Gilang Muhammad
Inflation fears have intensified significantly, with the near-term outlook in the New York Federal Reserve’s monthly survey reaching its highest level in nearly three and a half years as of September 2026. This surge in consumer anxiety is primarily driven by escalating energy costs and widespread utility rate hike requests, posing a complex challenge for Federal Reserve officials as they navigate monetary policy amidst persistent inflationary pressures. The economic landscape, marked by a delicate balance between price stability and economic growth, now faces renewed scrutiny as key indicators suggest consumers anticipate a prolonged period of elevated prices.
The New York Fed’s Survey: A Deeper Dive into Consumer Sentiment
The central bank’s Survey of Consumer Expectations (SCE), a crucial gauge of household sentiment regarding economic conditions, provided stark insights into the escalating inflation outlook. The median expectation for inflation over the next 12 months jumped to 3.9% in September, marking a 0.3 percentage point increase from August. This figure represents the highest level recorded since May 2023, when the expectation stood at 4.1%, signaling a concerning re-acceleration in short-term inflationary perceptions after a period of gradual moderation.
Beyond just prices, the survey also indicated a notable shift in household spending projections. Consumers now anticipate their spending growth to hit 5.5%, also a 0.3 percentage point rise month-over-month and the highest since May 2023. This dual increase in both expected inflation and spending growth presents a conundrum for policymakers. While increased spending might typically signal economic robustness, when coupled with heightened inflation expectations, it can fuel a self-fulfilling prophecy, where consumers accelerate purchases to beat future price increases, thereby further stoking demand and inflationary pressures.
The SCE, conducted by the Federal Reserve Bank of New York, is meticulously designed to capture the evolving perceptions of U.S. households on various economic variables, including inflation, labor market conditions, and household finance. Its findings are particularly influential because the Federal Reserve views consumer expectations as a critical driver of actual inflation. If consumers expect prices to rise, they may demand higher wages or accept higher prices, creating a feedback loop that can embed inflation more deeply into the economy. This makes the recent uptick in short-term expectations a significant concern for the Federal Open Market Committee (FOMC).
Interestingly, while near-term expectations have surged, the outlook appears somewhat better-anchored further out on the timeline. The three-year expectation for inflation edged up by a modest 0.1 percentage point to 3.3%, while the five-year view remained unchanged at 3%. This divergence suggests that while households anticipate immediate price pressures, there is still a degree of confidence that the Federal Reserve will eventually bring inflation back towards its long-term target over a broader horizon. However, the widening gap between short-term and long-term expectations underscores the immediate challenge faced by the Fed in maintaining its credibility in controlling inflation.
Energy Costs: The Primary Catalyst for Renewed Inflationary Pressures
At the heart of the intensifying inflation problem are surging energy costs, which have been a persistent source of price volatility throughout 2026. Data from the Bureau of Labor Statistics (BLS) for August 2026 revealed a significant increase in energy components, with gasoline prices rising by nearly 4% in that month alone. Fuel oil saw an even more dramatic surge, climbing by over 10%. These increases directly impact household budgets and ripple through the economy, affecting transportation costs for goods and services.
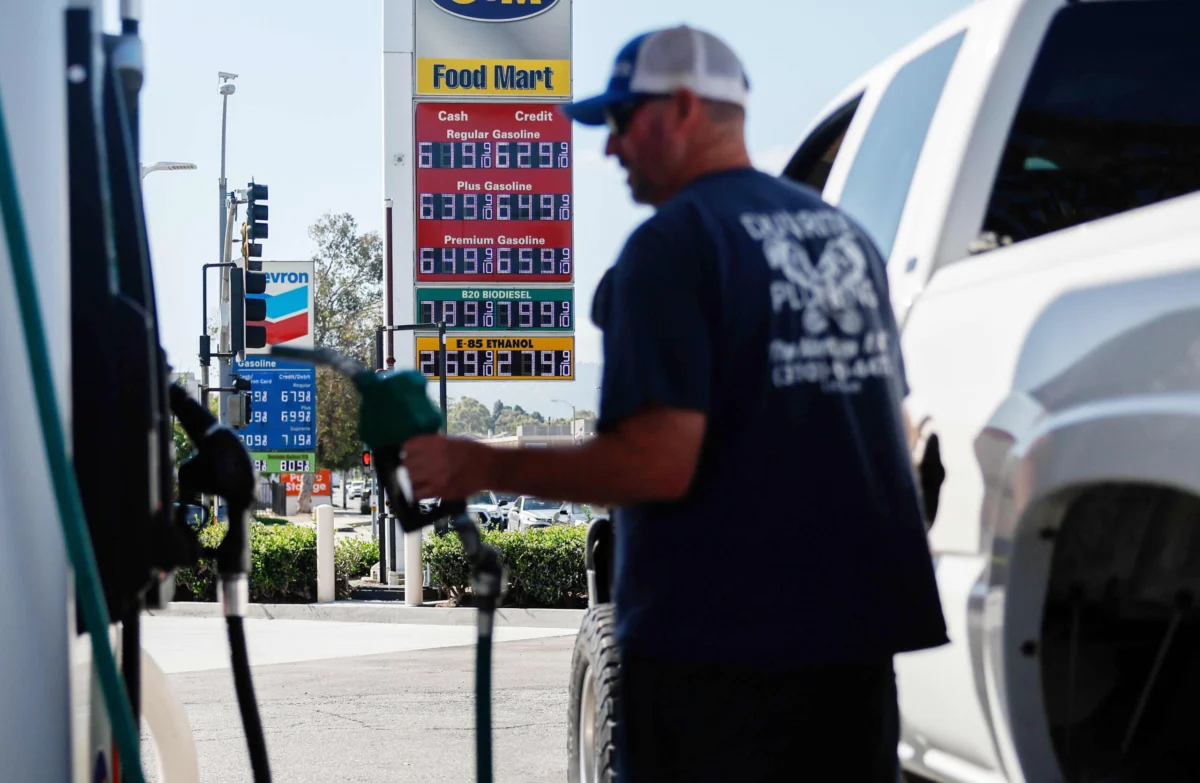
The visual evidence of this trend is stark: an Exxon gas station in Alexandria, Virginia, on October 2, 2026, displayed gas prices exceeding $4.70 per gallon, a tangible reflection of the broader energy cost inflation consumers are experiencing daily. The New York Fed survey confirmed this concern, finding that consumers expect gas prices to rise by 4.8% over the next year, an increase of 0.2 percentage point from their August projections. This widespread expectation of continued increases in fuel costs influences general inflation expectations, as gasoline is a highly visible and frequently purchased commodity.
Beyond direct fuel costs, utility expenses have also emerged as a significant inflationary factor. According to PoweLines, a nonpartisan consumer advocacy group, utilities across the nation have filed for an astounding $23.1 billion in rate increases so far in 2026. The third quarter alone witnessed requests totaling $4.5 billion, marking the largest sum for that period on record. These proposed increases, if approved, will further strain household budgets already contending with higher food and energy prices, embedding inflationary pressures into essential services. The cumulative effect of these energy and utility hikes creates a challenging environment for consumers, forcing them to re-evaluate discretionary spending and potentially leading to broader economic slowdowns if not addressed effectively.
The global energy market has been subject to various pressures throughout 2026, including geopolitical tensions, OPEC+ production decisions, and fluctuations in global demand. Supply chain disruptions, though eased from their peak during the pandemic, continue to contribute to cost pressures in certain sectors, including energy infrastructure and maintenance, indirectly affecting utility rates. These factors combined create a complex web of influences that push energy prices higher, translating directly into consumer inflation.
Market Signals Diverge: Breakevens and Treasury Yields Sound Alarms
While some Fed officials express patience, market-based indicators paint a less sanguine picture, particularly concerning longer-term inflation expectations and the cost of borrowing. One closely watched bond market indicator, known as the five-year breakeven inflation rate, has risen to around 2.35%, marking its highest level of the year. The breakeven rate, derived from the difference in yields between nominal Treasury bonds and Treasury Inflation-Protected Securities (TIPS), reflects what bond investors expect inflation to average over a specific period. A rising breakeven rate signals that the market anticipates higher inflation in the future, aligning more closely with the elevated consumer expectations for the short term.
Adding to the market’s unease, Treasury yields have been soaring in recent weeks, hitting levels not seen since the early part of the century. This dramatic ascent in yields across the curve—particularly for longer-dated bonds—is a critical development. Higher Treasury yields indicate that investors are demanding greater compensation for holding government debt, reflecting increased concerns about inflation, larger government borrowing needs, and expectations for higher interest rates from the Federal Reserve over an extended period. For instance, the 10-year Treasury yield, a benchmark for various lending rates, has moved significantly higher, impacting everything from mortgage rates to corporate borrowing costs. These elevated yields could cool economic activity by making borrowing more expensive for businesses and consumers, potentially leading to a slowdown in investment and spending.
The current Federal funds rate target stands between 3.75%-4%. However, market participants, as reflected in Fed funds futures contracts, are pricing in a much more aggressive central bank in the years ahead. These contracts imply a rate of 5.58% in five years, suggesting that traders anticipate the Fed will need to raise rates further from current levels and maintain them at a higher plateau for a considerable duration to effectively combat inflation. This divergence between the Fed’s current "wait and see" stance and the market’s expectation of sustained hawkishness underscores the challenge of communicating monetary policy and managing inflation expectations effectively.
The Federal Reserve’s Delicate Balancing Act
The survey results come at a critical juncture, with Fed officials grappling over the proper setting of monetary policy as inflation continues to hold well above the central bank’s 2% target. The Federal Reserve operates under a dual mandate: achieving maximum employment and maintaining price stability. Balancing these two objectives becomes particularly challenging when inflation is high, and the economy shows signs of both resilience and potential vulnerability.
Markets largely anticipate the Federal Open Market Committee (FOMC) to keep benchmark rates steady when it meets later in October. This expectation is partly supported by the fact that inflation in August, as measured by the Fed’s preferred gauge—the Personal Consumption Expenditures (PCE) price index—came in lower than expected, particularly the core PCE which strips out volatile food and energy prices. This provided some policymakers with a glimmer of hope that underlying inflationary pressures might be moderating.
In recent days, several key officials, including New York Fed President John Williams, have publicly stated that policymakers can afford to take their time when evaluating where interest rates should be set. This sentiment reflects a desire to avoid overtightening, which could push the economy into an unnecessary recession. Proponents of patience argue that monetary policy operates with long and variable lags, meaning the full effect of past rate hikes is yet to be realized. They also point to the potential for supply-side improvements and base effects to naturally bring inflation down over time. Furthermore, focusing on "core" inflation, which excludes the volatile energy and food sectors, provides a clearer picture of underlying price trends, and core inflation has shown signs of deceleration.
However, the recent surge in consumer inflation expectations and the persistent strength in energy prices could challenge this patient approach. If inflation expectations become unanchored, it could lead to a wage-price spiral, making it significantly harder and more painful to bring inflation back down. The Fed’s credibility as an inflation fighter is paramount, and a prolonged period of high inflation could erode public trust and necessitate more drastic measures in the future. The FOMC’s upcoming meeting will undoubtedly involve a robust debate between those advocating for continued vigilance against inflation and those prioritizing the avoidance of a recessionary downturn.
Historical Context and the Fight Against Inflation
The current inflationary environment draws parallels with historical periods where central banks faced similar dilemmas. The 1970s, for instance, saw a prolonged period of high inflation, partly fueled by energy shocks and unanchored inflation expectations. The Federal Reserve, under Chairman Paul Volcker in the early 1980s, eventually had to implement aggressive interest rate hikes, leading to a recession but ultimately restoring price stability and the Fed’s credibility. While the current situation differs in many aspects, the lesson about the importance of managing expectations remains highly relevant.
Since the global financial crisis of 2008 and particularly during the COVID-19 pandemic, the Federal Reserve maintained an accommodative monetary policy, including near-zero interest rates and quantitative easing, to support economic recovery. However, the unprecedented fiscal stimulus, coupled with supply chain disruptions and a surge in demand post-lockdowns, ignited inflationary pressures that began to manifest strongly in 2021 and 2022. The Fed initially characterized this inflation as "transitory" but later acknowledged its persistence, leading to a rapid series of rate hikes starting in early 2022.
The battle against inflation has been a multi-year effort, marked by significant increases in the federal funds rate from near zero to the current target range of 3.75%-4%. While headline inflation has retreated from its 2022 peak, its stubborn persistence above the 2% target, coupled with the latest surge in consumer expectations, signals that the fight is far from over. The Fed’s current challenge is to achieve a "soft landing"—cooling the economy enough to bring inflation down without triggering a severe recession. This delicate act requires precise calibration of monetary policy, a keen understanding of economic data, and effective communication to manage public and market expectations.
Implications for Households and the Broader Economy
The sustained period of elevated inflation and rising interest rates carries significant implications for various sectors of the economy and for individual households.
For consumers, the most immediate impact is the erosion of purchasing power. Higher prices for essentials like gasoline, food, and utilities mean that household budgets are stretched further, leaving less disposable income for discretionary spending, savings, or investment. This can lead to a decline in living standards, particularly for low-income households who spend a larger proportion of their income on necessities. The expectation of continued price increases might also alter consumer behavior, potentially leading to delays in large purchases or a shift towards cheaper alternatives.
Businesses face a dual challenge. On one hand, they contend with higher input costs, including energy, raw materials, and potentially labor, as workers demand higher wages to offset inflation. This compresses profit margins unless they can pass these costs onto consumers through higher prices, which risks further fueling inflation. On the other hand, higher interest rates make borrowing more expensive, impacting investment decisions, expansion plans, and the ability to refinance existing debt. Small and medium-sized enterprises, often more reliant on variable-rate loans, can be particularly vulnerable to these pressures.
The housing market is directly affected by rising Treasury yields, which typically translate into higher mortgage rates. This makes homeownership less affordable, potentially cooling demand and impacting home prices. For existing homeowners, higher rates can make refinancing less attractive.
For the broader economy, persistent inflation and aggressive monetary tightening pose the risk of a recession. If the Fed overshoots in its efforts to tame inflation, it could lead to a significant contraction in economic activity and job losses. There are also concerns about "stagflation," a scenario characterized by high inflation coupled with slow economic growth and high unemployment, reminiscent of the 1970s. While current labor market conditions remain relatively strong, a prolonged period of high rates could eventually weaken employment.
Looking Ahead: The Path for Monetary Policy
The coming months will be crucial for observing how these inflationary pressures evolve and how the Federal Reserve responds. The FOMC’s October meeting will be closely watched for any shifts in sentiment or policy guidance. While a pause in rate hikes is widely expected, the accompanying statement and press conference by the Fed Chair will be scrutinized for clues about future policy trajectory.
The Federal Reserve’s credibility in achieving its 2% inflation target hinges on its ability to both respond to current economic data and effectively manage expectations. The recent surge in consumer inflation expectations signals that the public believes the battle against inflation is far from over, and that current policy may not be sufficient to bring prices back down swiftly. This perception could force the Fed to adopt a more hawkish stance than it currently prefers, potentially necessitating further rate increases or a longer period of elevated rates than previously anticipated by some policymakers.
The path ahead remains uncertain, characterized by the interplay of persistent supply-side cost pressures, evolving consumer expectations, and the ongoing debate within the central bank about the appropriate balance between fighting inflation and preserving economic growth. The global economic environment, including energy markets and geopolitical developments, will also continue to play a significant role in shaping the inflationary landscape. Ultimately, the Federal Reserve’s response to these complex dynamics will determine the trajectory of inflation and the broader economic health in the coming years.