Ena Muazin
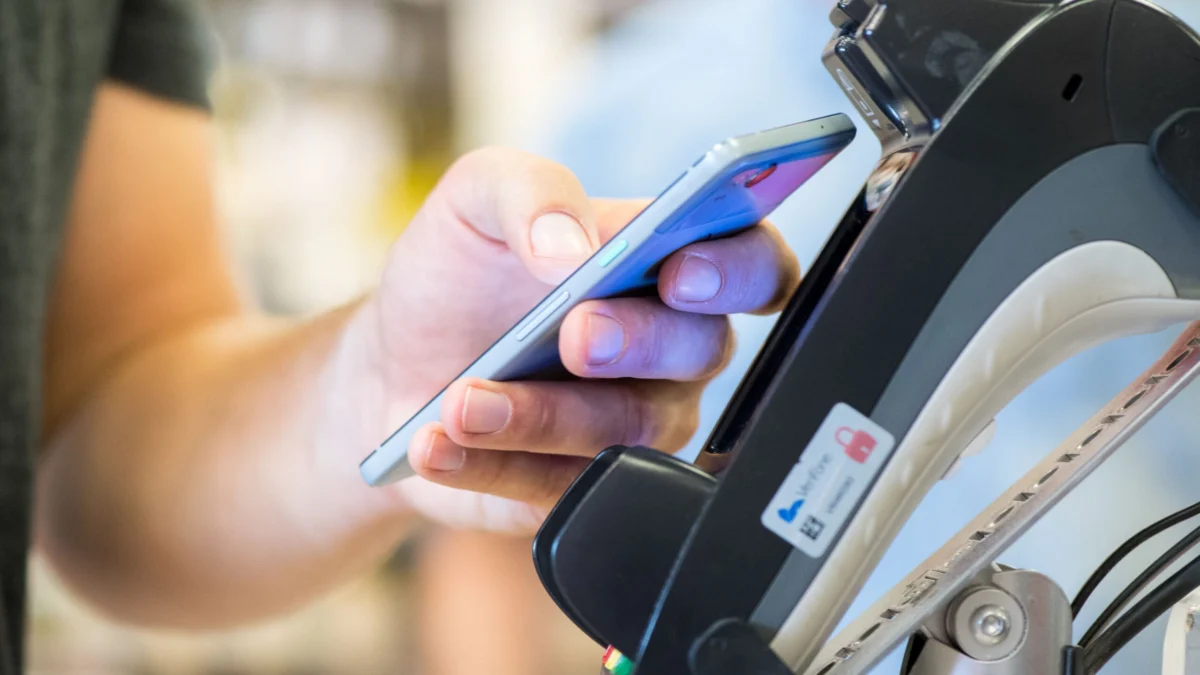
Neu-Isenburg, Germany – A significant and growing portion of the German adult population experienced difficulties with cashless payments this year, with over half reporting at least one instance where they were unable to pay electronically as desired. A recent YouGov survey, commissioned by the Genoverband, revealed that 56 percent of adults faced such issues, a notable increase from 45 percent in 2021. This trend is fueling a crucial debate about payment accessibility and the potential for mandatory acceptance of both digital and physical tender by businesses.
The survey, which involved a representative sample of 1,534 adults in August, found that the majority of those compelled to use cash instead of their preferred card or smartphone payment methods reported experiencing between two and five such incidents over the course of the year. This highlights a recurring frustration for a substantial segment of consumers, suggesting that the infrastructure or willingness to accept diverse payment options is not universally in place.
In response to these growing concerns and the broader push towards digitalization, Federal Finance Minister Lars Klingbeil (SPD) has signaled his intention to introduce legislation mandating that shops and restaurants accept digital payments via card or mobile phone in addition to cash. While the specific details of this proposed regulation are still under discussion, the Ministry of Finance aims to have a draft bill approved by the cabinet before the end of the year, with implementation targeted for 2027.
The Rationale Behind Mandatory Digital Payment Acceptance
The push for mandatory digital payment acceptance is driven by several key factors, both from a consumer and a governmental perspective. For consumers, the ability to pay with their preferred method offers convenience and flexibility. However, the YouGov survey indicates that this flexibility is not always available, leading to potential lost sales for businesses and frustration for customers.
From the state’s perspective, the advantages of widespread digital payment adoption are significant, particularly in combating illicit financial activities. As digital transactions are inherently traceable, they make tax evasion and money laundering considerably more difficult. This increased transparency can lead to a more robust tax base and a stronger defense against criminal financial operations. The German government views this as a crucial step in modernizing the financial landscape and enhancing regulatory oversight.
Industry Perspectives: A Divided Opinion Among Cooperative Banks
The proposed mandate for digital payment acceptance garners significant support among the executive boards of cooperative banks within the Genoverband’s purview, which encompasses all German federal states except Bavaria and Baden-Württemberg. A substantial three-quarters (77 percent) of the 196 surveyed board members expressed their approval for such a regulation. This indicates a general understanding within the cooperative banking sector of the benefits and inevitability of digital payment integration.
However, the perspective on cash acceptance is more nuanced. While supporting digital payments, nearly half (49 percent) of these same board members also advocate for a continued obligation for businesses to accept cash up to a certain maximum limit. This suggests a recognition of the continued importance of cash for a segment of the population, potentially including older individuals, those with limited access to digital banking, or for privacy-conscious transactions. The balancing act between promoting digital innovation and ensuring financial inclusion for all remains a key consideration.
Underlying Trends: The Evolving Payment Landscape in Germany
Germany has historically maintained a strong affinity for cash, often cited as a bastion of physical currency in an increasingly digital world. However, global trends and technological advancements are gradually shifting consumer behavior. The COVID-19 pandemic, in particular, accelerated the adoption of contactless and digital payment methods as consumers and businesses sought to minimize physical contact.
Despite this shift, cash remains a vital part of the German economy. It offers a degree of anonymity and privacy that digital payments cannot replicate, and it is particularly important for small transactions and for individuals who may not have access to or be comfortable with digital financial tools. The current situation, where cashless payment attempts are being thwarted, points to a disconnect between the evolving desires of consumers and the actual payment infrastructure and policies in place across various businesses.
Chronology of Payment Debates and Policy Developments
The discussion surrounding payment methods in Germany is not new. For years, there have been debates about the declining use of cash and the increasing reliance on digital alternatives.
- Pre-2020: A gradual increase in card and mobile payment adoption, but cash remained dominant for everyday transactions. Concerns about data privacy and digital exclusion were already present.
- 2020-2021: The COVID-19 pandemic significantly boosted the adoption of contactless and digital payments. Many businesses temporarily favored non-cash transactions. The YouGov survey in 2021 indicated 45% of adults faced cashless payment issues.
- 2022: A slight rebound in cash usage in some sectors as pandemic restrictions eased, but digital payment habits had become more ingrained for many.
- 2023 (Current Year): The YouGov survey reveals a significant uptick in cashless payment failures, with 56% of adults experiencing issues. This data point appears to be a key catalyst for the current policy discussions.
- Late 2023: Federal Finance Minister Lars Klingbeil announces plans for mandatory digital payment acceptance. The Ministry of Finance begins drafting legislation with a target for cabinet approval by year-end and implementation in 2027.
- Ongoing: Discussions and consultations with stakeholders, including industry associations, consumer groups, and financial institutions, are expected to shape the final form of the legislation.
This timeline illustrates a dynamic shift, where initial trends towards digitalization are now being met with a reactive policy approach driven by observed consumer frustrations and the potential for increased financial transparency.
Analysis of Implications: Navigating the Future of Payments
The proposed mandate for mandatory digital payment acceptance carries several significant implications for businesses, consumers, and the German economy as a whole.
For Businesses:
- Increased Costs: Implementing new payment terminals and integrating digital payment systems can incur significant costs, particularly for small and medium-sized enterprises (SMEs).
- Operational Adjustments: Businesses will need to ensure their staff are trained to handle various digital payment methods and troubleshoot any technical issues.
- Potential for Increased Sales: By offering more payment options, businesses could potentially attract a wider customer base and reduce instances of lost sales due to payment method limitations.
- Enhanced Security: Digital payment systems often come with enhanced security features, potentially reducing risks associated with handling large amounts of cash.
For Consumers:
- Greater Convenience: Consumers will have more freedom to choose their preferred payment method, leading to a smoother shopping experience.
- Financial Inclusion Concerns: A key challenge will be ensuring that individuals who rely on cash, such as the elderly, low-income individuals, or those without bank accounts, are not further marginalized. The proposed mandate needs to strike a balance to ensure continued access to essential goods and services for all.
- Data Privacy: Increased digital transactions raise ongoing concerns about data privacy and the potential for misuse of personal financial information. Robust data protection regulations will be crucial.
For the German Economy:
- Reduced Shadow Economy: The move towards greater digital payments is expected to further shrink the informal economy, leading to increased tax revenues and a more equitable distribution of the tax burden.
- Modernization of Financial Infrastructure: The mandate will likely accelerate the modernization of Germany’s payment infrastructure, aligning it more closely with international standards.
- Potential for Innovation: A more digitalized payment landscape could foster further innovation in financial technology (FinTech) within Germany.
The success of this legislative push will depend on careful consideration of these implications and the development of a framework that is both effective in its objectives and inclusive in its reach. The timeline for implementation, set for 2027, allows for a period of adaptation and preparation for businesses and consumers alike. The coming years will be critical in shaping how Germany navigates this significant shift in its payment culture.