Ena Muazin
For couples who share their lives, living spaces, and often their daily finances through joint checking accounts, the question of pooling investment assets, particularly Exchange Traded Funds (ETFs), naturally arises. While the concept of a joint ETF savings plan is straightforward, the establishment of joint investment depots is less common than joint bank accounts, presenting both potential advantages and considerations for couples. This article delves into the intricacies of joint investment depots, exploring who stands to benefit most and when it is more prudent to maintain separate financial holdings.
The growing popularity of ETFs has made them an attractive investment vehicle for a wide range of individuals, including couples looking to build wealth together. ETFs offer diversification, low costs, and accessibility, making them a cornerstone of modern investment strategies. As financial interdependence grows within a partnership, the desire to consolidate financial management, including investments, becomes a logical next step for many. However, the decision to open a joint depot for ETFs is not one to be taken lightly and requires careful consideration of individual circumstances, financial goals, and the dynamics of the relationship.
Understanding Joint Investment Depots
A joint investment depot, much like a joint bank account, allows two or more individuals to have shared ownership and control over an investment portfolio. In the context of ETFs, this means that both partners can contribute to, manage, and withdraw from the same investment account. This can simplify financial planning, consolidate investment tracking, and foster a sense of shared financial responsibility.
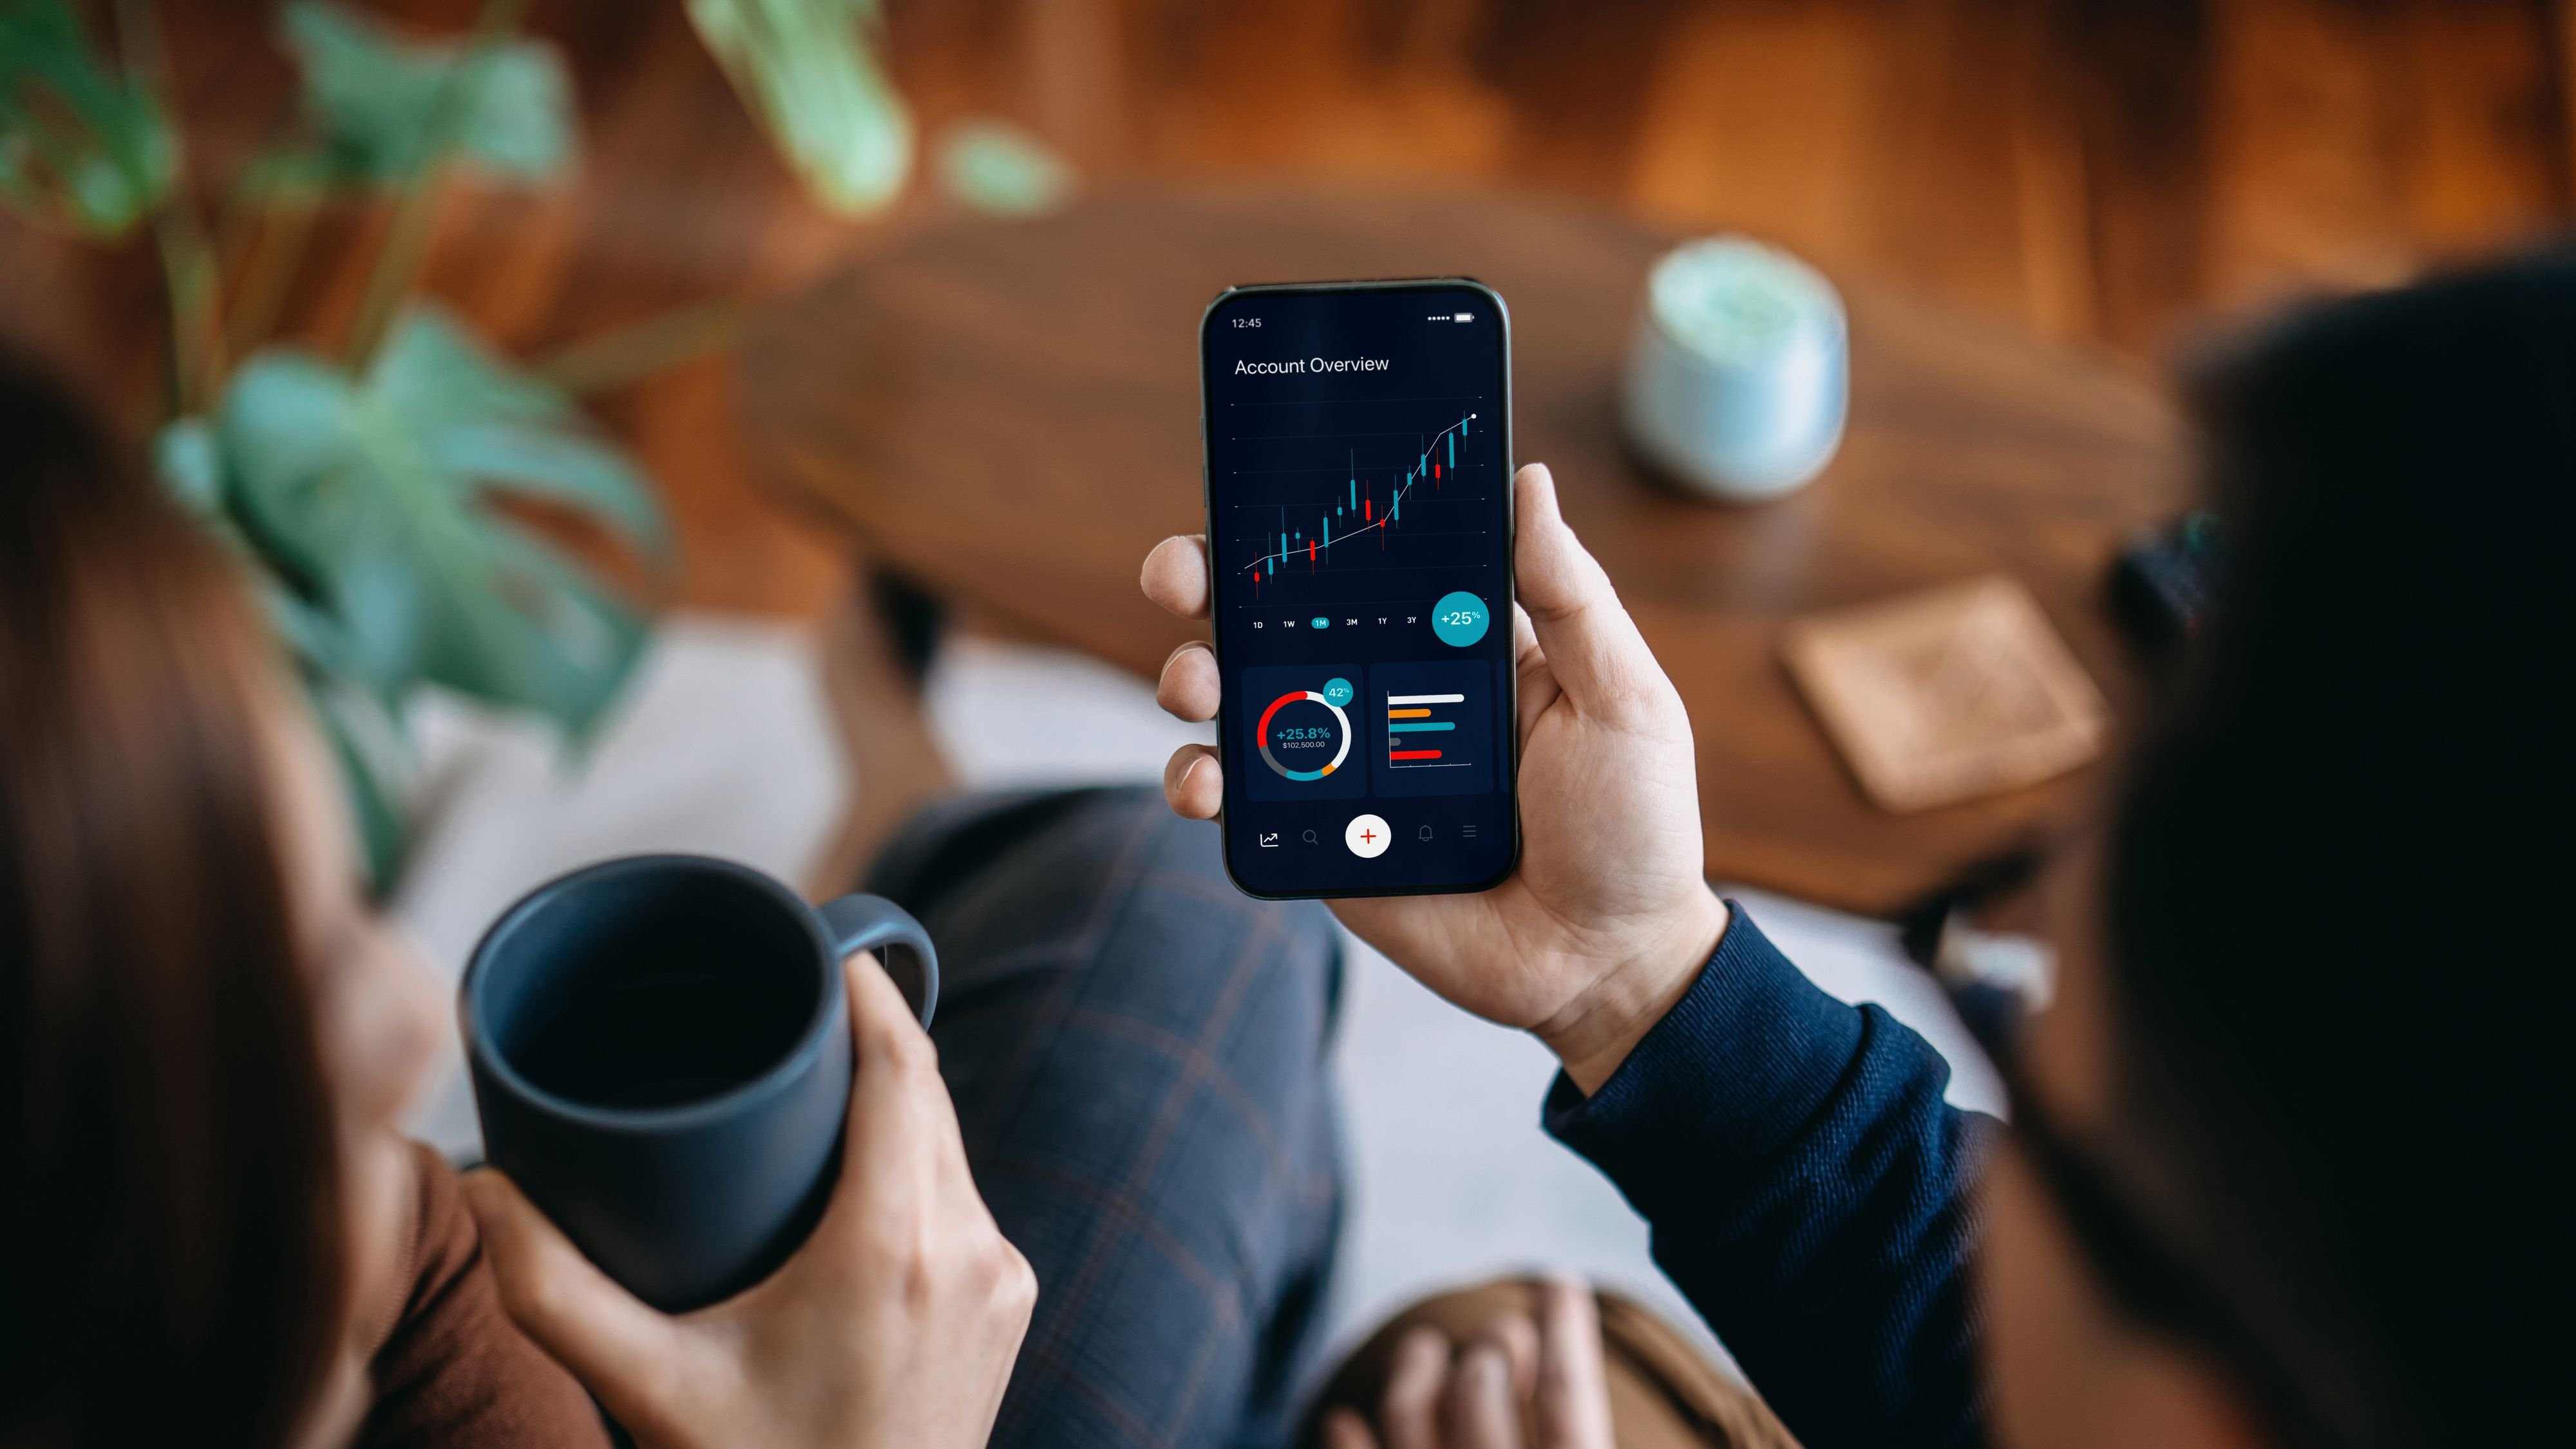
The underlying principle is similar to managing joint household expenses or savings. When a couple decides to merge their financial lives, they often seek ways to streamline these processes. A joint depot can be seen as an extension of this philosophy, allowing for unified investment strategies and a singular view of their collective wealth-building efforts.
Key Features and Benefits of Joint Depots:
- Simplified Management: A single account reduces the administrative burden of managing multiple investment portfolios, making it easier to track performance, rebalance assets, and manage contributions.
- Shared Financial Goals: Joint depots can be instrumental in working towards shared financial objectives, such as saving for a down payment on a property, funding children’s education, or building a retirement nest egg together. This shared endeavor can strengthen the couple’s financial partnership.
- Estate Planning Advantages: In the event of the death of one partner, a joint depot can often simplify the transfer of assets to the surviving partner, potentially avoiding lengthy probate processes, depending on the jurisdiction and the specific account structure.
- Potential for Joint Decision-Making: The existence of a joint depot encourages open communication and collaborative decision-making regarding investment strategies, risk tolerance, and financial planning.
When a Joint Depot May Be Advantageous
The decision to opt for a joint ETF depot is often driven by specific relationship stages and financial objectives. Couples who are deeply integrated financially, perhaps already sharing a mortgage, utilities, and significant savings, may find a joint depot a natural progression.
Scenario 1: Established Partnerships with Merged Finances
For couples who have been together for an extended period, have a high degree of trust, and have largely merged their financial lives, a joint depot can be a logical and efficient solution. This includes individuals who:
- Share a significant portion of their income and expenses.
- Have common long-term financial goals.
- Exhibit strong communication and agreement on financial matters.
In such cases, managing a joint depot can consolidate their investment efforts, making it easier to monitor progress towards their shared objectives. For instance, if a couple is saving for a joint retirement fund or a significant purchase like a vacation home, a single depot can streamline contributions and provide a clear overview of their collective progress.

Scenario 2: Building Wealth for Shared Future Goals
The pursuit of ambitious financial milestones often necessitates a coordinated approach. Whether it’s accumulating a down payment for a property, planning for children’s higher education, or simply aiming to build substantial wealth for future financial security, a joint depot can serve as a powerful tool. By pooling resources, couples can potentially reach these goals faster, especially if they can leverage economies of scale in terms of investment management fees or if one partner has more disposable income to contribute. The act of investing together can also reinforce their commitment to these shared aspirations.
Scenario 3: Simplifying Estate Planning
While often overlooked in the early stages of a relationship, estate planning becomes increasingly important as couples mature and their assets grow. A joint depot, particularly one structured with the right of survivorship, can significantly simplify the process of transferring assets to the surviving spouse. This can help avoid the complexities and delays associated with probate, ensuring a smoother transition of wealth. It is crucial, however, to understand the specific legal implications and account titling in your jurisdiction to ensure the intended outcome.
When Separate Depots Might Be More Prudent
Despite the appeal of shared finances, there are several valid reasons why maintaining separate investment depots might be a more suitable approach for some couples. These situations often arise when there is a need for financial autonomy, a divergence in investment strategies, or specific legal or tax considerations.
Scenario 1: Maintaining Financial Autonomy and Individual Control
In some partnerships, individuals may value their financial independence, even within a committed relationship. This can stem from personal financial histories, differing risk appetites, or a desire to have control over a portion of their assets. In such cases, separate depots allow each partner to manage their investments according to their individual preferences and comfort levels. This can prevent potential disagreements about investment choices and maintain a sense of personal financial agency.
Scenario 2: Divergent Investment Philosophies and Risk Tolerances
Couples do not always share the same views on investing. One partner might be risk-averse, preferring conservative investments, while the other may be more comfortable with higher-risk, higher-reward strategies. Attempting to reconcile these differing philosophies within a single joint depot can lead to compromises that satisfy neither party or, worse, to ongoing conflict. Separate depots allow each individual to pursue their own investment strategy without needing to gain consensus from their partner on every decision. This can be particularly relevant for individuals with established, long-term investment portfolios that they are reluctant to alter significantly.
Scenario 3: Pre-existing Assets and Individual Responsibilities
If one or both partners bring substantial pre-existing assets into the relationship, or if there are ongoing individual financial obligations (e.g., child support from a previous marriage, personal business investments), managing these separately can be simpler and clearer. A joint depot might complicate the accounting and tracking of these distinct financial streams. Furthermore, if there are specific tax implications associated with individual assets or income, keeping them separate might offer more advantageous tax planning opportunities.
Scenario 4: Legal and Inheritance Considerations
In certain legal frameworks or for individuals with complex family structures, maintaining separate depots might be crucial for estate planning and inheritance purposes. For example, if a partner wishes to ensure that specific assets are passed on to particular beneficiaries outside of the current partnership, keeping those assets in a separate, individually controlled depot would be essential. Similarly, in jurisdictions with community property laws, the distinction between separate and joint assets can be critical in the event of divorce or death.
Practicalities of Setting Up and Managing Joint ETF Depots
For couples who decide a joint depot is the right path, several practical considerations come into play.
Choosing the Right Brokerage
The first step is selecting a brokerage that offers joint account options and is suitable for ETF investing. Key factors to consider include:
- Account Types: Ensure the brokerage offers joint taxable brokerage accounts and potentially joint IRAs if the investments are intended for retirement.
- Investment Offerings: Verify that the brokerage has a wide selection of ETFs, including those that align with your investment strategy.
- Fees and Costs: Compare trading fees, account maintenance fees, and expense ratios of ETFs offered.
- User Interface and Tools: A user-friendly platform with good research tools and reporting can enhance the investment experience.
- Customer Support: Reliable customer support is essential for resolving any issues that may arise.
Account Titling and Ownership Structure
When opening a joint account, the titling is critical. Common options include:
- Joint Tenants with Rights of Survivorship (JTWROS): This is the most common form for married couples. In the event of one owner’s death, the assets automatically pass to the surviving owner, bypassing probate.
- Tenants in Common (TIC): Each owner holds a specific share of the assets. In the event of death, their share passes to their heirs as specified in their will, not automatically to the other account holder.
It is vital to consult with a financial advisor or legal professional to determine the most appropriate titling based on your specific circumstances and local laws.
Contribution and Withdrawal Management
Establishing clear guidelines for contributions and withdrawals is paramount to avoid disputes. This could involve:
- Proportional Contributions: Both partners contribute a percentage of their income or a fixed amount to the joint depot.
- Equal Contributions: Both partners contribute the same amount.
- Designated Contribution Sources: Agreeing on which partner’s income or savings will fund the joint depot.
Similarly, clear rules should be established for withdrawals, outlining whether both partners must approve all withdrawals, or if certain thresholds allow for unilateral action.
Investment Strategy and Decision-Making
Before investing, a thorough discussion about investment goals, risk tolerance, and time horizon is essential. This collaborative approach ensures that the investment strategy reflects the shared objectives of both partners. Regular reviews of the portfolio and investment strategy are also crucial to ensure they remain aligned with evolving goals and market conditions.
The Broader Economic Context: ETFs and Financial Planning in the Digital Age
The rise of joint ETF depots is part of a broader trend towards digital financial management and increased financial literacy among the general population. Online brokerages and robo-advisors have democratized investing, making it more accessible than ever before. This has empowered couples to take a more active role in their financial planning and wealth accumulation.
The availability of low-cost ETFs has also been a significant driver. Historically, diversified investment portfolios were often accessible only to wealthier individuals due to high minimum investment requirements and management fees. ETFs, by contrast, allow individuals to invest in diversified baskets of securities with relatively small sums of money. This accessibility makes them an ideal vehicle for couples looking to build wealth steadily over time.
Furthermore, the digital age has fostered a culture of transparency and shared financial information. Couples are increasingly comfortable discussing their finances openly, which facilitates joint decision-making and the adoption of shared financial tools like joint investment accounts.
Data Insights on ETF Adoption
Recent industry data highlights the growing appeal of ETFs. According to various financial reports, the global ETF market has seen consistent growth, with assets under management reaching trillions of dollars. This surge is attributed to factors such as investor demand for low-cost diversification, the ease of trading, and the increasing range of thematic and sector-specific ETFs available. While specific data on joint ETF depot adoption is scarce, the overall increase in ETF investing by individuals and households suggests a parallel trend in shared investment accounts.
Analysis of Implications: A Double-Edged Sword
The decision to establish a joint ETF depot can be a powerful catalyst for shared financial success, fostering a deeper partnership and accelerating the achievement of common goals. It can simplify complex financial management and provide a clear, unified path toward wealth accumulation.
However, it is not without its risks. A poorly managed joint account, stemming from a lack of clear communication, differing financial philosophies, or unresolved trust issues, can become a source of significant marital discord. The potential for disputes over contributions, withdrawals, or investment choices can strain even the strongest relationships.
Therefore, the success of a joint ETF depot hinges on a foundation of strong communication, mutual trust, and a shared understanding of financial goals and responsibilities. It requires ongoing dialogue and a willingness to compromise. For couples who can navigate these complexities effectively, a joint depot can be an invaluable tool for building a secure and prosperous financial future together.
Future Trends in Joint Financial Management
Looking ahead, we may see further innovation in how couples manage their finances collectively. This could include more sophisticated joint account management tools, integrated financial planning platforms designed for couples, and potentially even AI-driven financial advisors that cater to the specific needs of partnerships. The trend towards financial integration within relationships is likely to continue, driven by technology and evolving societal norms.
In conclusion, the decision to open a joint ETF depot is a significant one that should be approached with careful consideration. While it offers numerous benefits for integrated couples, it is essential to weigh these against the potential challenges and ensure that it aligns with the unique dynamics and financial philosophies of the partnership. Open communication, mutual respect, and a shared vision for the future are the cornerstones of success, whether financial assets are managed jointly or separately.