Ena Muazin
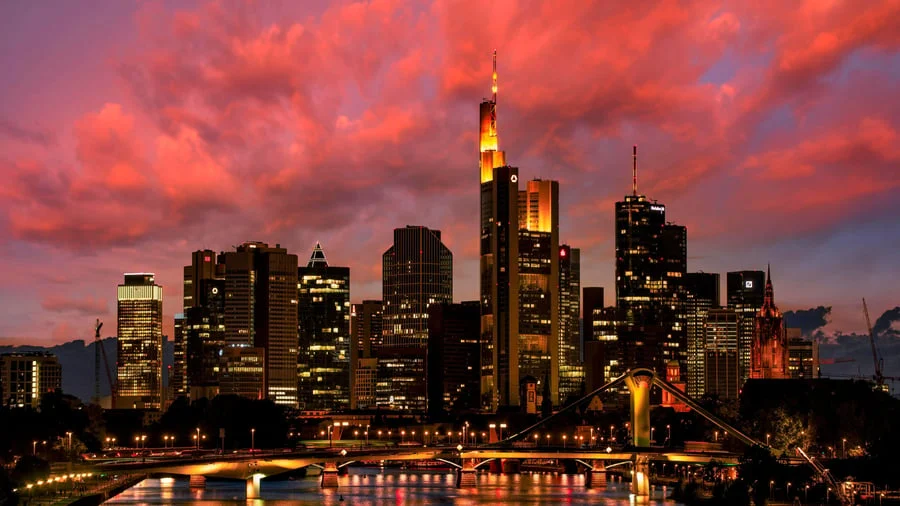
Frankfurt – Deutsche Bank is poised to capitalize on the evolving European banking landscape, with a significant opportunity emerging from the potential takeover of Commerzbank by Italian banking giant UniCredit. The German lender views the prospect of a major competitor being absorbed as a chance to enhance its own market position and growth potential.

Alexander von zur Mühlen, a board member at Deutsche Bank, expressed this strategic outlook in an interview with Handelsblatt on the sidelines of the International Monetary Fund (IMF) and World Bank annual meetings in Bangkok. "We see the planned takeover as an opportunity," von zur Mühlen stated, highlighting the bank’s forward-thinking approach to market dynamics. He further elaborated, "When a competitor disappears in certain segments, our responsibility as Deutsche Bank naturally increases, and so does our growth potential." This statement underscores a calculated strategy to leverage consolidation within the European banking sector for its own advancement.
The potential for UniCredit to acquire a controlling stake in Commerzbank has taken a significant step forward, with regulatory approval from the European Central Bank (ECB) clearing a crucial hurdle. This green light from the ECB allows UniCredit to increase its stake in Commerzbank beyond the 30 percent threshold, without an immediate upper limit. This development signifies a pivotal moment, bringing a potential full-scale takeover closer to reality and setting the stage for a reshaped German and European financial market.
Background and Regulatory Developments
The intricate dance of European banking consolidation has been a recurring theme, with regulatory bodies playing a crucial role in shaping the sector’s future. The ECB’s supervisory authority over major European banks means that any significant acquisition or stake increase requires their explicit approval. In this instance, the ECB’s decision on UniCredit’s Commerzbank stake is a critical enabler for the Italian bank’s ambitions.
UniCredit, a prominent banking group with a strong presence across Europe, has been strategically expanding its footprint. Commerzbank, a cornerstone of the German financial system, has faced its own set of challenges and strategic reviews in recent years, making it a target for consolidation. The ECB’s approval to allow UniCredit to surpass the 30 percent ownership threshold is not merely a procedural step; it signals a calculated assessment by the central bank that the move aligns with broader financial stability objectives and does not pose an undue risk to the market.
The 30 percent threshold is often significant in corporate governance, as exceeding it can trigger mandatory takeover bids and grant substantial influence over the target company’s strategic direction. By allowing UniCredit to move beyond this, the ECB has implicitly endorsed the Italian bank’s potential to exert greater control over Commerzbank, paving the way for more substantial integration or a full acquisition.
Strategic Implications for Deutsche Bank
For Deutsche Bank, the potential consolidation presents a clear strategic advantage. The German banking sector, in particular, has been undergoing a period of introspection and restructuring. The presence of two major German banks, Deutsche Bank and Commerzbank, has often led to intense competition, sometimes at the expense of profitability.
If Commerzbank were to become part of UniCredit, it would fundamentally alter the competitive landscape in Germany. Deutsche Bank, as the largest remaining German-headquartered international financial institution, would find itself in a stronger relative position. This could translate into increased market share in domestic lending, corporate banking, and wealth management services within Germany.
Furthermore, the departure of a significant competitor could reduce pressure on pricing and margins, potentially improving profitability for Deutsche Bank. The bank’s leadership has been vocal about its strategy to focus on core strengths, enhance efficiency, and drive profitability. This potential consolidation aligns perfectly with such objectives, offering a pathway to achieve these goals through external market dynamics rather than solely through internal restructuring.

Broader European Banking Context
The move by UniCredit and the anticipated reaction from Deutsche Bank are part of a larger trend of consolidation within the European banking sector. For years, European banks have grappled with lower profitability, regulatory burdens, and the need to adapt to a rapidly changing digital landscape. Mergers and acquisitions have been viewed as a means to achieve economies of scale, reduce costs, and enhance competitiveness, particularly against larger global players.
The German banking market, in particular, has been characterized by a fragmented structure, with a mix of large private banks, public sector banks, and cooperative banks. While there have been attempts at consolidation in the past, such as the failed merger talks between Deutsche Bank and Commerzbank in 2019, the underlying pressures for consolidation remain. The current development suggests that external forces, rather than purely domestic initiatives, might be the primary drivers of future consolidation in Germany.
The ECB’s role in facilitating such cross-border consolidation is crucial. By allowing a major Italian bank to acquire a significant stake in a German counterpart, the ECB is signaling a willingness to foster a more integrated European banking market, which could lead to stronger, more resilient pan-European financial institutions.
Potential Challenges and Future Outlook
While Deutsche Bank views the situation as an opportunity, the actualization of this potential will depend on several factors. The success of UniCredit’s potential takeover of Commerzbank is not guaranteed and will involve complex negotiations, regulatory approvals, and integration challenges. The operational and cultural integration of two large banking entities is a formidable task, often fraught with unforeseen difficulties.
Moreover, the reaction of other market participants, including smaller regional banks and fintech companies, will also shape the future competitive environment. While Deutsche Bank stands to benefit from the potential departure of Commerzbank as a direct competitor, the increased presence of a strong pan-European player like UniCredit could also introduce new competitive dynamics.
The strategic positioning of Deutsche Bank will require continued focus on its core competencies, digital transformation, and risk management. The bank must be prepared to not only absorb potential new business but also to innovate and adapt to evolving customer needs and technological advancements.
The coming months will likely be critical in determining the trajectory of this significant development. The banking sector in Germany and across Europe is at a crossroads, and the strategic maneuvers of major players like Deutsche Bank and UniCredit will undoubtedly play a pivotal role in shaping its future. The expectation within Deutsche Bank is clear: to leverage the shifts in the competitive landscape to its own advantage, reinforcing its position as a leading financial institution in Europe.