Gilang Muhammad
The economic spotlight intensified on Friday as the Bureau of Labor Statistics (BLS) prepared to unveil its closely watched nonfarm payrolls count for September, a report poised to offer critical insights into the resilience and trajectory of the U.S. labor market. Wall Street analysts, keenly observing every economic tremor, have coalesced around a consensus expectation of 84,000 new jobs added last month, with the unemployment rate anticipated to hold steady at 4.1%. This projected growth, while signaling a notable deceleration from the robust pre-2025 hiring trends, continues to place the jobless rate squarely within a range that Federal Reserve officials consider indicative of full employment.
The impending September figures arrive on the heels of a surprisingly vigorous August jobs report, which saw a gain of 162,000 nonfarm payrolls, further bolstered by upward revisions to previous months’ data. This sustained, albeit moderating, strength in employment has provided a complex backdrop for the Federal Reserve, which is grappling with the dual mandate of fostering maximum employment and maintaining stable prices. As central bank policymakers scrutinize the labor market’s robustness, a significant portion of their attention is simultaneously pivoting towards the more "nettlesome" challenge of persistent inflation, suggesting a nuanced approach to future monetary policy decisions.
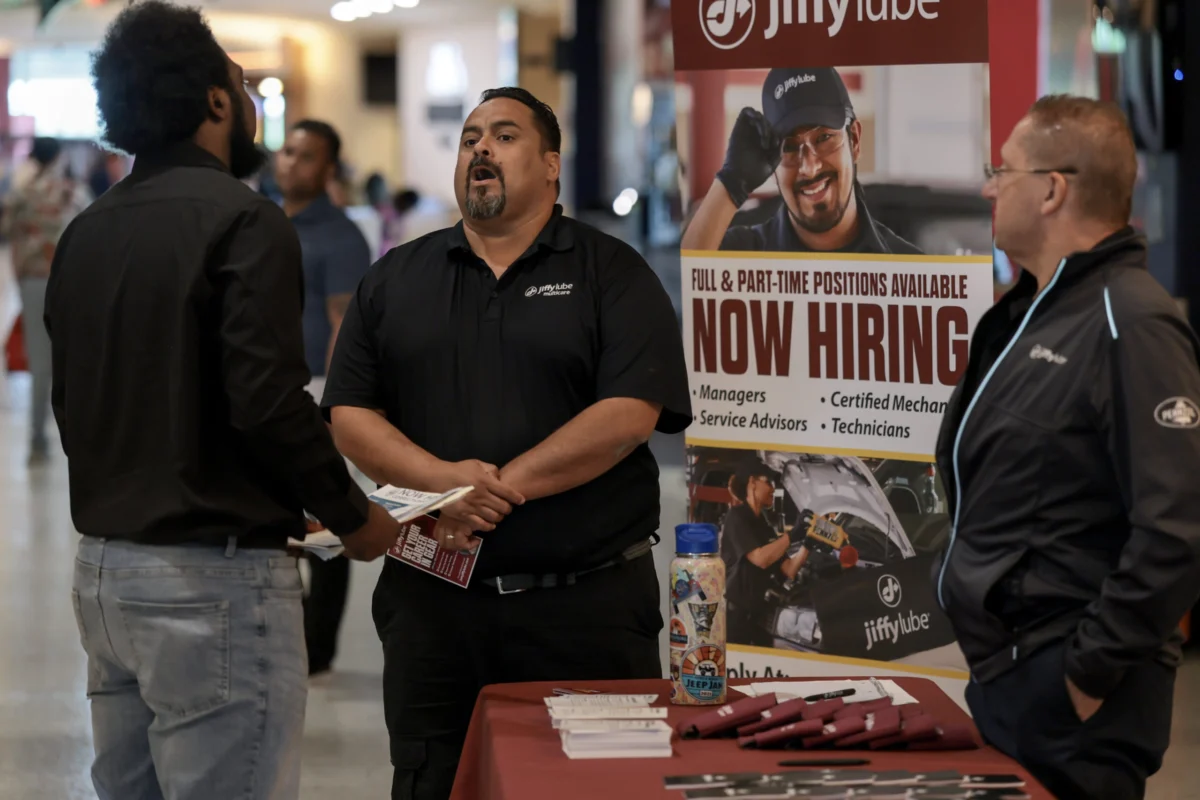
Adding a tangible dimension to the ongoing labor market discussions, the Mega JobNewsUSA South Florida Job Fair, held on September 25, 2026, at the Amerant Bank Arena in Sunrise, Florida, served as a microcosm of the current employment landscape. Victor Moreno, representing Jiffy Lube, was observed engaging with job seekers, highlighting the continued, albeit perhaps more competitive, search for talent across various sectors. Such events underscore the dynamic interplay between macroeconomic data and the real-world experiences of job seekers and employers navigating a shifting economic environment.
The Federal Reserve’s Evolving Stance and Market Reaction
The week leading up to the September jobs report was punctuated by significant commentary from Federal Reserve officials, signaling a discernible shift in the central bank’s near-term policy outlook. Federal Reserve Vice Chairman Philip Jefferson, speaking on Thursday, articulated a view that "a broad range of data indicates that conditions have stabilized" within the labor market. He noted the encouraging broadening of payroll gains across many sectors in recent months, despite some volatility in job creation, and pointed to consistently low layoff rates and a slight upward trend in job openings as positive indicators.
This sentiment of stability was echoed and amplified by New York Fed President John Williams earlier in the week. Williams’ remarks, specifically that "there is no need for urgency" regarding further rate adjustments, significantly recalibrated market expectations. His statement, delivered in the context of the Fed’s assessment of its twin goals, underscored that the employment side of the mandate continues to demonstrate solidity, having even "strengthened a bit on the margin." This dovish turn from a prominent Fed voice came shortly after the central bank’s September meeting, which saw a quarter percentage point rate hike—a decision that had initially led many analysts to anticipate another increase by year-end.

The financial markets responded swiftly to these pronouncements. The probability of an additional rate hike at the upcoming October 27-28 Federal Open Market Committee (FOMC) meeting sharply diminished, with traders and investors now largely anticipating such a move to be considerably more likely in December. This recalibration reflects a growing belief that the Fed, while acknowledging ongoing inflationary pressures, may opt for a more patient, data-dependent approach, allowing previous tightening measures to fully propagate through the economy before implementing further adjustments. The implied pause in October, therefore, becomes a critical indicator of the Fed’s assessment of economic momentum and its confidence in achieving its inflation target without unduly stifling employment growth.
Dissecting the Labor Market Data: A Picture of Stability and Nuance
The "slow but steady" narrative increasingly defines the U.S. labor market in 2026. While the headline nonfarm payrolls figure is expected to show moderation, the underlying trends suggest a market that has largely stabilized rather than contracted. The average monthly payroll growth for 2026 has hovered around 80,000, a figure considerably lower than the blistering pace observed in the immediate post-pandemic recovery years but still indicative of expansion. This average, however, masks significant month-to-month volatility, illustrating the erratic nature of the current hiring environment. For instance, the labor market experienced a perplexing loss of 156,000 jobs in February, only to rebound sharply with a gain of 214,000 the very next month, followed by a mix of hits and misses throughout the year. Such fluctuations underscore the challenges faced by economists and policymakers in discerning clear, consistent trends.
Beyond job creation, wage growth—a key component in the inflation debate—has shown signs of moderation. Average hourly earnings are projected to register a 3.1% year-over-year increase for September. This represents a cooling from the approximately 4% growth rates observed at the beginning of the year. Federal Reserve officials have repeatedly emphasized that current wage trends do not appear to be a primary driver of inflation, noting a distinct lack of evidence for a self-reinforcing "wage-price spiral." This distinction is crucial for calibrating monetary policy, as it suggests that broad-based inflationary pressures may stem more from supply-side constraints or elevated demand rather than spiraling labor costs.
Complementing these top-line figures, other labor market indicators paint a nuanced picture of resilience. Layoffs, often a harbinger of economic distress, have remained remarkably low. The most recent data on first-time claims for unemployment insurance showed a slight dip to 197,000 last week, maintaining a level consistent with a tight labor market. Further corroborating this, the job placement firm Challenger, Gray & Christmas reported a significant decline in layoffs for September, down 18% from August and a notable 20% compared to the same period a year ago. This suggests that while hiring may be less aggressive, employers are generally retaining their existing workforce. Conversely, while job openings have seen some fluctuations, Vice Chairman Jefferson noted a slight upward movement on net, indicating that demand for labor, while perhaps uneven, is still present.
Beneath the Surface: Worker Sentiment and Emerging Anxieties
Despite the official data points signaling a stable labor market, a deeper dive into worker sentiment reveals a more complex reality. The most recent Glassdoor survey, a bellwether for employee confidence, indicated a record low in September—the third such instance within the year. Daniel Zhao, chief economist at Glassdoor, attributed this downturn to mounting anxieties among workers, citing concerns over job security, broader economic uncertainty, and the relentless pressure of inflation. A new and increasingly potent factor contributing to this unease is the fear surrounding the rapid advancement and potential displacement by artificial intelligence (AI). The prospect of automation reshaping industries and rendering certain roles obsolete is a growing source of trepidation for many.

This dichotomy between macro-level stability and micro-level apprehension was captured by Dan North, senior economist at Allianz Trade. North characterized the current environment as a "low-hire, low-fire job market," where while layoffs remain subdued, the process of securing new employment has become noticeably more challenging. "Job openings are going down, hiring’s kind of creeping down," North observed, adding that "it’s very hard for people to get a new job." He emphasized the historical significance of the consistently low unemployment rate, suggesting that "stable" is indeed a fitting descriptor for the current labor market, even as individuals face increased hurdles in career transitions. The scenes at job fairs, like the one in Sunrise, Florida, where individuals actively seek opportunities amidst a landscape described by economists as "stable" yet "hard to get a new job," vividly illustrate this paradox.
Inflation’s Persistent Shadow and Broader Implications
Central to the Federal Reserve’s current strategy is the argument that while the labor market remains robust, the primary policy focus must shift to controlling inflation without prematurely stifling economic growth. The stable, if unspectacular, labor picture provides the Fed with room to maneuver, allowing them to be less urgent about further rate hikes. This approach hinges on the belief that the cumulative impact of previous rate increases, which began in early 2025 and continued throughout 2026, is still working its way through the economy. The Fed’s target for inflation, typically around 2% as measured by the Personal Consumption Expenditures (PCE) price index, remains above desired levels, necessitating continued vigilance.
The implications of the September jobs report and the Fed’s evolving stance are far-reaching. For consumers, a stable labor market, coupled with moderating wage growth, could offer some relief if inflation also begins to recede more meaningfully. However, persistent anxieties about job security and the cost of living could temper consumer spending. For businesses, the "low-hire, low-fire" environment suggests a cautious approach to expansion, prioritizing efficiency and retention over aggressive hiring. The reduced odds of an October rate hike are generally positive for equity markets, as lower interest rates tend to support corporate valuations. Conversely, the bond market might see some fluctuations, with Treasury yields reacting to any surprises in the jobs data or further shifts in Fed commentary.
Looking ahead, the debate between a "soft landing"—where inflation cools without a significant economic downturn—and the risk of a recession continues. The Fed’s delicate balancing act, navigating labor market strength against inflationary pressures, will be crucial in determining the economy’s trajectory. The ongoing discussion about artificial intelligence also looms large, posing fundamental questions about the future of work, skill requirements, and potential structural changes to the labor market that could have long-term implications for employment, wages, and economic growth. The September nonfarm payrolls report, therefore, is not merely a snapshot of the past month but a vital piece of the complex puzzle informing the nation’s economic future.