Gilang Muhammad
The United States economy is bracing for another month of subdued job creation, with economists forecasting a meager gain in nonfarm payrolls for October. This comes as employers exhibit a reluctance to expand their workforces significantly, yet simultaneously show little inclination to cut existing staff. This paradoxical stability is occurring against a backdrop of a shrinking national labor force and an increasingly entrenched problem of long-term unemployment, painting a complex picture of the nation’s economic health.
Anticipating October’s Figures: A Modest Outlook
As the Bureau of Labor Statistics (BLS) prepares to release its highly anticipated October nonfarm payrolls report on Friday at 8:30 a.m. ET, the consensus among economists surveyed by Dow Jones points to a gain of just 59,000 jobs. This modest projection represents only a slight uptick from the 29,000 jobs reported in September and would further entrench a pattern of sparse growth that has characterized the labor market for nearly two years. Such figures, once considered a significant red flag for economic vitality, are now being viewed through a different lens, largely due to profound demographic and structural shifts.
Crucially, despite the expected sluggish job creation, the unemployment rate is projected to hold steady at a very low 4.2%. This seemingly contradictory outcome is the product of a labor market where a stagnant, and in some aspects, contracting labor force reduces the necessity for massive job increases to maintain a stable jobless level. The implication is that the economy requires fewer new jobs each month to keep pace with the available workforce, redefining traditional benchmarks of labor market strength.
Demographic Headwinds: The Root of the Structural Shift
Economists like Nicole Bachaud, a labor economist at the jobs site ZipRecruiter, emphasize that the long-term outlook for job creation is fundamentally altered. "Long-term, we’re not going to need as many jobs added to the economy to have stable employment because we have fewer people who are available to work," Bachaud explained. This shift is primarily driven by three interconnected demographic forces: an aging workforce, decades of low birth rates, and significantly reduced immigration.
The aging of the vast Baby Boomer generation continues to push a substantial number of experienced workers into retirement, creating a vacuum in various sectors. Simultaneously, the sustained period of low birth rates over the past few decades means that there are simply fewer young adults entering the workforce to replace those retiring. This demographic deficit creates a pipeline problem for future labor supply. Compounding these domestic trends, a significant reduction in immigration has further curtailed the influx of prime-age workers who have historically played a crucial role in replenishing the labor force and filling critical skill gaps. These combined factors signify a structural recalibration of the labor supply, fundamentally altering the dynamics of hiring and employment.
A Closer Look at Recent Trends (January 2025 – September 2026)
The period spanning from January 2025 through September 2026 offers compelling evidence of this new normal. During these 21 months, average payroll growth has been a remarkably low 35,000 jobs per month. This extended stretch saw only a single month where job gains topped the 200,000 mark – a level once considered the minimum for healthy economic expansion – and, strikingly, seven months that recorded outright job losses.
Yet, amidst this pronounced slowdown in hiring, the unemployment rate has remained remarkably resilient, inching up by a mere 0.2 percentage points over the entire period. This stability is largely attributable to a shrinking labor pool. The national labor force has contracted by a substantial 434,000 individuals since January 2025, and by just shy of a million people since September 2025. This significant reduction in the number of people either working or actively seeking employment has had a direct impact on the labor force participation rate, which has pulled back sharply to 61.8%, representing a 0.8 percentage point slide. This decline signifies a smaller proportion of the working-age population engaged in the labor market, altering the equilibrium between job supply and demand.
Contrasting Indicators: Strength Amidst Weakness
While headline job growth has been muted, other facets of the labor market reveal pockets of strength, creating a nuanced and often contradictory narrative. The level of layoffs, for instance, has remained exceptionally low. Initial jobless claims, a key indicator of firings, recently slid to 189,000 last week, marking the lowest level since July and hovering around levels not seen since 1969. This suggests that employers, while cautious about adding new staff, are highly motivated to retain their current employees, likely due to the ongoing challenges in finding qualified talent and the costs associated with training new hires.

Further bolstering signs of underlying demand, job openings unexpectedly picked up significantly in September, increasing by 333,000 positions. This rise indicates that businesses still have unfilled roles, even if they are slow to fill them. Moreover, the number of workers voluntarily quitting their jobs – often considered a proxy for worker confidence in their ability to find new employment – reached 3.36 million in September, its highest level in a year and a half. This suggests that a segment of the workforce remains confident enough to seek better opportunities, although the overall slowdown in "movement" as noted by economists like Bachaud indicates that finding those new opportunities might be more challenging for those currently out of work.
However, a persistent area of concern remains long-term unemployment. The total number of workers who have been out of a job for more than 25 weeks has increased by a troubling 495,000 since January 2025. Correspondingly, the average duration of unemployment has risen to 24.8 weeks, an increase of 2.8 weeks, according to BLS data through September. This segment of the unemployed population faces unique challenges, often encountering skill decay, discrimination, and a diminished professional network, making their reintegration into the workforce particularly difficult in a market that prioritizes retention over new hiring.
The Federal Reserve’s Stance and Economic Policy Implications
Federal Reserve officials have generally characterized the labor market as "solid," a perspective that takes into account the low unemployment rate and strong retention figures. However, the emerging structural shifts and mixed signals present a complex challenge for monetary policy. The traditional metrics used to gauge labor market tightness and inflationary pressures are becoming less straightforward to interpret.
Economists are increasingly grappling with how to evaluate the true health of the labor market in this new climate. As Bachaud points out, the focus may need to shift beyond mere job numbers. "Do we have an economy where we have a lot of productivity but not as many jobs? Do we start focusing on things like wage growth? Is that more of a signal, especially for lower-wage workers?" she queried. This indicates a potential re-evaluation of economic indicators, emphasizing the quality of jobs and the distribution of wage gains rather than just the sheer volume of new positions. The expectation is that the economy is unlikely to return to a period of consistently adding 200,000-plus jobs per month, necessitating a more nuanced approach to policy formulation.
Beyond the Numbers: The Human Element and Targeted Hiring
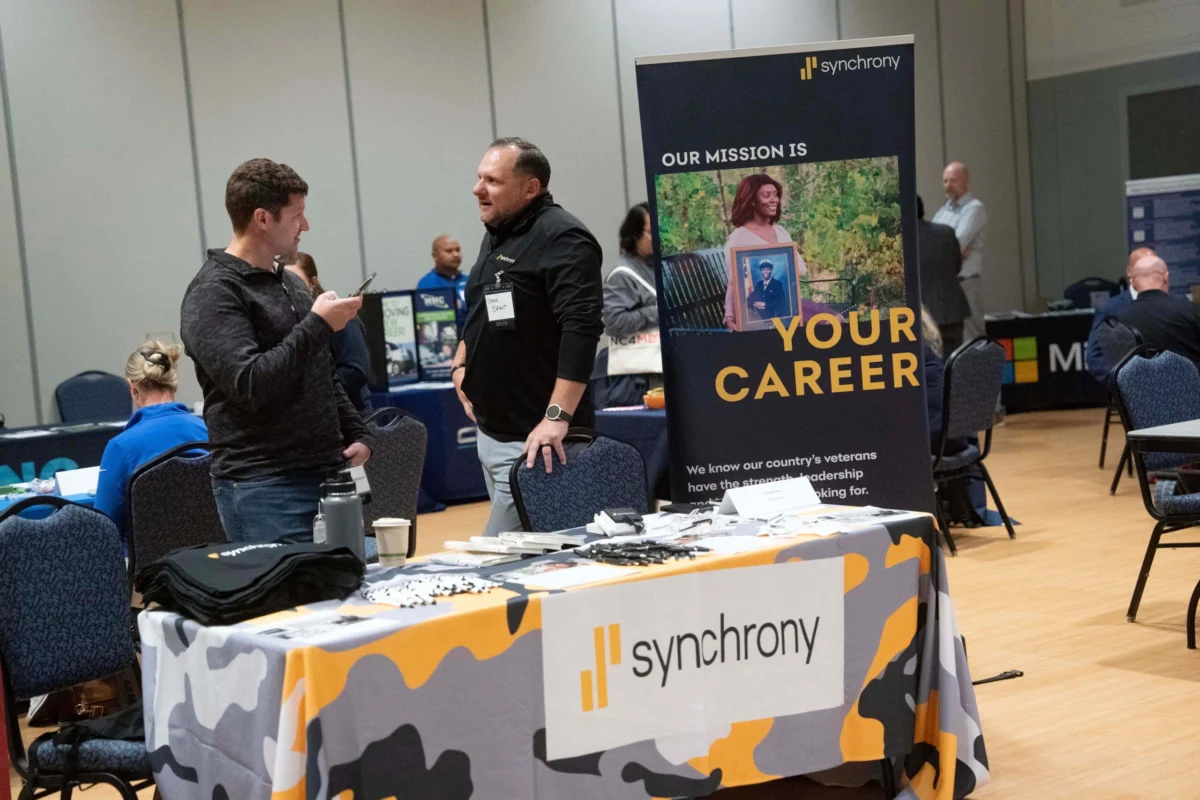
Against this broader economic backdrop, the challenges and opportunities in specific hiring initiatives become particularly poignant. A tangible example is the Synchrony booth at the NC4ME hiring event for military veterans, which took place in Wilmington, North Carolina, on Wednesday, October 28, 2026. NC4ME (North Carolina for Military Employment) is a public-private partnership dedicated to connecting North Carolina’s military talent with businesses looking for an exceptional workforce. Events like these highlight how companies are actively seeking to tap into specific talent pools to address their hiring needs, even in a market characterized by overall slower growth.
For companies like Synchrony, a financial services company, veterans represent a valuable talent source, often bringing a diverse set of skills, leadership qualities, and a strong work ethic honed through military service. In a competitive environment where employers are reluctant to let go of existing staff and the overall labor pool is shrinking, targeted recruiting efforts become even more critical. Such initiatives are vital not only for the companies filling their ranks but also for the individuals seeking employment.
As ZipRecruiter’s Bachaud summarized, "If you have a job, you’re fine, right? There’s not a lot of movement happening, but at least you’re employed." This sentiment underscores the relative security for those currently employed. However, for individuals who are out of work, especially the long-term unemployed, the situation is far more precarious. "For people who are out of work because of the slowdown in turnover, people aren’t vacating their jobs, employers aren’t expanding and adding new jobs. That makes it very difficult to kind of break back in." This observation highlights the increased competition for available roles and the vital role that specialized programs like NC4ME play in helping specific populations bridge the gap into stable employment.
The Road Ahead: Adapting to a New Economic Reality
The U.S. labor market is undergoing a fundamental transformation, moving away from the rapid expansion phases seen in previous decades. The current environment, characterized by structurally lower job growth, persistent low unemployment, and a shrinking labor force, demands a recalibration of expectations and policy. For businesses, this means a greater emphasis on employee retention, productivity enhancements through technology and training, and strategic recruitment from diverse talent pools. For workers, it underscores the importance of continuous skill development and adaptability in navigating a market that values specialized expertise and experience.
As the BLS prepares to release the latest figures, the focus will not solely be on the headline number of jobs created. Instead, economists, policymakers, and businesses will delve deeper into the nuanced indicators of wage growth, productivity, labor force participation, and the trajectory of long-term unemployment to truly assess the health and future direction of the American workforce. The era of robust, easily achieved job growth may be receding, replaced by a more complex, structurally constrained, yet resilient labor market that requires new metrics and new strategies to thrive.