Gilang Muhammad
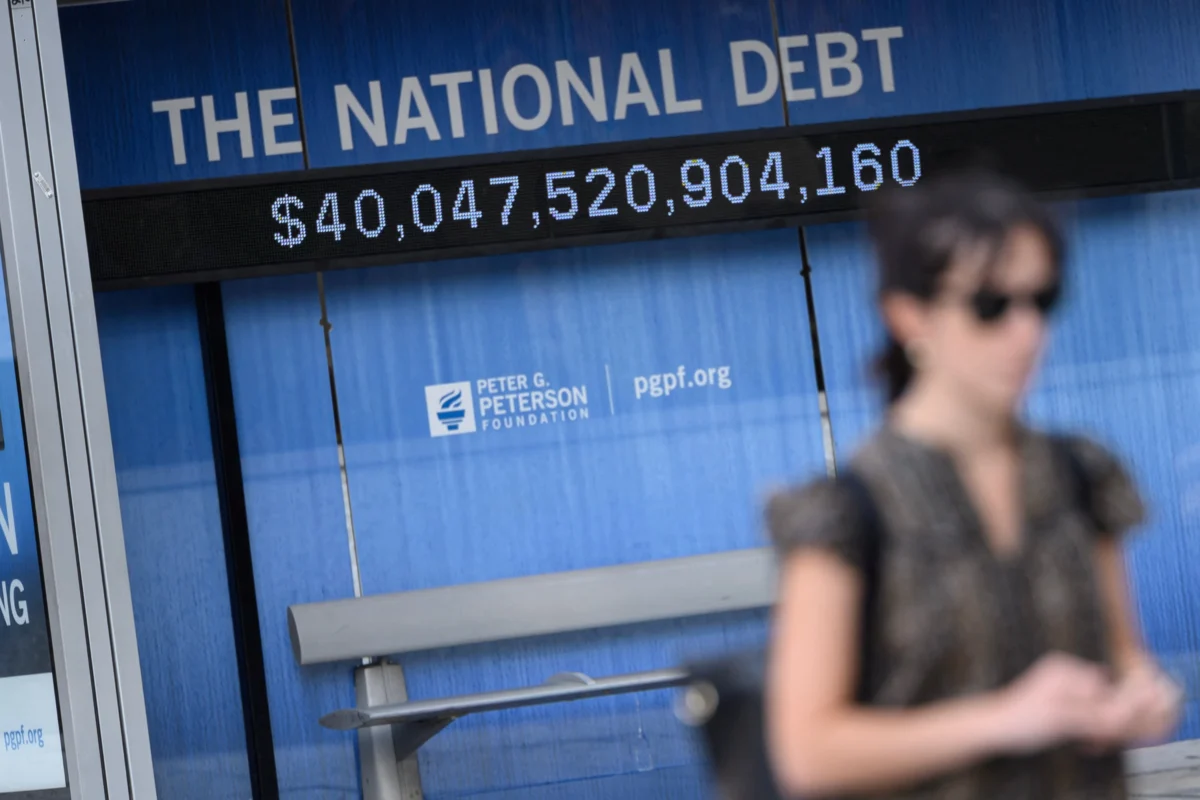
The United States concluded its 2026 fiscal year with a staggering budget deficit of nearly $2 trillion, specifically $1.992 trillion, a stark indicator of the nation’s escalating financial pressures. This figure represents a significant 12% increase from the $1.775 trillion deficit recorded in the prior fiscal year, as reported by the Treasury Department on Friday. This marks the third-highest annual deficit in U.S. history, trailing only the extraordinary spending years of 2020 and 2021 when the federal government deployed trillions in financial stimulus to combat the economic fallout of the Covid-19 pandemic. Notably, the 2026 fiscal year witnessed record sums for both government receipts and outlays, a Treasury Department official confirmed, highlighting an unprecedented scale of federal financial activity.
With this latest announcement, the U.S. officially extends its streak to 25 consecutive fiscal years operating in deficit territory. The last time the federal government achieved a budget surplus, meaning its revenues surpassed its expenditures, was in 2001. This quarter-century trend underscores a persistent structural imbalance in federal finances, raising profound questions about the nation’s long-term economic health. The accelerating accumulation of national debt has already begun to ripple through financial markets, fueling anxiety among bond traders. This apprehension manifested last week as the yields on both the benchmark 10-year and 30-year U.S. Treasury bonds soared to 24-year highs, signaling investors’ demand for higher compensation to hold U.S. government debt amid rising fiscal uncertainty.
A Quarter Century of Deficits: A Troubling Trajectory
The U.S. fiscal landscape has been characterized by deficits for over two decades, a trend that began shortly after the brief surplus period at the turn of the millennium. The year 2001 marked the culmination of a period of fiscal discipline and economic prosperity driven by the dot-com boom, which temporarily bolstered federal revenues. However, the subsequent years saw a dramatic shift. The September 11th terrorist attacks, followed by military engagements in Afghanistan and Iraq, initiated a period of increased defense spending. This was compounded by significant tax cuts enacted in the early 2000s, which, while intended to stimulate the economy, also reduced federal revenue streams.
The global financial crisis of 2008-2009 further exacerbated the deficit problem. In response to the severe economic downturn, the government implemented massive stimulus packages and bailouts, pushing deficits to then-unprecedented levels. By 2010, the annual deficit had peaked at over $1.4 trillion, a figure that would eventually be dwarfed by the COVID-19 era. Throughout the 2010s, while deficits somewhat receded from their crisis-era highs, they never returned to balance. Persistent structural issues, including rising healthcare costs and an aging population, continued to exert upward pressure on spending, while various tax policy changes influenced revenue collection.
The COVID-19 pandemic introduced an entirely new scale of fiscal intervention. In 2020 and 2021, the federal government deployed trillions in emergency aid, unemployment benefits, and business support programs. These measures, while crucial for mitigating economic collapse, pushed annual deficits to over $3 trillion, creating the two largest deficits in U.S. history. The 2026 deficit, at nearly $2 trillion, while lower than the pandemic peaks, signals a worrying return to elevated levels even without the immediate exigencies of a global health crisis. This trajectory highlights a structural problem where federal spending consistently outpaces revenue, independent of acute emergencies, reflecting a deeply ingrained fiscal imbalance. The national debt, which stood at around $5.7 trillion in 2001, has now surged past the $40 trillion mark, more than doubling in just the last decade, painting a stark picture of intergenerational fiscal burden.
The Anatomy of the 2026 Deficit: Spending and Revenue Dynamics
The substantial deficit in fiscal year 2026 is a result of complex interplay between record-high government outlays and significant, though ultimately insufficient, revenue generation. A closer examination of the figures reveals the primary drivers behind the nation’s growing financial imbalance.
Record Outlays: The Dominance of Entitlement Programs and Interest Payments
Federal spending in FY2026 reached unprecedented levels, driven primarily by major entitlement programs and a rapidly expanding bill for servicing the national debt.
- Social Security: This program constituted the largest share of government spending, totaling nearly $1.7 trillion for the full fiscal year. This represents a modest increase from the roughly $1.6 trillion spent in 2025. The rising costs of Social Security are largely attributable to the increasing number of retirees and beneficiaries, a demographic trend that will continue to strain the system as the baby boomer generation fully enters retirement.
- Medicare: The government-run healthcare program was the second-largest expenditure, costing almost $1.1 trillion in FY2026, up from slightly under $1 trillion in fiscal 2025. Medicare’s escalating costs are a reflection of both an aging population and the relentless increase in healthcare expenditures, including prescription drugs, medical technology, and provider services. These two programs combined account for a substantial portion of the federal budget, and their growth is largely mandated by existing law, making them challenging to control without significant legislative reform.
- Net Interest: Perhaps the most alarming component of the 2026 budget was the cost of net interest on the national debt, which topped $1 trillion for the fiscal year. This figure soared from $970 billion in fiscal 2025, demonstrating the dramatic impact of both the expanding debt principal and rising interest rates. As the Federal Reserve has raised rates to combat inflation, the cost of borrowing for the U.S. government has surged. This expenditure is non-discretionary, meaning it must be paid, and it diverts an increasingly large share of federal revenue that could otherwise be allocated to other critical areas like infrastructure, education, defense, or scientific research. This phenomenon, often referred to as "crowding out," limits the government’s fiscal flexibility and long-term investment capacity. In FY2026, the U.S. shelled out more than $1.3 trillion in gross interest on the national public debt, emphasizing the magnitude of this growing burden.
Revenue Landscape: Strong Individual Taxes Offset by Corporate Cuts and Tariff Refunds
Despite the record outlays, federal revenues also hit a record high in FY2026, but not enough to bridge the gap.
- Individual Income Taxes: These remained the largest source of federal revenue, bringing in more than $2.8 trillion. This figure represents a healthy increase of approximately 7% year-over-year, likely reflecting a strong labor market and wage growth.
- Corporate Income Tax: In contrast, corporate income tax receipts provided $381 billion during the 2026 fiscal year, a decrease of about $70 billion from fiscal 2025. This reduction stemmed directly from the tax cuts included in the "One Big Beautiful Bill act" passed by Congress last year. This legislation, championed by the administration, aimed to stimulate economic growth by reducing the corporate tax burden, but its immediate effect was a noticeable decline in corporate tax contributions to federal coffers. Economists and policymakers remain divided on the long-term economic benefits versus the immediate revenue loss associated with such cuts.
- Tariffs and Trade Policy: A Contentious Revenue Stream: The administration’s aggressive trade policy, particularly its reliance on tariffs, aimed to bolster federal revenue while protecting domestic industries. The Treasury did report a record high for gross customs duties in the 2026 fiscal year, indicating the significant volume of tariffs collected. However, the total net revenue from customs took a substantial hit due to refunds required following a Supreme Court ruling earlier in 2026. This ruling found many of the tariffs instituted by the Trump administration to be unconstitutional, necessitating the return of billions of dollars to affected retailers and importers. This judicial intervention underscored the legal complexities and potential revenue instability associated with using tariffs as a primary fiscal tool. The monthly deficit for September 2026, coming in at $27 billion, further highlighted this volatility, marking a significant reversal from the prior year’s September surplus of $198 billion.
Official Responses and Economic Perspectives
The alarming deficit figures for FY2026 have elicited a range of responses from government officials, economists, and other stakeholders, reflecting diverse views on the causes and potential solutions to the nation’s fiscal challenges.
Treasury Secretary Bessent’s Growth Strategy:
Treasury Secretary Scott Bessent, speaking to CNBC in August, articulated the administration’s primary strategy for addressing the burgeoning debt: "grow our way out of" it. Bessent emphasized, "Our message to our allies, our trading partners, is that global growth is the way to take care of this mountain of debt." This perspective suggests a belief that robust economic expansion, both domestically and internationally, can generate sufficient tax revenue to outpace the growth of the debt, effectively shrinking the debt-to-GDP ratio over time. However, many economists caution that relying solely on growth, while desirable, may be insufficient given the current scale of the debt and the structural nature of the deficit. They point to historical precedents where even periods of strong growth struggled to significantly reduce debt burdens without accompanying fiscal adjustments. The feasibility of this strategy hinges on sustained, exceptionally high growth rates, which are challenging to achieve consistently.
President Trump’s Fiscal Vision and Tariff Policy:
President Donald Trump has consistently advocated for broad and steep tariffs as a means to drive up revenue and shrink the government’s debt. His administration pushed forward with its strategy of increasing levies on trading partners, arguing that these duties would not only protect American industries but also provide a significant income stream for the federal government. This approach, however, faced considerable headwinds. The Supreme Court ruling in February 2026, which declared many of Trump’s instituted tariffs unconstitutional, dealt a blow to this revenue strategy. The subsequent requirement for billions of dollars in refunds to retailers demonstrated the legal and economic vulnerabilities of relying heavily on tariffs for federal funding. Critics of the tariff policy, including many business groups and economists, have argued that such levies ultimately act as a tax on American consumers and businesses, raising import costs and potentially leading to retaliatory tariffs from other countries, thus hindering global trade and economic growth.
Congressional Reactions (Inferred):
In Congress, the deficit figures are likely to intensify partisan debates. Lawmakers from the ruling party (assuming a Republican majority aligned with President Trump) would likely emphasize the need for continued tax cuts to stimulate growth, echoing Secretary Bessent’s sentiment. They might also call for spending reductions in non-essential areas, while defending allocations to defense and other priorities. Conversely, the opposition party (likely Democrats) would almost certainly seize upon the rising deficit to criticize the "One Big Beautiful Bill act" tax cuts, arguing that they disproportionately benefit corporations and the wealthy while exacerbating the national debt. They would likely advocate for increased revenue through higher taxes on corporations and high-income earners, coupled with calls to protect social safety net programs like Social Security and Medicare from cuts, instead proposing reforms to ensure their long-term solvency.
Economists and Fiscal Watchdogs (Inferred):
The release of the FY2026 deficit numbers would undoubtedly trigger widespread alarm among fiscal watchdogs and a significant segment of the economics community. Organizations like the Committee for a Responsible Federal Budget and the Peter G. Peterson Foundation would likely issue stern warnings about the nation’s unsustainable fiscal path. Economists across the spectrum would highlight the dangers of consistently high deficits: increased interest payments diverting funds from productive investments, potential for higher inflation, and the risk of a fiscal crisis if investor confidence wanes. While some economists might argue that deficits are manageable during periods of low interest rates or economic downturns, the combination of a near-$2 trillion deficit and rising interest rates presents a more immediate and pressing concern. Many would call for a comprehensive, bipartisan plan to address the structural imbalances in federal spending and revenue.
Credit Rating Agencies (Inferred):
The major credit rating agencies—Standard & Poor’s (S&P), Moody’s, and Fitch Ratings—would be closely scrutinizing these figures. Continued high deficits and a rapidly expanding national debt could prompt these agencies to issue warnings, revise their outlooks to "negative," or even consider downgrading the U.S. sovereign credit rating. A downgrade, while not unprecedented (S&P downgraded the U.S. in 2011), would send a powerful negative signal to global financial markets, potentially increasing borrowing costs for the U.S. government and, by extension, for businesses and consumers across the country. Such actions would underscore the international community’s concerns about the long-term fiscal stability of the world’s largest economy.
Broader Economic and Societal Implications
The U.S.’s persistent and expanding budget deficits carry profound implications, extending far beyond the immediate financial markets to impact economic stability, future generations, and the nation’s global standing.
Impact on Financial Markets:
The immediate reaction in bond markets, with 10-year and 30-year Treasury yields reaching 24-year highs, is a clear signal of investor apprehension. Higher yields mean increased borrowing costs for the government, further exacerbating the interest payment burden. This also translates to higher interest rates for consumers and businesses, affecting mortgages, car loans, and corporate investments, potentially dampening overall economic activity. A sustained period of high deficits can erode investor confidence in the U.S. dollar, potentially weakening its status as the world’s primary reserve currency and leading to greater volatility in international financial markets.
Long-Term Fiscal Sustainability and Intergenerational Burden:
The continuous accumulation of debt without a clear path to repayment raises serious questions about long-term fiscal sustainability. Each dollar added to the national debt represents a future tax obligation or a reduction in future government services. This creates an intergenerational burden, where today’s consumption and spending are financed by future generations. Economists warn that unchecked debt growth can stifle future economic potential by diverting resources from productive investments, increasing the risk of higher inflation, and limiting the government’s capacity to respond to unforeseen crises. The long-term solvency of critical social programs like Social Security and Medicare, already under demographic strain, becomes even more precarious amidst a backdrop of rising national debt. Without reform, these programs face funding shortfalls that could necessitate benefit cuts or significant tax increases in the future.
Policy Choices and Constraints:
A ballooning national debt severely constrains the government’s fiscal space, limiting its ability to respond effectively to future economic downturns, national security threats, or other emergencies. During the COVID-19 pandemic, the U.S. had significant fiscal capacity to deploy trillions in aid. However, with the national debt now exceeding $40 trillion and annual deficits nearing $2 trillion, the ability to mount similar large-scale responses to future crises is diminished. This could force difficult choices between essential public services, defense spending, and critical investments in areas like infrastructure, education, and clean energy, potentially hindering long-term national competitiveness and well-being.
Global Standing and Geopolitical Influence:
The U.S.’s economic strength and stability are cornerstones of its global leadership and geopolitical influence. A deteriorating fiscal outlook can undermine international confidence in the U.S. economy, potentially weakening its diplomatic leverage and its ability to project power globally. Countries that hold significant amounts of U.S. debt, such as China and Japan, could use their holdings as leverage, while allies might question the reliability of a partner facing internal fiscal instability. Maintaining a strong and stable economy is crucial for the U.S. to effectively address global challenges and uphold its position on the international stage.
The Path Forward: Navigating Fiscal Headwinds
The near $2 trillion deficit in fiscal year 2026 serves as an urgent wake-up call, underscoring the critical need for a comprehensive and bipartisan approach to address the nation’s fiscal challenges. Relying solely on economic growth, while desirable, is unlikely to be sufficient given the magnitude of the debt and the structural nature of federal spending.
A sustainable fiscal strategy would require a combination of measures. On the spending side, this could involve reforms to entitlement programs, such as adjusting eligibility ages, modifying benefit formulas, or exploring new revenue streams dedicated to these programs. Discretionary spending, while a smaller component of the budget, could also be scrutinized for efficiencies. On the revenue side, discussions could encompass adjustments to the tax code, including revisiting corporate and individual income tax rates, broadening the tax base, or exploring new forms of taxation.
The political will to enact such measures has historically been difficult to muster, often falling victim to partisan gridlock and the short-term focus of election cycles. However, the escalating costs of inaction, particularly the soaring interest payments and the growing intergenerational burden, make the need for a long-term solution more pressing than ever. A credible, transparent, and bipartisan fiscal plan would not only reassure financial markets but also lay a stronger foundation for sustained economic growth, ensure the solvency of vital social programs, and preserve the U.S.’s economic leadership for future generations.
In conclusion, the fiscal year 2026 deficit is more than just a number; it is a critical indicator of deep-seated financial challenges that demand immediate attention and courageous political leadership. The consequences of continuing on the current trajectory are profound, threatening everything from everyday economic stability to America’s long-term global standing. The time for comprehensive fiscal reform is now, before the options narrow and the costs become insurmountable.