Farhan Pambudi
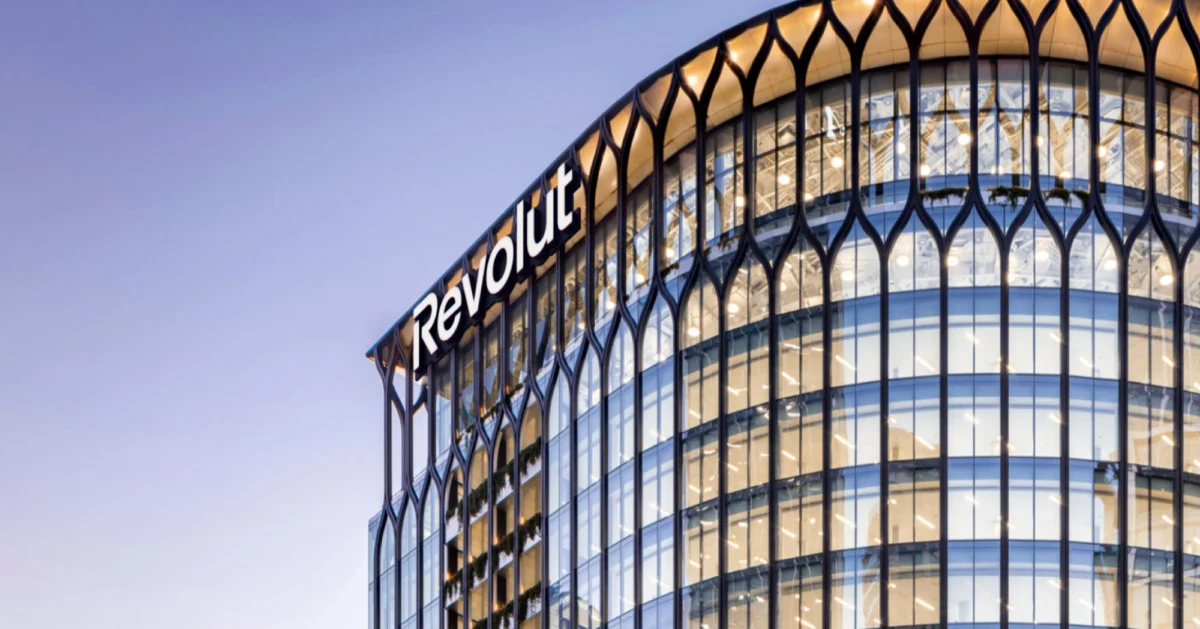
The London-based fintech powerhouse Revolut has solidified its position as one of the most valuable private financial institutions in the world, achieving a valuation of $115 billion following a successful secondary share sale. This latest valuation represents a staggering 53% increase from the price tag established during a similar share sale only one year ago, signaling robust investor confidence in the company’s aggressive global expansion and its transition from a digital wallet into a diversified global bank.
The secondary sale was led by a consortium of high-profile investment firms, including Glade Brook Capital Partners, Coatue, Durable Capital Partners, T. Rowe Price Associates, and Baillie Gifford. Notably, the transaction did not involve the issuance of new shares or the infusion of fresh capital into Revolut’s balance sheet. Instead, it served as a liquidity event, allowing long-term employees and early-stage investors to divest a portion of their holdings. While Revolut has declined to specify the total volume of stock traded during this round, the $115 billion benchmark places it in a rare echelon of "decacorns," rivaling the market capitalization of some of the world’s most established traditional banking institutions.
A Decade of Disruption: From Startup to Global Powerhouse
Founded in 2015 by former Credit Suisse trader Nik Storonsky and software developer Vlad Yatsenko, Revolut was initially conceived as a low-cost currency exchange and money-transfer app designed to eliminate the hidden fees associated with international travel. In the decade since its inception, the company has undergone a rapid metamorphosis. Today, it operates as a comprehensive financial services ecosystem, boasting more than 80 million retail customers across more than 40 countries.
Revolut’s growth trajectory has been characterized by a relentless pursuit of banking licenses in major economies. The company has already established significant banking operations across the European Union and, in a landmark year for its regulatory ambitions, launched full banking services in the United Kingdom, Mexico, Australia, and New Zealand in 2024. Furthermore, the firm has successfully secured licenses in key emerging markets, including France, Colombia, and Argentina, creating a geographic footprint that few fintech competitors can match.
The company’s financial performance has kept pace with its user growth. According to internal reports, Revolut achieved a 38% profit margin on revenue of $6 billion in 2025. This profitability marks a significant turning point for the fintech sector, which has historically struggled to prove that high-growth digital platforms can achieve sustainable, high-margin returns.
The Strategic Importance of Revolut Business
While Revolut’s retail division remains its most visible arm, the company’s business banking division has emerged as a critical driver of its valuation and long-term stability. Launched in 2017, Revolut Business was designed to provide small and medium-sized enterprises (SMEs) with the same seamless, borderless financial tools enjoyed by retail users.
James Gibson, Head of Revolut Business and a partner at the firm, recently highlighted the division’s outsized impact on the company’s bottom line. The business segment currently accounts for approximately 20% of Revolut’s gross profit. Operating across Europe, the UK, Singapore, Australia, New Zealand, and the United States, the division processes more than £36 billion (approximately $48.6 billion) in transactions every month.
The U.S. market has proven particularly fertile ground for this division, with monthly transaction volumes exceeding £1 billion ($1.35 billion). In a testament to the platform’s appeal to entrepreneurs, Revolut noted that nearly half of its new business customers in the U.S. are "newly incorporated" companies, suggesting that the platform is becoming the primary financial partner for the next generation of American startups.
Financially, the business division generates more than £950 million (roughly $1.28 billion) in annualized revenue and manages over £18 billion ($24.3 billion) in customer deposits. Looking ahead, Gibson indicated that the company intends to scale this segment further, with plans to expand business banking into Mexico, Brazil, and India. The stated goal is to grow the B2B customer base from its current 800,000 businesses to over one million by 2027.
Targeting the American Market: The 2027 Banking Vision
The most significant catalyst for Revolut’s future growth is its anticipated entry into the United States banking sector. While the company already offers a suite of services in the U.S. via partner banks, it has long sought the autonomy provided by a national banking charter.
Revolut recently received conditional approval from the U.S. Office of the Comptroller of the Currency (OCC) to establish a national bank. This regulatory milestone is the culmination of years of negotiation and compliance auditing. The company expects to officially launch its U.S. bank in the first half of 2027, provided it meets final regulatory requirements.
A full U.S. banking license will allow Revolut to hold its own deposits and expand its lending capabilities, including credit cards and personal loans, which are traditionally higher-margin products. Analysts suggest that a successful U.S. launch could be the deciding factor in whether Revolut can sustain its triple-digit billion-dollar valuation. The U.S. market, while highly competitive and heavily regulated, offers a massive pool of high-value customers that could significantly boost Revolut’s average revenue per user (ARPU).
Expansion in Asia and Latin America
Parallel to its U.S. ambitions, Revolut is making significant inroads into India, the world’s most populous nation. Earlier this year, the company began rolling out financial services to thousands of users in India as part of a phased launch. India represents a unique challenge and opportunity; while the market is dominated by state-backed unified payments interfaces (UPI), the demand for sophisticated cross-border wealth management and business tools is surging among India’s growing middle class and tech-savvy workforce.
In Latin America, the securing of licenses in Mexico, Colombia, and Argentina positions Revolut to capitalize on the region’s high rates of financial exclusion and the increasing adoption of mobile banking. By offering a "super-app" experience—combining banking, stock trading, commodities, and crypto-assets—Revolut aims to displace traditional regional banks that have often been criticized for high fees and poor digital interfaces.
Chronology of Key Milestones
- July 2015: Revolut is founded in London, focusing on multi-currency cards.
- April 2017: Launch of Revolut Business, targeting SMEs.
- December 2018: Secured a specialized European banking license via the Bank of Lithuania.
- July 2021: Reached a $33 billion valuation following an $800 million funding round led by SoftBank and Tiger Global.
- 2024: Secured banking licenses or launched operations in the UK, Mexico, and Australia.
- 2025: Achieved $6 billion in annual revenue with 38% profit margins.
- Late 2025: Secondary share sale values the company at $115 billion.
- 2027 (Projected): Official launch of the Revolut national bank in the United States.
- 2028 (Projected): Earliest window for a potential Initial Public Offering (IPO).
The Path to a 200 Billion Dollar IPO
As Revolut’s valuation continues its meteoric rise, the financial world is closely watching for signs of an Initial Public Offering (IPO). Nik Storonsky has remained pragmatic about the timing, suggesting that while the company is "IPO-ready" in terms of its internal processes and financial reporting, the actual listing will depend heavily on global market conditions.
Speculation regarding the venue for the listing has sparked a "tug-of-war" between London and New York. While the UK government has lobbied heavily for its domestic fintech champion to list on the London Stock Exchange (LSE) to bolster the city’s post-Brexit financial standing, Storonsky has expressed a clear preference for a primary listing in the U.S. or a dual-listing structure. The deeper liquidity pools and higher valuations typically afforded to tech companies on the NASDAQ or NYSE are significant draws.
Reports indicate that Revolut is eyeing a target valuation of up to $200 billion for its eventual IPO. However, the company has signaled that this milestone is unlikely to occur before 2028. This conservative timeline allows Revolut to fully integrate its U.S. and Indian operations, proving the viability of its global banking model before facing the scrutiny of public quarterly earnings reports.
Implications for the Global Fintech Landscape
The $115 billion valuation of Revolut serves as a bellwether for the broader fintech industry. It suggests that the "unbundling" of banking services—where startups took small pieces of the banking value chain—has moved into a "rebundling" phase. Revolut’s success is built on its ability to offer a "one-stop-shop" for all financial needs, a strategy that is increasingly being emulated by competitors like Monzo in the UK and Chime in the U.S.
However, the path forward is not without risks. Regulatory scrutiny remains the primary hurdle for Revolut. The length of time it took to secure a UK banking license—over three years—highlights the cautious approach regulators take toward tech-first firms. As Revolut moves into the U.S., it will face a complex web of state and federal regulations, as well as intense competition from Wall Street giants like JPMorgan Chase and Goldman Sachs, both of which have invested heavily in their own digital offerings.
Despite these challenges, the latest share sale confirms that Revolut has transitioned from a disruptive upstart into a systemic player in the global financial architecture. With a diversified revenue stream, a clear path to U.S. expansion, and a massive retail and business user base, the company is well-positioned to redefine the parameters of 21st-century banking.