Gilang Muhammad
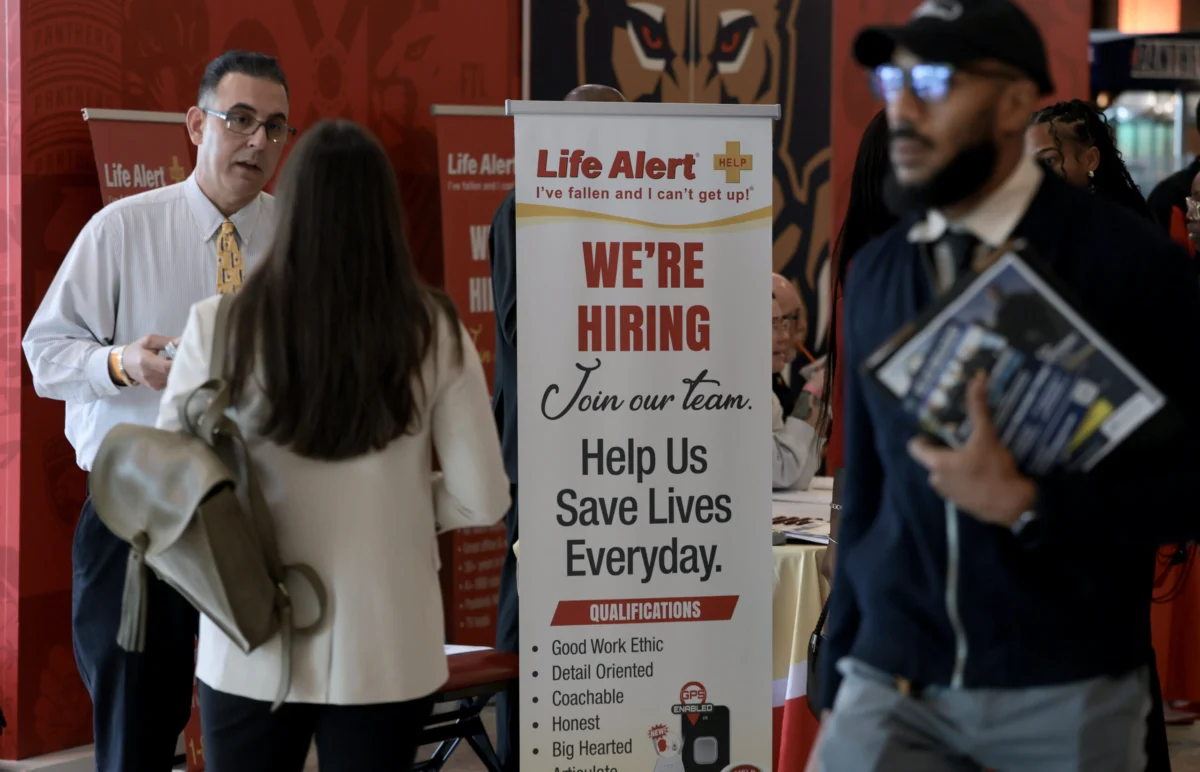
The latest figures released by the Bureau of Labor Statistics on Friday indicated that nonfarm payrolls advanced by a seasonally adjusted 29,000 positions for the month. This tally fell dramatically short of the 84,000 job additions economists surveyed by Dow Jones had anticipated. Concurrently, the unemployment rate experienced an uptick, rising to 4.2% from the prior month, exceeding the 4.1% rate analysts had projected. This unexpected deceleration in job growth marks a notable pivot from the robust hiring trends that characterized much of the post-pandemic recovery, sending ripples of uncertainty through financial markets and prompting a recalibration of future monetary policy expectations.
A Deeper Look at the September Labor Report
Beyond the headline figures, the September jobs report revealed a more entrenched weakness than initially perceived. Compounding the underwhelming performance, August’s job count was revised downward to reflect a gain of 133,000, a reduction from earlier estimates. More strikingly, July’s employment data, initially reported as a gain, was adjusted to a loss, with payrolls shrinking by 10,000. These revisions collectively subtracted 60,000 jobs from previously reported totals for the two preceding months, indicating that the labor market’s momentum was weaker for longer than official statistics had suggested. The cumulative effect of these revisions and the September miss painted a picture of a labor market losing steam at a faster pace than anticipated, raising questions about the underlying health and trajectory of economic growth.
The establishment survey, which provides the widely cited nonfarm payrolls figure, draws data from approximately 122,000 businesses and government agencies, capturing about one-third of total nonfarm employment. Its findings are often seen as a bellwether for business hiring trends. The significant slowdown in this measure immediately triggered concerns, contrasting sharply with recent indicators that had pointed to continued, albeit moderating, strength.
Market Reaction and Federal Reserve Implications
The financial markets responded with alacracy to the soft jobs numbers, interpreting the data as a strong signal that the Federal Reserve would likely maintain its current interest rate stance at its upcoming October meeting. Stock futures surged sharply in the wake of the report’s release, reflecting investor optimism that a less aggressive Fed would alleviate pressure on corporate earnings and valuations. Simultaneously, Treasury yields, which had recently climbed to levels not witnessed since the early part of the century, experienced a notable slump. This decline in yields suggested that bond traders were pricing in a reduced likelihood of further rate hikes in the immediate term, with capital flowing into safer assets.
According to the CME Group’s FedWatch tool, the market-implied odds that the Federal Open Market Committee (FOMC) would hold rates steady at its October 27-28 meeting jumped significantly to 82.8%. This marked a substantial shift from prior expectations, which had seen a non-negligible probability of another quarter-percentage-point hike.
Thomas Simons, chief U.S. economist at Jefferies, encapsulated the prevailing sentiment, stating in a note, "For the Fed, this number should be the nail in the coffin for an October hike." Simons further elaborated on the recent employment trajectory, noting, "The payroll data surged in August, and we had expected the momentum to continue this month, given the historically low prints on jobless claims in recent weeks. However, it now appears that the August number was nothing more than a rebound from very weak hiring in June and July." This assessment underscored the view that the recent strength was ephemeral rather than indicative of sustained economic vigor.
The Fed’s Dual Mandate and Shifting Focus
Federal Reserve officials, tasked with managing the economy under a dual mandate of achieving maximum employment and stable prices, closely scrutinize a broad array of economic indicators. While headline payroll numbers capture immediate attention, policymakers often place particular emphasis on the unemployment rate derived from the household survey, as it offers insights into labor force participation and the broader health of the job market.
The household survey, a separate questionnaire administered to a sample of 60,000 households, presented a somewhat different, and in some aspects, more encouraging picture than the establishment survey. Household employment rose by a robust 406,000 for the month, and the labor force swelled by 485,000. Crucially, the labor force participation rate, which measures the proportion of the civilian noninstitutional population aged 16 years and over who are working or actively searching for a job, increased by 0.2 percentage points to 61.8%. This marked its highest level since May, suggesting that more individuals were entering or re-entering the workforce, potentially easing wage pressures over time.
An alternative measure of unemployment, known as the U-6 rate (or the "underemployment rate"), which includes discouraged workers and those holding part-time jobs for economic reasons, edged down to 7.6%. This marked its lowest level in a significant period, providing a nuanced perspective on labor market slack. While the U-6 rate improved, the increase in the headline unemployment rate (U-3) alongside sluggish payroll growth highlighted a complex and potentially diverging set of signals for policymakers.

The report arrives at a critical juncture for Federal Reserve officials, who have been deliberating the state of the economy and its implications for future interest rate adjustments. Following a series of statements from central bank policymakers in recent days, markets had already begun to recalibrate expectations, leaning towards a pause in October and deferring the next potential rate hike until December. The FOMC had previously raised benchmark rates by a quarter percentage point in September, continuing a tightening cycle initiated to combat persistent inflation.
Policymakers have largely viewed inflation as a more pressing threat to economic stability than the labor market, which had demonstrated remarkable resilience in recent months. The data prior to September had largely painted a picture of a "low-hire, low-fire" economy, characterized by consistently low weekly jobless claims and indicators showing layoffs at their lowest rate in four years. However, the September report challenges this narrative, suggesting that the "low-hire" aspect may be becoming more dominant.
Inflation, despite the Fed’s aggressive tightening, has stubbornly remained well above the central bank’s 2% target. The most recent indicator of the central bank’s preferred gauge, the Personal Consumption Expenditures (PCE) price index, showed core inflation (excluding volatile food and energy components) at a 3% annual rate. This persistent inflationary pressure, combined with signs of a cooling labor market, presents a delicate balancing act for the Fed. While a softer labor market could help temper inflation by reducing wage pressures, a rapid deterioration could trigger broader economic instability.
Wage Growth Slowdown and Consumer Impact
Further underscoring the cooling trend, wage growth continued to show signs of disinflation. Average hourly earnings increased by a mere 0.1% in September, falling short of Wall Street’s expectation of 0.3%. This modest monthly gain brought the 12-month increase to 3%, marking its lowest level since May 2021 and also missing the anticipated 3.1% annual gain. The average work week remained unchanged at 34.6 hours, indicating no additional hours contributing to overall earnings.
The slowdown in wage growth, coupled with elevated inflation, has direct implications for household finances and consumer sentiment. Heather Long, chief economist at Navy Federal Credit Union, articulated these concerns, stating, "Americans are frustrated by the lack of opportunities right now. Wage growth fell to a new 5-year low and is being wiped out entirely by inflation. That stings heading into the holidays." The erosion of purchasing power due to inflation outpacing wage increases can dampen consumer spending, a crucial driver of the U.S. economy, particularly as the holiday shopping season approaches. Despite this, Long described the labor market as "stable" and expressed her belief that the Fed would not be dissuaded from a potential hike in December, suggesting that the underlying strength, despite the September blip, might still be sufficient to warrant further tightening.
Sectoral Performance and Economic Divergences
The monthly job gains were concentrated in a few key sectors. Healthcare led the way, adding 17,000 workers, reflecting ongoing demand for medical services and an aging population. Construction saw a gain of 11,000 jobs, perhaps bolstered by infrastructure projects or residential building despite higher interest rates. Manufacturing, a sector that has faced headwinds from global supply chain issues and trade tensions, managed to add 9,000 positions.
Conversely, several sectors experienced significant declines. Government employment fell by 17,000, which can often be attributed to seasonal adjustments or reductions in specific public sector initiatives. Temporary help services, often seen as a leading indicator of broader hiring trends, saw a decline of 11,000, raising concerns about future business demand. Information services lost 10,000 jobs, a sector facing increasing scrutiny amidst worries over the potential impact of artificial intelligence (AI) on employment. The financial activities sector also registered a drop of 7,000 jobs, possibly reflecting consolidation or cautious hiring in a high-interest-rate environment.
The weak job growth reported in September presents a stark contrast to other signs of strength in the broader economy. On a macro level, economic growth has demonstrated considerable resilience. Earlier in the week, the Commerce Department revised its estimates for both first- and second-quarter gross domestic product (GDP) growth, upward to 2.5% and 2.2%, respectively. Furthermore, the Atlanta Fed’s GDPNow forecast, a real-time estimate of current quarter GDP growth, was tracking an impressive 3.7% for the third quarter. This divergence between robust GDP expansion and decelerating job creation suggests that businesses might be achieving growth through increased productivity, automation, or by working existing employees longer hours, rather than through aggressive hiring. Such a trend could have long-term implications for the relationship between economic output and employment.
Looking Ahead: Navigating Uncertainty
The September jobs report undoubtedly introduces a new layer of complexity to the economic outlook. While one month’s data does not define a trend, the magnitude of the miss, coupled with significant downward revisions to prior months, cannot be easily dismissed. The Federal Reserve will closely monitor upcoming data releases, including inflation figures, consumer spending reports, and subsequent employment reports, to ascertain whether September’s weakness was an anomaly or the harbinger of a more sustained slowdown.
The implications for businesses range from potential shifts in consumer demand to adjustments in investment strategies. For consumers, the combination of slowing wage growth and persistent inflation underscores the ongoing challenges to their financial well-being. The narrative of a remarkably resilient U.S. labor market now faces a significant test, with policymakers and market participants alike carefully weighing the possibility of a more pronounced cooling and its cascading effects across the economy. The path forward for monetary policy, and indeed for the U.S. economy, appears increasingly uncertain as these conflicting signals emerge.