Gilang Muhammad
Initial filings for unemployment insurance have plunged to levels not seen in nearly six decades, underscoring an unexpected resilience in the U.S. labor market. For the week ending October 17, the Labor Department reported that seasonally adjusted initial claims for unemployment insurance slipped to a remarkably low 194,000. This figure positions weekly jobless claims near their lowest point in records stretching back to 1964, challenging conventional economic narratives and providing a crucial counterpoint to recent softer hiring data. The data suggests that despite a discernible slowdown in the pace of new job creation, employers are demonstrating a strong inclination to retain their existing workforce, a phenomenon that could have significant implications for the broader economic outlook and future monetary policy decisions.
Delving Deeper: The Latest Figures and Historical Context
The current figure of 194,000 new claims represents a continuation of a low-fire trend that has characterized the labor market for several months. This number is just marginally above the 189,000 claims reported for the week of July 18, which marked the lowest level recorded since September 1969. To put this into perspective, the late 1960s were characterized by a booming economy, low unemployment, and the early stages of the Great Inflation, a very different economic landscape from the post-pandemic, high-inflation environment of today. Over the past year, weekly claims have averaged 212,000, and the more stable four-week moving average has also trended downwards, now standing at 197,750. This consistent dip below the 200,000 threshold for the four-week average is a key indicator of underlying labor market strength, specifically in terms of job security for currently employed individuals. Economists closely monitor this metric as it smooths out week-to-week volatility, offering a clearer signal of the prevailing trend in layoffs.
The enduring low level of jobless claims is particularly noteworthy given the broader economic backdrop of persistent inflation and higher interest rates. Typically, such an environment would be expected to exert downward pressure on labor demand, potentially leading to increased layoffs as businesses cut costs or scale back expansion plans. However, the current data suggests that employers, having faced significant challenges in recruiting and retaining talent in recent years, are now hesitant to shed workers, even as economic growth moderates. This phenomenon, often referred to as "labor hoarding," can be a sign that businesses anticipate a future rebound in demand or are simply prioritizing the preservation of institutional knowledge and trained staff over short-term cost savings.
A Resilient Workforce: Low Layoffs Amidst Shifting Dynamics
The remarkably low jobless claims figures stand in contrast to other recent labor market indicators, which paint a more complex picture. While claims data primarily reflects layoffs, the pace of overall hiring has indeed decelerated. Nonfarm payrolls, a key measure of job creation, rose by a modest 29,000 in September. This figure falls significantly short of the monthly job gains often seen in robust economic expansions, and the average monthly gain for 2026 has been just 69,000. This slowdown in hiring is a clear departure from the explosive job growth experienced during the immediate post-pandemic recovery.
Despite the weaker hiring, the overall labor market remains tight due to the low rate of layoffs. Data from the Bureau of Labor Statistics (BLS) indicates that layoffs remained modest, declining by 61,000 in August. Furthermore, the layoff rate, measured as a share of the total workforce, fell to a mere 1% over the prior 12 months, down 0.2 percentage points during the period. This sustained low layoff rate suggests that the demand for labor, while not leading to aggressive new hiring, is robust enough to prevent widespread job losses. Businesses are seemingly prioritizing retention, perhaps recalling the difficulties they faced in finding qualified workers during the peak of the labor shortages. This stability in employment, even with slower job creation, provides a crucial buffer against a more significant economic downturn. Job openings, another critical indicator of labor demand, were relatively flat during the period, suggesting that while the intense competition for workers may have eased somewhat, demand for labor generally remains elevated.
Deciphering the Labor Market’s Mixed Signals
The interplay between low jobless claims, modest hiring, and a rising unemployment rate presents a nuanced challenge for economic analysis. The unemployment rate rose to 4.2% in the latest report, an increase that, on its surface, might appear concerning. However, this rise is largely attributable to a sharp spike in labor force participation. When more people enter the workforce—either seeking their first job or rejoining after a period of absence—the unemployment rate can temporarily tick up, even if the economy is creating jobs, because the pool of job seekers expands faster than available positions. Increased participation is generally considered a positive sign for an economy, indicating confidence in job prospects and potentially easing wage pressures over the long term. It suggests that individuals who may have been discouraged from seeking work previously are now re-engaging with the labor market, attracted by opportunities or driven by economic necessity.
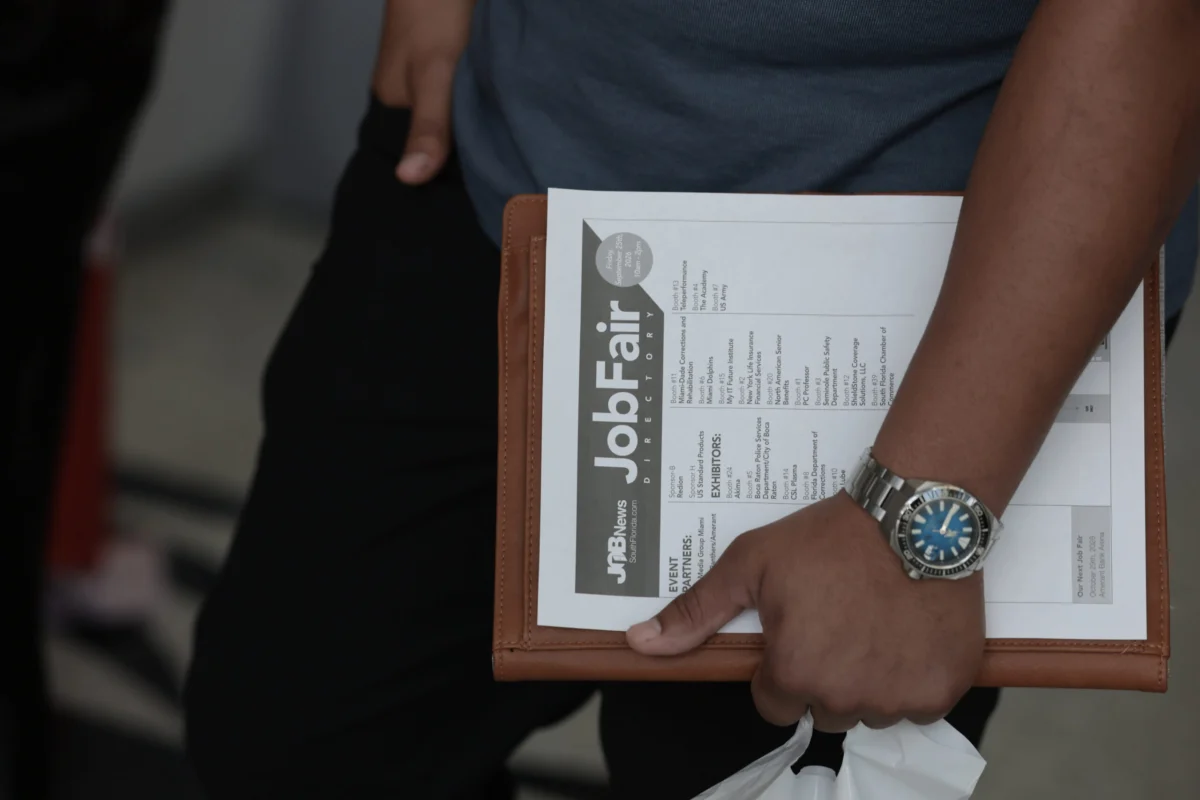
This dynamic underscores a key difference between a "weak" labor market characterized by mass layoffs and a "cooling" labor market where hiring slows, but job security remains high. The current situation leans heavily towards the latter, suggesting a rebalancing rather than a severe contraction. The photograph of a job seeker holding paperwork at the Mega JobNewsUSA South Florida Job Fair in Sunrise, Florida, on September 25, 2026, serves as a visual reminder of the ongoing search for employment, even as the broader data points to remarkable stability in existing jobs. Such fairs remain vital platforms for connecting available talent with persistent employer demand, particularly in regions experiencing population growth and economic diversification.
Economists Weigh In: Stability Amidst Uncertainty
Economists are carefully dissecting these mixed signals. Thomas Simons, chief U.S. economist at Jefferies, offered a perspective that encapsulates much of the current sentiment. In a client note, Simons stated, "Despite extremely pessimistic views expressed in consumer confidence surveys regarding the economy overall, countless headlines describing job cuts from a variety of businesses, and the phantom job-stealing power of AI, the claims data suggests that labor market conditions are stable." His assessment highlights the divergence between public perception and the hard data on layoffs. Consumer confidence surveys, often influenced by media headlines and general economic anxiety, can sometimes lag or misinterpret the underlying strength of employment.
The mention of "job cuts from a variety of businesses" typically refers to targeted layoffs, often in specific sectors like technology or finance, rather than economy-wide reductions. While these cuts are impactful for the individuals and companies involved, they have not translated into a systemic surge in unemployment claims across the broader economy. Furthermore, the "phantom job-stealing power of AI" refers to the ongoing public and academic debate about the long-term impact of artificial intelligence on employment. While AI is certainly transforming industries and job roles, current aggregate labor market data does not yet indicate a significant, widespread displacement of workers that would manifest in elevated jobless claims. Instead, many analysts suggest AI’s impact is more gradual, involving job augmentation and the creation of new roles, alongside the automation of some tasks. Other economists, echoing Simons’ sentiment, have posited that the current labor market exhibits a "soft landing" characteristic, where inflation cools without triggering a deep recession or widespread job losses. They argue that the persistent low level of layoffs is a crucial indicator that the economy is adjusting to higher interest rates without collapsing.
The Federal Reserve’s Tightrope Walk
The timing of this jobless claims data is particularly significant as it falls within the reference week that the BLS uses to calculate the broader payrolls growth number, which will be released on November 5. This makes the claims data a crucial preliminary indicator for the upcoming jobs report. Moreover, Federal Reserve officials are scheduled to gather next week to issue their latest decision on interest rates. Policymakers at the central bank have consistently characterized the labor market as a source of general strength in recent days, shifting their primary focus towards the more "nettlesome inflation problem" that has kept the pace of price increases well above the central bank’s 2% target.
The Fed operates under a dual mandate: to achieve maximum employment and price stability. The low jobless claims strongly support the "maximum employment" side of this mandate, even with the slower pace of hiring. This stability in employment allows the Fed greater latitude to focus on its inflation-fighting agenda. Despite a series of aggressive interest rate hikes over the past two years, core inflation metrics, such as the Consumer Price Index (CPI) reported for September 2026, have remained stubbornly elevated, preventing the central bank from declaring victory on price stability. Markets currently anticipate that the Fed will opt to hold off on a rate hike in October, allowing more time for the cumulative effects of previous hikes to work through the economy. However, there is a strong expectation for another quarter-percentage-point increase in December, as policymakers seek to ensure inflation is definitively brought under control. The continued strength in the labor market, as evidenced by these low jobless claims, provides the Fed with justification to maintain a hawkish stance, if necessary, without immediately risking a sharp rise in unemployment.
Historical Perspective: A Look Back at the Data
To fully appreciate the current jobless claims figures, a brief look at the historical trajectory is essential. The record low of 189,000 claims, and the current 194,000, stand in stark contrast to the dramatic spike witnessed at the onset of the COVID-19 pandemic in March 2020, when claims soared into the millions. The subsequent rapid decline, fueled by massive fiscal and monetary stimulus, saw claims return to pre-pandemic levels by late 2021. Since then, despite various economic headwinds—supply chain disruptions, geopolitical tensions, and aggressive interest rate hikes—jobless claims have largely remained within a remarkably low range.
The September 1969 low point for jobless claims occurred during a period of sustained economic expansion following the post-World War II boom. Unemployment rates were low, and the economy was experiencing strong growth, though inflationary pressures were beginning to emerge, setting the stage for the economic challenges of the 1970s. The fact that current claims are rivaling those from over half a century ago, despite a significantly larger workforce and a very different economic structure, speaks volumes about the current robustness of employer retention. It highlights that even in an era marked by rapid technological change and global economic uncertainties, the fundamental relationship between employers and their current employees remains remarkably stable.
Looking Ahead: Implications for Policy and the Economy
The implications of these sustained low jobless claims are far-reaching. For workers, it signifies continued job security, even if finding a new job might take slightly longer than during the peak of the hiring frenzy. This stability helps support consumer spending, a vital component of economic activity, as employed individuals are more likely to maintain their purchasing power. For businesses, the reluctance to lay off staff suggests that many anticipate continued demand for their products and services, or they are prioritizing the investment in their human capital.
For the Federal Reserve, the data provides a critical piece of the puzzle. It affirms the "maximum employment" side of its mandate, giving it more leeway to focus on battling inflation. If jobless claims were to rise significantly, it would signal a deteriorating labor market, potentially forcing the Fed to reconsider its aggressive stance on interest rates to avoid a deeper recession. As it stands, the low claims support the narrative that the economy is undergoing a "soft landing" – a scenario where inflation is brought down without triggering a severe economic downturn. However, the balance is delicate. The Fed must navigate between overtightening, which could eventually lead to higher unemployment, and undertightening, which would allow inflation to persist. The current jobless claims data provides a measure of confidence that the labor market, at least in terms of existing employment, remains resilient in the face of these challenges, offering a glimmer of stability in an otherwise uncertain economic climate. The coming months, particularly the release of the September jobs report and the Fed’s December rate decision, will be crucial in determining whether this stability can be maintained or if the mixed signals will eventually coalesce into a clearer, potentially less favorable, trend.