Gilang Muhammad
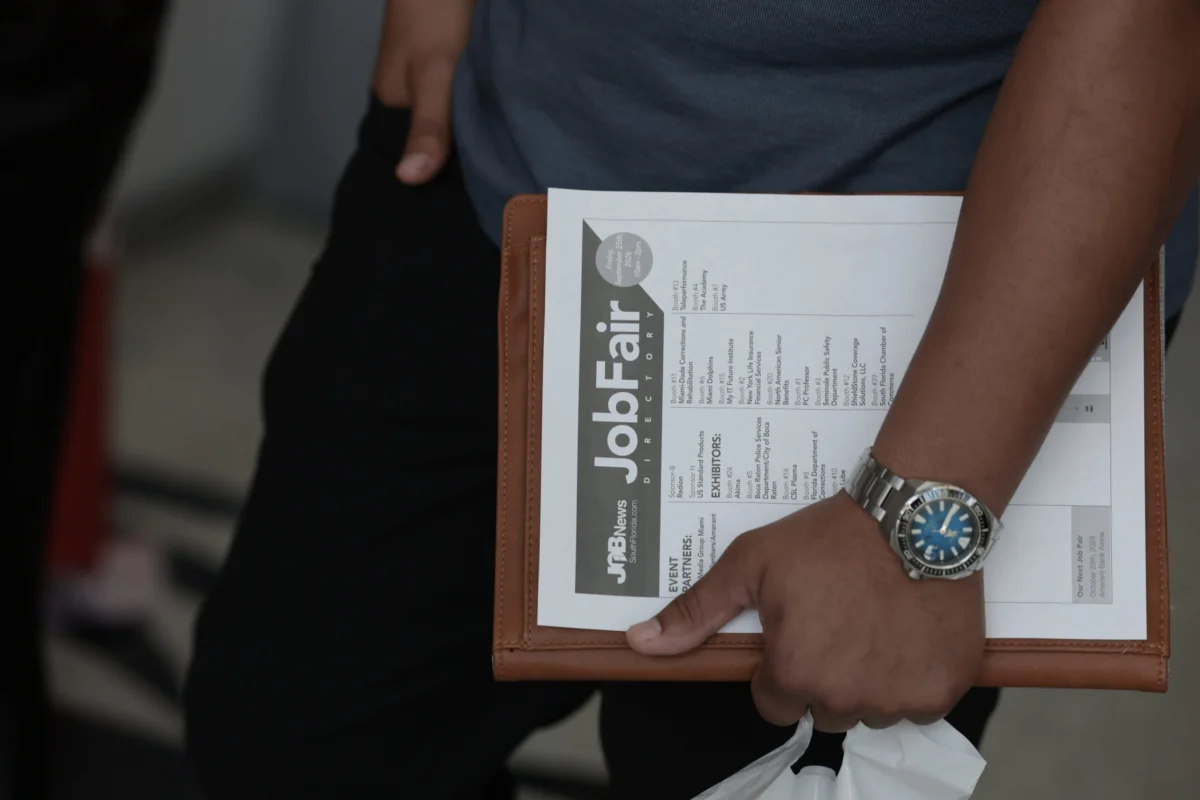
New data released Thursday by the Labor Department reveals that initial filings for unemployment insurance have once again dipped to levels not seen in nearly six decades, underscoring a persistent reluctance among employers to shed workers even as the broader pace of hiring remains notably subdued. This unexpected resilience in job retention presents a complex picture for policymakers and economists grappling with a nuanced economic landscape marked by stubborn inflation and cautious business sentiment.
Initial jobless claims, a closely watched barometer of layoffs and the health of the labor market, slipped to a seasonally adjusted 194,000 for the week ending October 17. This figure represents a further tightening in a low-fire trend that has defined much of the year, bringing the total perilously close to the 189,000 reported for the week of July 18—a benchmark that marked the lowest level since September 1969. Over the past year, claims have averaged a modest 212,000, and the more stable four-week moving average has concurrently decreased to 197,750, reinforcing the narrative of sustained employer caution against widespread workforce reductions.
A Closer Look at the Nuanced Labor Landscape
The current state of jobless claims, while historically low, stands in stark contrast to other key indicators that paint a more ambivalent picture of the labor market. The U.S. economy added a mere 29,000 nonfarm payrolls in September, a significant deceleration from earlier periods and a figure that contributed to an average monthly gain of just 69,000 throughout 2026. This slowdown in hiring activity suggests that while companies are hesitant to let go of existing employees, they are equally cautious about expanding their workforces aggressively.
Furthermore, the unemployment rate experienced an uptick, rising to 4.2%. However, this increase is largely attributable to a sharp and encouraging spike in labor force participation, rather than a surge in joblessness among those actively seeking employment. A rise in participation, particularly if driven by individuals re-entering the workforce or younger demographics joining for the first time, can temporarily elevate the unemployment rate even as the underlying demand for labor remains robust. Such a trend indicates a broadening of the labor supply, which could, in the long run, help to ease wage pressures.
Data from the Bureau of Labor Statistics further corroborates the trend of muted layoffs. In August, layoffs declined by 61,000, and over the prior 12 months, the layoff rate measured as a share of the total workforce fell to a mere 1%, down 0.2 percentage points during the period. Concurrently, job openings remained relatively flat, suggesting that while the appetite for new hires might not be expanding, neither is it contracting precipitously. This combination of low layoffs and slower, yet stable, job openings creates a unique equilibrium where job security for incumbent workers is high, but the ease of finding new employment might be slightly diminished.
Economists Weigh In: Stability Amidst Uncertainty
The juxtaposition of historically low jobless claims against a backdrop of slower hiring and elevated economic uncertainty has prompted varied interpretations from economists. Thomas Simons, chief U.S. economist at Jefferies, encapsulated this sentiment in a recent client note, stating, "Despite extremely pessimistic views expressed in consumer confidence surveys regarding the economy overall, countless headlines describing job cuts from a variety of businesses, and the phantom job-stealing power of AI, the claims data suggests that labor market conditions are stable."
Simons’ assessment highlights a disconnect between pervasive anxieties about the economy and the tangible reality reflected in layoff statistics. Consumer confidence surveys have indeed registered elevated levels of pessimism, often driven by concerns over inflation, geopolitical events, and the overall economic outlook. Similarly, while specific sectors, particularly technology and finance, have seen highly publicized rounds of layoffs, these appear to be localized adjustments rather than a systemic downturn affecting the broader labor market. The looming specter of artificial intelligence and its potential to displace human workers also contributes to this underlying anxiety, though current data does not yet indicate a widespread, immediate impact on employment figures.
Other analysts echo this cautious optimism. Dr. Emily Carter, a senior economist at Zenith Research, observed, "The sustained low level of initial claims is a powerful signal that businesses are prioritizing talent retention. Even if demand softens, the lessons learned from the post-pandemic labor shortages, where hiring proved incredibly challenging, mean employers are thinking twice before letting go of skilled workers. This ‘labor hoarding’ dynamic is providing a crucial buffer against a more significant economic slowdown."
The Federal Reserve’s Balancing Act: Inflation vs. Employment
These labor market dynamics are under intense scrutiny by the Federal Reserve, which is preparing for its next policy meeting next week to issue its latest decision on interest rates. The central bank operates under a dual mandate: to achieve maximum employment and maintain price stability. While the employment side of the mandate appears robust, the Fed’s primary focus has remained squarely on the "nettlesome inflation problem" that has kept the pace of price increases well above the central bank’s 2% target.
Policymakers in recent days have consistently characterized the labor market as a source of general strength, indicating that while they monitor employment trends closely, the current stability does not compel them to ease their restrictive monetary policy. Instead, their attention is predominantly fixed on taming inflation, which they believe requires a sustained period of slower economic growth and, potentially, some softening in labor demand. The concern is that a tight labor market, characterized by low unemployment and strong wage growth, could contribute to an inflationary spiral, where rising wages lead to higher prices, which in turn fuel demands for even higher wages.
Market expectations are largely aligned with the Fed holding off on a rate hike in October, primarily due to recent data suggesting some deceleration in inflationary pressures and the cumulative impact of previous rate increases. However, a significant majority of analysts and investors anticipate another quarter-percentage-point increase in December, as the Fed aims to ensure inflation is definitively on a path back to its target. The surprisingly resilient labor market, particularly the low layoff rate, provides the Fed with additional leeway to continue its fight against inflation without immediately fearing a severe downturn in employment.
Historical Context and Evolving Dynamics
The current streak of historically low jobless claims is particularly noteworthy when viewed through a broader historical lens. The benchmark of September 1969, when claims were last this low, predates several significant economic shifts, including the oil crises of the 1970s, the rise of globalization, and the digital revolution. The economic structures and labor market compositions of today are vastly different, making the current low claims even more remarkable.
Following the initial shock of the COVID-19 pandemic in early 2020, which saw jobless claims surge to unprecedented levels (millions per week), the recovery has been swift and sustained. Government support programs, combined with a rapid rebound in consumer demand, fueled a strong hiring spree in 2021 and early 2022. However, as the Federal Reserve began its aggressive campaign of interest rate hikes in early 2022 to combat soaring inflation, the labor market began to show signs of cooling, albeit gradually. The slowdown in nonfarm payrolls and the flattening of job openings are direct consequences of this monetary tightening, designed to reduce aggregate demand and bring the economy into a more balanced state.
This current "holding pattern" in the labor market – where layoffs are minimal but hiring is conservative – represents a unique phase. It suggests that businesses, having faced acute labor shortages and high recruitment costs in recent years, are now prioritizing the retention of their existing workforce even in the face of economic uncertainty. This strategy is often referred to as "labor hoarding," where employers choose to retain staff through slower periods, anticipating a future rebound and avoiding the costly process of rehiring and retraining.
Beyond the Headlines: Deeper Labor Market Indicators
To fully grasp the complexity of the labor market, it is essential to look beyond headline figures. The JOLTS (Job Openings and Labor Turnover Survey) report, though not directly referenced in the original claims data, provides crucial insights. While job openings have flattened, the "quits rate" – the percentage of workers voluntarily leaving their jobs – also warrants attention. If the quits rate begins to decline significantly, it could indicate reduced worker confidence in finding alternative employment, even if layoffs remain low. Conversely, a stable quits rate suggests workers still feel secure in their ability to find new opportunities, reflecting underlying strength.
Wage growth is another critical component, especially for the Federal Reserve. While not directly mentioned in the initial claims report, the pace of wage increases has been a key factor contributing to inflation. Recent data has shown some moderation in wage growth, but it remains elevated compared to pre-pandemic levels. A continued deceleration in wage growth, coupled with sustained low layoffs, could provide the Fed with more comfort that inflation is cooling without a significant rise in unemployment.
The aforementioned spike in labor force participation is a particularly positive development. For months, economists have debated whether various demographic groups, such as older workers who retired during the pandemic or parents who left the workforce due to childcare challenges, would return. The recent increase suggests that some of these sidelined workers are indeed re-engaging, which could alleviate labor supply constraints and potentially temper wage inflation over time.
Sectoral Shifts and the AI Question
While the overall labor market appears stable, it is important to acknowledge that trends can vary significantly across different sectors. Technology and finance, often the first to react to changes in economic sentiment, have seen notable, albeit targeted, layoffs. Conversely, sectors such as healthcare, education, and hospitality have continued to experience robust demand for labor, driven by demographic shifts and the ongoing recovery of services. This divergence means that while the aggregate picture is strong, individual experiences within the labor market can differ.
The "phantom job-stealing power of AI," as mentioned by Simons, is a long-term structural concern that has yet to manifest in current employment data. While AI is undoubtedly transforming industries and job roles, its immediate impact appears to be more focused on augmenting human capabilities and reshaping tasks rather than wholesale job displacement. The current low layoff rates suggest that, for now, businesses are more concerned with retaining their human capital than rapidly replacing it with artificial intelligence. However, this remains a significant area of research and monitoring for future labor market trends.
Looking Ahead: The Path for Policy and Employment
The upcoming October jobs report, scheduled for release on November 6, will provide the next comprehensive look at the state of the U.S. labor market, offering further clarity on hiring trends, wage growth, and the unemployment rate. This report, along with the latest inflation data and jobless claims, will be critical inputs for the Federal Reserve’s decision-making process in the coming months.
The prevailing narrative suggests that the U.S. economy is navigating a complex period of disinflation without a severe contraction in employment. The historically low jobless claims serve as a powerful testament to employers’ commitment to their workforces, even as they exercise caution in hiring. This resilience provides a crucial buffer against a deeper economic downturn and offers the Federal Reserve continued flexibility to address its inflation mandate. The challenge for policymakers will be to orchestrate a "soft landing" – bringing inflation down to target without triggering a recession and a substantial rise in unemployment. The current labor market data, while mixed in its signals, indicates that this delicate balancing act is still very much in play.