Gilang Muhammad
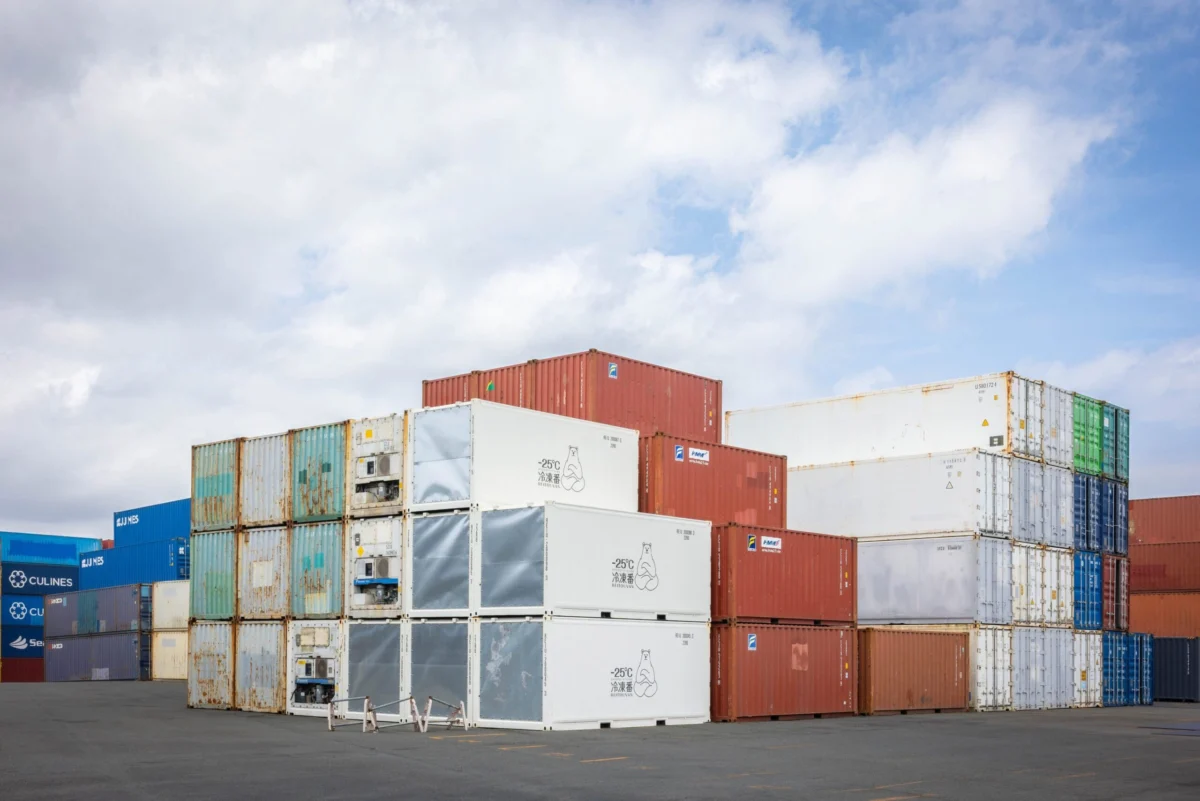
YOKOHAMA, KANAGAWA, JAPAN – Japan’s economic performance took an unexpected turn in the third quarter of 2023, with data revealing a contraction at an annualized rate of 0.1% compared to the preceding quarter. This downturn, a significant deviation from market expectations, has raised fresh concerns among policymakers and economists about the fragility of the nation’s post-pandemic recovery. The contraction, covering the three months ending September, was primarily driven by a slowdown in domestic consumption and a persistent drag from net exports, which were impacted by higher energy imports. The unexpected shrinkage stands in stark contrast to a Reuters poll that had projected a modest growth of 0.3% for the period, and represents a notable deceleration from the robust 1.4% expansion recorded in the second quarter. The visual of bustling shipping containers at Honmokufuto port in Yokohama, a critical gateway for Japan’s international trade, underscores the vital role of exports and imports in the nation’s economic health, yet the latest figures suggest that the dynamics within these trade flows are currently weighing down overall growth.
Unexpected Contraction: Key Figures and Components
The initial flash estimate for Japan’s Gross Domestic Product (GDP) by the Cabinet Office painted a somber picture, indicating a real GDP contraction of 0.04% on a quarter-on-quarter basis, translating to an annualized decline of 0.1%. This figure was a significant disappointment following a strong second quarter, which saw a 0.3% quarter-on-quarter expansion, equivalent to an annualized 1.4% growth. The primary culprits behind this reversal were identified as a slowdown in private consumption and a negative contribution from net exports.
Private consumption, a cornerstone of Japan’s economy, accounts for over half of its GDP. In the third quarter, it registered a modest 0.0% growth on a quarter-on-quarter basis, essentially stagnating after showing signs of recovery in previous periods. This stagnation suggests that inflationary pressures, subdued wage growth, and a cautious consumer sentiment are collectively dampening household spending. While the government had implemented various measures to support consumption, including subsidies and campaigns, their impact appears to be waning or insufficient to counter the prevailing headwinds.
The other major component weighing heavily on the economy was net exports. Despite Japan’s overall exports beating expectations for two out of the three months within the quarter, the balance of trade ultimately exerted a negative influence on GDP. This was largely due to the elevated cost of imports, particularly energy. The data indicated that net exports subtracted a substantial 0.6 percentage points from the country’s growth. This highlights Japan’s vulnerability to global commodity price fluctuations and the impact of a depreciating yen, which makes imports more expensive when denominated in local currency.
Other components of GDP also showed mixed performance. Private non-residential investment, often seen as a barometer of business confidence, grew by a marginal 0.3% quarter-on-quarter, indicating some resilience but not enough to offset the weaknesses elsewhere. Private residential investment, on the other hand, declined by 0.1%, suggesting ongoing challenges in the housing sector. Government consumption remained relatively flat, while public investment saw a robust increase of 1.1%, potentially reflecting ongoing infrastructure projects or stimulus spending aimed at propping up the economy.
Deeper Dive into Domestic Consumption Challenges
The stagnation in private consumption is perhaps the most concerning aspect of the latest GDP report. Historically, robust domestic demand has been a key driver of Japan’s economic growth. The current slowdown can be attributed to several intertwined factors. Inflation, which has remained above the Bank of Japan’s 2% target for an extended period, has eroded the purchasing power of households. While headline Consumer Price Index (CPI) figures have shown some moderation recently, the cost of essential goods, including food and energy, remains elevated. Data from the Ministry of Internal Affairs and Communications consistently shows year-on-year increases in the cost of living, squeezing household budgets.
Wage growth, while showing some improvement compared to previous years, has largely failed to keep pace with inflation. Preliminary figures from the Ministry of Health, Labour and Welfare indicated that real wages, adjusted for inflation, continued to decline for several consecutive months leading up to and during the third quarter. This mismatch means that even if nominal wages are rising, households feel poorer in real terms, leading to more cautious spending habits. Consumer confidence surveys, such as those conducted by the Cabinet Office, have reflected this sentiment, often showing a deteriorating outlook on future income and employment, which further inhibits discretionary spending. Sectors typically reliant on robust consumer spending, such as retail, hospitality, and entertainment, are feeling the pinch. Despite the lifting of all pandemic-era restrictions and the return of inbound tourism, the domestic consumer base appears hesitant to spend freely.
The Persistent Drag of Net Exports and Global Headwinds
Japan, as a major exporting nation, is highly susceptible to global economic fluctuations. While the country’s exports initially showed resilience, beating expectations in July and August, the overall contribution of net exports to GDP turned negative in Q3. This phenomenon, where exports grow but net exports contract, is primarily explained by the surge in import costs. Japan is heavily reliant on imported energy, particularly oil and natural gas, to power its industries and homes. Geopolitical tensions, production cuts by oil-exporting nations, and robust global demand have kept energy prices high throughout the year.
Compounding this issue is the significant depreciation of the Japanese yen against major currencies, particularly the U.S. dollar. The yen’s weakness, driven largely by the Bank of Japan’s ultra-loose monetary policy contrasting with tighter policies elsewhere, has made imported goods, especially energy and raw materials, considerably more expensive when purchased in yen. This dynamic directly inflates the value of imports in GDP calculations, thereby subtracting more from overall growth. Even as Japanese exporters benefit from a weaker yen, which makes their products more competitive abroad, the higher cost of imported inputs for manufacturing and energy for operations can eat into their profits and overall economic contribution.
Beyond energy, a broader slowdown in global demand also began to impact Japan’s export-oriented industries. Key trading partners, such as China, have faced their own economic challenges, including a property market crisis and subdued consumer confidence, which reduced demand for Japanese goods. Economic slowdowns in Europe and the United States, driven by high interest rates and inflationary pressures, further contributed to a less favorable external environment for Japanese exports. Exports of capital goods and electronic components, critical for Japan’s manufacturing sector, began to show signs of softening towards the end of the quarter.
Market Reaction: Navigating Uncertainty
Following the release of the unexpectedly weak GDP data, financial markets exhibited a nuanced reaction, reflecting a complex interplay of immediate concerns and speculative outlooks. The Nikkei 225 stock index, Japan’s benchmark equity gauge, initially showed resilience, rising by 0.4%. This seemingly counterintuitive rise can often be attributed to several factors. Firstly, a weaker yen, which continued its trend of depreciation following the data release, typically benefits Japan’s large export-oriented companies by boosting their overseas earnings when converted back into yen. Investors might have anticipated that the weak economic data would reinforce the Bank of Japan’s commitment to its ultra-loose monetary policy, thus sustaining the yen’s weakness and supporting exporter profits. Secondly, poor economic data can sometimes fuel speculation that the government might introduce new fiscal stimulus measures or that the central bank might further delay any potential policy tightening, which can be seen as positive for equity markets in the short term.
The yield on the benchmark 10-year Japanese Government Bonds (JGBs) also reflected market dynamics. It was recorded at 2.885% immediately after the data release. The Bank of Japan’s long-standing Yield Curve Control (YCC) policy aims to cap the 10-year JGB yield around 0%, though it has introduced more flexibility recently. The slight increase in yield, while still relatively low compared to global standards, suggests that the market is constantly testing the BoJ’s resolve and anticipating potential future adjustments to its YCC policy, even if the immediate data points to continued dovishness.
Meanwhile, the Japanese yen weakened marginally against the U.S. dollar, trading at 159.76. This depreciation underscores the persistent monetary policy divergence between the Bank of Japan and other major central banks, particularly the U.S. Federal Reserve, which has aggressively hiked interest rates. The weak GDP data reinforces expectations that the BoJ will be compelled to maintain its negative interest rates and YCC policy for an extended period to support the economy, thus keeping the yen less attractive to yield-seeking investors compared to higher-yielding currencies. This weakening trend has been a significant concern for Japanese households and businesses reliant on imports, despite the competitive boost it offers to exporters.
Contextualizing Japan’s Economic Landscape
Japan’s economic journey in recent decades has been characterized by unique challenges, including a rapidly aging population, persistent deflationary pressures, and a substantial public debt burden. The current contraction needs to be viewed within this broader historical and demographic context. While the nation has made strides in certain areas, such as technological innovation and global trade integration, underlying structural issues continue to pose significant headwinds.
The post-pandemic recovery has been uneven. While global supply chain disruptions have largely eased, new challenges have emerged, including geopolitical instability, high global inflation, and a synchronized slowdown in major economies. Japan’s reliance on global trade means that it is particularly susceptible to these external shocks. The current situation also highlights the dilemma faced by the Bank of Japan, which has maintained an ultra-loose monetary policy for years to combat deflation and stimulate growth, even as other central banks globally have tightened their policies to combat soaring inflation. This divergence is a key factor driving the yen’s weakness and impacting import costs.
The government, under Prime Minister Fumio Kishida, has been actively pursuing policies aimed at fostering sustainable growth, including efforts to boost wages, promote investment in green technologies, and enhance economic security. However, the latest GDP figures suggest that these initiatives are yet to fully translate into broad-based economic strength, underscoring the deep-seated nature of the challenges.
The Bank of Japan’s Enduring Ultra-Loose Stance
The unexpected economic contraction places additional scrutiny on the Bank of Japan’s monetary policy. For years, the BoJ has maintained an unconventional ultra-loose stance, characterized by a negative short-term interest rate (minus 0.1%) and its Yield Curve Control (YCC) framework, which targets the 10-year JGB yield around 0% with a flexible upper bound. The primary objective of this policy has been to achieve stable 2% inflation and stimulate economic activity.
The latest GDP data, showing a contraction and stagnant consumption, reinforces the argument for the BoJ to maintain its accommodative stance. Any move towards tightening policy, such as raising interest rates or significantly altering YCC, could further dampen consumption and investment, potentially pushing the economy into a deeper downturn or even a technical recession (two consecutive quarters of contraction). This situation puts the BoJ in a difficult position, as it must balance the need to support a faltering economy with the desire to normalize policy eventually and address the negative side effects of prolonged easing, such as distortions in financial markets and the weakening yen.
While some analysts had anticipated a possible shift in BoJ policy earlier in the year as inflation picked up, the Q3 GDP figures are likely to push back any expectations for near-term tightening. Governor Kazuo Ueda and other BoJ officials are expected to reiterate their commitment to supporting the economy until stable and sustainable inflation, accompanied by robust wage growth, is firmly achieved. This stance implies a continued divergence from the monetary policies of the U.S. Federal Reserve and the European Central Bank, which have both aggressively raised rates to combat inflation.
Government’s Policy Toolkit and Fiscal Response
In response to the economic headwinds, the Japanese government has a range of fiscal policy tools at its disposal. Prime Minister Kishida’s administration has already implemented various stimulus packages since taking office, focusing on areas like energy subsidies, support for vulnerable households, and promoting investment. The latest GDP data will undoubtedly intensify calls for further government action.
Officials from the Cabinet Office and the Ministry of Finance are likely to acknowledge the challenges posed by the contraction and emphasize the government’s commitment to supporting economic recovery. Potential measures could include new rounds of direct aid to households, further extensions of energy subsidies, or targeted support for industries struggling with high import costs or sluggish demand. Investment in public works, as evidenced by the 1.1% increase in public investment in Q3, is another avenue through which the government can inject demand into the economy.
However, the government also faces fiscal constraints, given Japan’s already substantial public debt, which is the highest among developed nations as a percentage of GDP. Any new stimulus package would need to be carefully crafted to maximize its impact while managing fiscal responsibility. The balance between short-term relief and long-term structural reforms will be a key consideration for policymakers. The government’s focus on wage growth, as a means to sustainably boost consumption, will also gain renewed urgency.
Expert Analysis and Future Outlook
Economists and market analysts are now recalibrating their forecasts for Japan’s economy. Many are pointing to the heightened risk of a technical recession in the current quarter (Q4 2023) if the economy contracts again. "This data is a clear warning sign that Japan’s recovery is far from stable," stated one Tokyo-based economist, who requested anonymity due to corporate policy. "The twin pressures of weak domestic demand and expensive imports are proving difficult to overcome, even with a strong rebound in tourism."
Analysts are particularly concerned about the persistence of negative real wage growth, which directly impacts consumer spending. While inbound tourism has seen a robust recovery, contributing positively to the service sector, its impact has not been enough to offset the broader weaknesses in domestic consumption. The global economic outlook also remains a significant risk factor. Should major economies like the U.S. and China experience deeper slowdowns, Japan’s export sector would face even greater challenges.
Looking ahead, the outlook remains cautiously optimistic for a gradual recovery, but significant headwinds persist. The timing of any potential BoJ policy shift will now likely be pushed further into 2024, or even later, depending on how inflation and wage growth evolve. The government’s ability to implement effective fiscal measures that genuinely stimulate demand and investment will be crucial. The focus will be on whether the current contraction is a temporary blip or indicative of a more entrenched period of slow growth.
Broader Implications for Businesses and Households
The unexpected economic contraction carries significant implications for various stakeholders within Japan. For businesses, particularly those reliant on the domestic market, the stagnation in consumption translates to reduced sales and revenue. Small and medium-sized enterprises (SMEs) are particularly vulnerable to these pressures, as they may have less flexibility to absorb higher input costs or declining demand. Exporters, while benefiting from a weaker yen, face the dual challenge of higher import costs for raw materials and components, alongside a potentially shrinking global market. Corporate earnings, which had shown resilience in some sectors, may come under renewed pressure.
Households will continue to feel the pinch of elevated living costs and stagnant real wages. The hope for a significant wage increase that outpaces inflation, a key objective for both the government and the BoJ, appears to be a distant prospect for many. This can lead to increased financial strain, reduced savings, and a cautious approach to major purchases, further perpetuating the cycle of weak consumption.
On an international level, Japan’s economic performance is closely watched as the world’s third-largest economy. A sustained period of weakness could have ripple effects on global trade and investment flows. While Japan’s economy is structurally sound in many respects, the latest data serves as a stark reminder of the challenges it faces in achieving sustainable, inflation-driven growth amidst a complex global economic environment. The focus will now turn to the upcoming Q4 data and the policy responses from both the Bank of Japan and the government to navigate these turbulent economic waters.