Gilang Muhammad
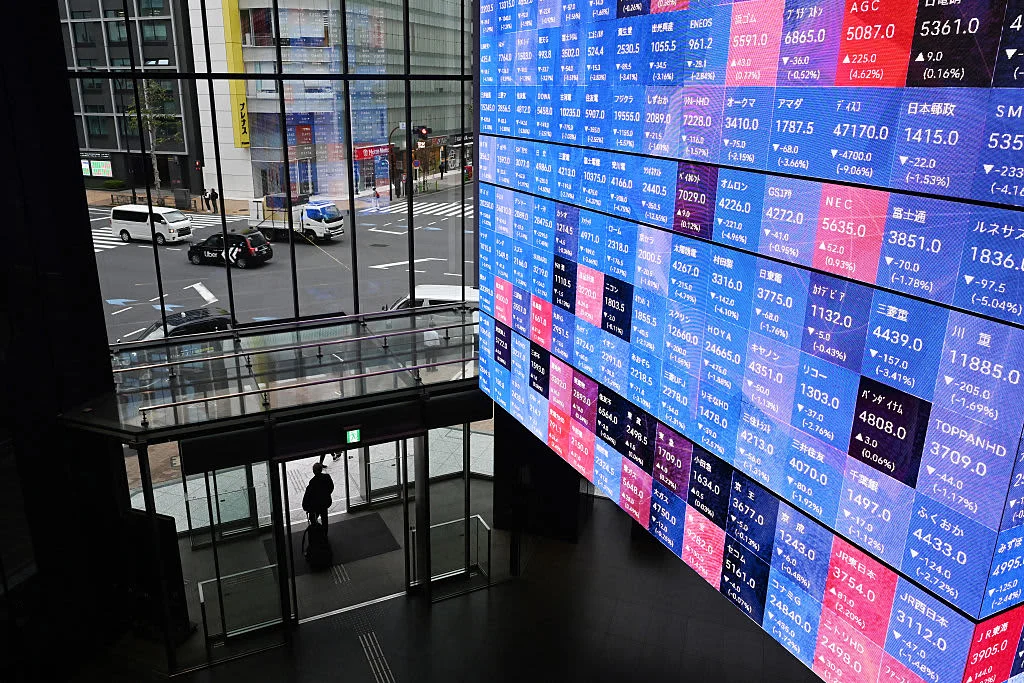
Tokyo, Japan – November 5, 2025 – Japanese financial markets displayed a strikingly counterintuitive reaction on Friday following the Bank of Japan’s (BOJ) decision to raise its benchmark interest rate to 1.25%, the highest level seen in 31 years. Contrary to conventional economic wisdom, which posits that interest rate increases typically bolster a nation’s currency, elevate its bond yields, and exert downward pressure on its stock market, Japan witnessed precisely the opposite. The yen unexpectedly weakened past 157 against the U.S. dollar, the yield on the bellwether 10-year Japanese Government Bond (JGB) slipped, and the Nikkei 225 stock index remarkably climbed by 1.5%. This perplexing market response has prompted a closer examination of the BOJ’s internal dynamics and its communication strategy.
A Shift in Policy: Unpacking the BOJ’s Latest Move
The Bank of Japan’s Monetary Policy Board, concluding its meeting on November 5, 2025, announced the decision to increase the policy rate by 25 basis points to 1.25%. This move marks the latest step in a gradual but significant pivot away from decades of ultra-loose monetary policy, which had been characterized by negative interest rates and an expansive quantitative easing program. This particular hike brought the policy rate to its highest point since 1995, a year marked by significant economic shifts globally and domestically. Notably, this increase came just three months after a previous adjustment, signaling an accelerating pace of normalization for the central bank.
For years, the BOJ had been an outlier among major central banks, steadfastly maintaining an accommodative stance to combat persistent deflation and stimulate economic growth. While central banks like the U.S. Federal Reserve and the European Central Bank embarked on aggressive tightening cycles in 2022-2024 to curb soaring inflation, the BOJ moved cautiously, only beginning to unwind its negative interest rate policy in March 2025, when it first lifted rates above zero to 0.5%. A subsequent hike in August 2025 brought the rate to 1.0%, making the latest November move the third increase within the calendar year.
The Counterintuitive Market Reaction: Decoding the Discrepancy
The immediate aftermath of the BOJ’s announcement left many market observers scratching their heads. A rate hike, in theory, makes a country’s assets more attractive to foreign investors, increasing demand for its currency and thus strengthening it. Higher rates also typically lead to higher government bond yields as investors demand greater compensation for holding debt in a rising rate environment. Conversely, higher borrowing costs can dampen corporate profits and consumer spending, often leading to a pullback in stock markets. Japan’s markets, however, defied these expectations.
The yen’s depreciation beyond 157 per dollar, extending its multi-year weakening trend, was particularly striking. For context, the yen had traded in the 110-120 range against the dollar for much of 2021-2022, only to experience a dramatic decline as the interest rate differential between Japan and other major economies widened significantly. While it had briefly dipped below 160 earlier in 2025, market participants had anticipated that further BOJ tightening would provide some much-needed support for the beleaguered currency. Similarly, the dip in the 10-year JGB yield, which indicates falling bond prices, suggested that investors were not demanding higher returns, contradicting the tightening narrative. The Nikkei 225’s robust 1.5% gain further underscored the market’s divergent interpretation of the BOJ’s actions.
Behind the Dissent: A Divided Board Shapes Expectations
Experts quickly converged on the split decision by the BOJ’s nine-member board as the primary catalyst for the uncharacteristic market reaction. The vote to raise rates passed by a 7-2 margin, with board members Toichiro Asada and Ayano Sato dissenting from the majority verdict. This unexpected level of internal disagreement signaled to markets that the central bank might not be as united or as committed to an aggressive tightening path as some had anticipated.
Hirofumi Suzuki, chief FX strategist at Japanese bank Sumitomo Mitsui Banking Corporation, articulated this sentiment, stating, "The two dissenting votes in favor of keeping rates unchanged came as a surprise." He further elaborated that such a visible division could be interpreted as a lack of strong conviction within the BOJ, tempering expectations for a rapid series of future hikes.
The arguments put forth by the dissenting members provided further clarity. Toichiro Asada expressed concerns that with the core inflation rate remaining below the central bank’s 2% target, the underlying economic situation might not be sufficiently robust to withstand further tightening. Core inflation for August in Japan stood at 1.7%, a slight decrease from 1.8% in July. While positive, this figure still hovered below the sustained 2% level that the BOJ has long targeted as a sign of healthy demand-driven inflation. Ayano Sato echoed similar reservations, noting that current economic and price developments did not appear to have substantially accelerated compared to previous assessments, suggesting that the inflationary pressures might not be as entrenched or widespread as the majority believed.
The Absence of a Hawkish Reinforcement: Missing Outlook and Muted Tone
Another critical factor contributing to the market’s muted hawkish interpretation was the absence of an updated outlook report accompanying the rate hike. Typically, central banks utilize these reports to provide detailed projections for inflation, economic growth, and other key indicators, thereby reinforcing their policy stance and guiding market expectations. Without such a report, the BOJ’s ability to project a strong, consistent hawkish message through revised forecasts was significantly limited.
Masahiko Loo, senior fixed income strategist at State Street Investment Management, highlighted this deficiency, noting that the lack of an updated outlook hindered the BOJ’s communication. This view was strongly supported by Shigeto Nagai, head of Japan economics at Oxford Economics. Nagai, speaking to CNBC’s "Access Middle East," further emphasized that the tone of the BOJ’s official statement itself was less hawkish than financial markets had hoped for. "If we look at the statement, all the phrases and the tone was almost similar to what we saw in the quarterly outlook report published in July," Nagai explained, indicating that the language failed to signal any heightened urgency or aggressive forward guidance.
Japan’s Long Road from Deflation: A Historical Perspective
To fully appreciate the significance of the BOJ’s recent moves, it is essential to contextualize them within Japan’s unique economic history. For nearly three decades, Japan grappled with persistent deflation, a phenomenon where prices continuously fall, leading to delayed consumption, reduced investment, and stagnant wages. In response, the BOJ pioneered some of the most unconventional monetary policies globally, including quantitative easing (QE) from the early 2000s, negative interest rate policy (NIRP) introduced in 2016, and the innovative yield curve control (YCC) framework, also launched in 2016. YCC aimed to keep long-term government bond yields anchored around zero, further suppressing borrowing costs.
The objective of these policies was clear: to stimulate inflation towards the elusive 2% target and kickstart a virtuous cycle of economic growth. While these measures prevented a deeper deflationary spiral, they largely failed to achieve sustained, demand-driven inflation. However, the global inflation surge post-COVID-19, driven by supply chain disruptions, robust demand, and commodity price spikes, began to exert upward pressure on Japanese prices, albeit with a significant lag compared to Western economies. This global backdrop, coupled with a weakening yen making imports more expensive, finally provided the BOJ with an opportunity to consider normalization. The initial steps involved gradually widening the permissible band for JGB yields under YCC in 2023 and 2024, before ultimately abandoning NIRP and YCC in March 2025, marking the true beginning of the exit strategy.
The Yen’s Tumultuous Journey and Economic Implications
The yen’s persistent weakness has been a double-edged sword for Japan. While a weaker currency generally benefits large Japanese exporters by making their goods cheaper overseas and boosting repatriated profits when converted back into yen, it simultaneously drives up the cost of imports, particularly crucial energy and food items. Japan is heavily reliant on imported fossil fuels, and the Middle East conflict mentioned in the BOJ’s statement has exacerbated oil price volatility, adding inflationary pressure through higher import costs.
The Ministry of Finance has frequently expressed concern over excessive yen volatility, often issuing verbal warnings against rapid depreciations. While direct intervention in currency markets is a tool at its disposal, the current situation highlights the complex interplay between monetary policy, global economic conditions, and geopolitical events. For domestic consumers, a weak yen translates to higher prices at the pump and the grocery store, eroding purchasing power, especially if wage growth fails to keep pace with inflation.
Global Pressures and Domestic Realities
The BOJ acknowledged in its statement that while it intends to continue raising rates as economic and price conditions develop, growth was likely to decelerate due to high oil prices stemming from the Middle East conflict. This external shock adds another layer of complexity to Japan’s monetary policy decisions. The global economic landscape in late 2025 is characterized by ongoing geopolitical tensions, persistent inflationary pressures in some regions, and concerns about a potential global slowdown.
Domestically, while inflation has finally breached the 2% mark for a period, questions remain about its sustainability and whether it is truly demand-driven. Japan also faces unique structural challenges, including a rapidly aging and shrinking population, which impacts labor supply, productivity, and domestic demand. These factors underscore the BOJ’s cautious approach, as it seeks to normalize policy without stifling nascent economic recovery or triggering a new downturn.
International Scrutiny: U.S. Influence on BOJ Policy
The role of international pressure, particularly from the United States, in influencing the BOJ’s policy trajectory cannot be overlooked. Reuters reported on Friday that U.S. Treasury Secretary Scott Bessent had explicitly stressed the need for higher BOJ rates during his meeting with Japanese Finance Minister Satsuki Katayama in May 2025. This pressure stems from the U.S. desire for greater global monetary policy coordination and a stronger yen to alleviate inflationary pressures on its own economy.
Shigeto Nagai of Oxford Economics suggested that the dissenting votes within the BOJ board might also signal that Prime Minister Sanae Takaichi’s administration was not entirely convinced to accede to the U.S.’s request for faster and more aggressive rate hikes. This highlights the delicate balancing act faced by Japanese policymakers, who must navigate domestic economic imperatives while also considering international relations and the impact on global financial stability. The U.S. has a vested interest in a more stable yen and a Japan that contributes to global disinflation efforts.
Looking Ahead: The Path of Future Hikes
Despite the market’s immediate, tempered reaction, the consensus among experts remains that further rate hikes from the BOJ are firmly on the table. State Street’s Masahiko Loo expects BOJ Governor Kazuo Ueda to continue emphasizing that "every forthcoming meeting remains ‘live’," indicating that the central bank retains flexibility for future adjustments. Loo added, "The debate is no longer whether the BOJ hikes, but how far rates ultimately go."
Sam Jochim, economist at EFG International, projects that rates could rise roughly once every three months as underlying inflation steadily approaches the 2% target. He forecasts a "terminal rate"—the expected peak level of interest rates in a tightening cycle—between 1.75% and 2% by 2027. This suggests a continued, albeit measured, tightening path over the next two years.
However, the BOJ itself has refrained from forecasting a terminal rate, instead maintaining its stance that it will conduct monetary policy "as appropriate" to stabilize underlying inflation at around its 2% target. Stefan Angrick, head of Asia-Pacific economics at Moody’s Analytics, expects another increase around the turn of the year, likely in December 2025 or early 2026. Nevertheless, Angrick cautioned that weak demand-driven inflation and disappointing real-wage growth would likely limit the extent and pace of subsequent moves. Sustained wage growth, in particular, is seen as crucial for generating a durable inflationary environment.
Broader Economic Impact: Winners and Losers
The trajectory of Japan’s interest rates will have profound implications across various sectors of its economy. Exporters, who have benefited immensely from the weak yen in recent years, may see their competitive edge erode if the yen eventually strengthens. Conversely, importers, who have faced rising costs, stand to gain from a stronger currency.
For domestic businesses, higher borrowing costs could dampen investment and expansion plans, particularly for small and medium-sized enterprises (SMEs) that are more sensitive to interest rate fluctuations. Consumers, while potentially benefiting from future yen strength mitigating import costs, also face the immediate challenge of higher prices for daily necessities if inflation persists without corresponding wage increases. The government, with its massive debt pile, will also face higher debt servicing costs as bond yields rise, although the BOJ’s gradual approach and the dip in JGB yields after this hike suggest this pressure might be manageable in the short term. The real estate sector, which has enjoyed ultra-low mortgage rates for years, will likely see a gradual increase in borrowing costs, potentially cooling a previously buoyant market.
In conclusion, the Bank of Japan’s latest rate hike represents a complex and nuanced step in its long journey toward monetary policy normalization. The counterintuitive market reaction, driven by a divided board and a measured communication strategy, underscores the delicate balance the central bank must strike. As Japan grapples with domestic economic realities, global pressures, and international expectations, the path ahead for its monetary policy will continue to be closely watched, with profound implications for its economy and the broader global financial landscape.