Gilang Muhammad
The Eurozone’s economic expansion decelerated to 0.4% in the third quarter of 2026, according to figures released by statistics agency Eurostat on Friday, marking a notable slowdown from the 0.6% growth observed in the second quarter, which had followed a period of stagnation in the first three months of the year. While this flash reading for the July-September period surpassed the 0.2% growth forecast by a Reuters poll of economists, the headline figure masked significant disparities among member states, most notably an unexpected 0.1% contraction in France’s economy, which coincides with escalating nationwide protests over the cost of living and the government’s fiscal policies.
A Mixed Economic Picture Across the Euro Area
The Eurozone, comprising 21 nations, has been grappling with a complex economic landscape characterized by persistent inflationary pressures, the lingering effects of global supply chain disruptions, and geopolitical uncertainties, particularly the ongoing Middle East crisis impacting energy markets. The 0.4% growth rate in the third quarter suggests a cautious recovery, yet one unevenly distributed. Germany, the bloc’s largest economy, managed a modest 0.2% growth, reflecting its struggles with industrial output and export demand in a challenging global trade environment. Italy, the third-largest economy, recorded flat growth, indicative of enduring structural impediments and a slower post-pandemic rebound compared to some of its peers.
In stark contrast to France’s contraction, Spain demonstrated robust performance, expanding by 0.6% in the third quarter. This growth positions Spain above the Euro area average, bolstered by a resilient labor market, a thriving tourism industry, robust domestic demand, and a relatively strong fiscal position. However, even Spain has not been immune to social discontent, having recently experienced its own wave of mass protests over housing shortages and cost-of-living pressures, which ultimately led to a snap election being called for next month. Ireland, often an outlier due to its unique economic structure, reported an impressive 5.5% growth. However, economists frequently caution that Ireland’s headline GDP figures are highly volatile and subject to substantial revision, largely due to the significant presence of multinational corporations domiciled in the country but conducting much of their business operations elsewhere, leading to a skew in traditional economic metrics.
France’s Dual Crisis: Economic Contraction and Social Upheaval
France’s unexpected 0.1% economic contraction in the third quarter stands as a significant point of concern for the Eurozone’s second-largest economy. This downturn is occurring against a backdrop of intensifying fiscal challenges. The nation is currently facing soaring borrowing costs, a direct consequence of investor apprehension regarding the government’s ongoing political struggle to rein in its persistently high budget deficit and mounting national debt. The French government has been under immense pressure to implement fiscal reforms aimed at reducing public spending and increasing revenue, but these efforts have frequently met with strong political opposition and public resistance, exacerbating investor doubts about the country’s long-term financial stability.
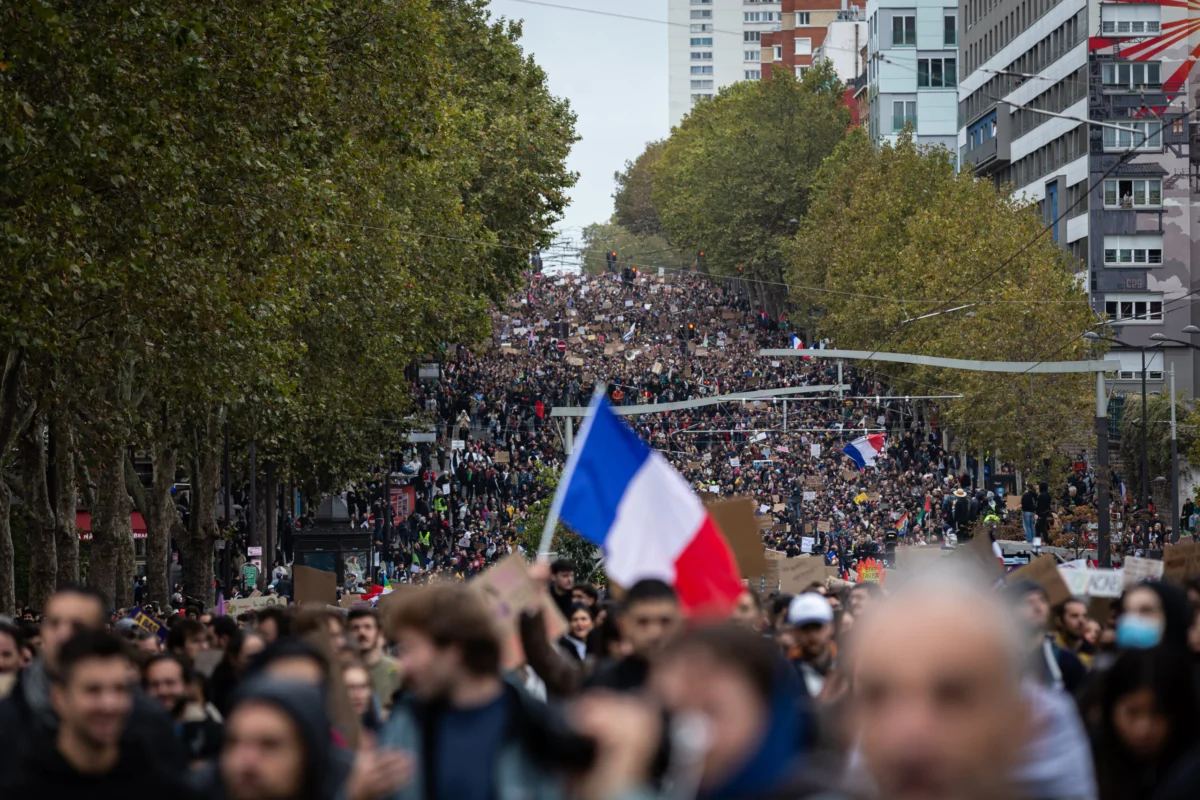
The economic anxieties are inextricably linked to a surge in nationwide unrest. On October 24, 2026, approximately 800,000 people demonstrated across France, with a significant contingent of 250,000 participating in Paris, according to estimates from the Confédération Générale du Travail (CGT), one of France’s largest trade unions. The Parisian march, initially planned for a different route, saw a last-minute alteration by the Police Headquarters, commencing from the Porte d’Italie and proceeding towards the Porte de Vincennes, a change that itself sparked minor logistical challenges and added to the palpable tension. These protests, fueled by rising costs of living, concerns over purchasing power, and dissatisfaction with government policies, have at times escalated beyond peaceful demonstrations, resulting in violent clashes with law enforcement and costly rioting across various cities throughout October, leading to significant property damage and disruptions.
Timeline of Key Events and Economic Indicators (October 2026)
- Early October: Tens of thousands protest across Spain over housing crisis and cost pressures, leading to a snap election being called for the following month.
- October 21: Reports emerge detailing France’s soaring borrowing costs as investors react to political struggles over debt.
- October 23: Concerns escalate over France’s national debt and budget deficit, raising fears of potential Eurozone contagion.
- October 24: Mass protests unfold across France, with 800,000 demonstrators nationwide, including 250,000 in Paris, according to the CGT. The Parisian march route is altered by police.
- October 29/30 (Thursday): The European Central Bank (ECB) votes to hold interest rates steady, citing that the shock from higher energy prices is not yet feeding into broader second-round effects in the economy.
- October 30 (Friday): Eurostat announces the Eurozone’s economic expansion slowed to 0.4% in Q3, while France’s economy unexpectedly contracted by 0.1% during the same period.
- Throughout October: Growing nationwide unrest in France, occasionally escalating into violent and costly rioting, is reported, driven by cost of living and other socio-economic issues.
The European Central Bank’s Cautious Stance
In its latest policy meeting held on Thursday, the European Central Bank (ECB) opted to maintain interest rates at their current levels. This decision was underpinned by the assessment that, despite elevated energy prices, there was no clear evidence of these price shocks translating into broader "second-round effects" that would embed inflation more deeply into the wider economy through wage-price spirals. The ECB’s primary mandate is to maintain price stability, and its Governing Council has been meticulously balancing the need to curb inflation with the risks of stifling economic growth.
However, the central bank also acknowledged that "downside risks to growth had increased," reflecting concerns over geopolitical instability, persistent inflation, and the uneven economic performance across the Eurozone. While the immediate decision was to hold rates, many analysts continue to project the possibility of one more rate hike in December. This forward guidance suggests that the ECB remains vigilant and prepared to act if inflationary pressures prove more persistent than anticipated, especially as energy costs continue to remain elevated amidst the Middle East crisis. The cautious approach signals a desire to avoid prematurely declaring victory over inflation while simultaneously being mindful of the fragile growth trajectory.
Broader Implications and Structural Challenges
Economists are dissecting the Eurozone’s performance with a mixture of relief and apprehension. Joe Nellis, head of economic research at accountancy MHA, commented that the Euro area is "showing unexpected resilience against a backdrop of considerable economic and geopolitical uncertainty." This resilience, however, may be deceptive, potentially masking deeply entrenched structural challenges that have plagued the continent for years. Nellis cautioned that these include weak productivity growth, insufficient investment expenditure in critical sectors, demographic pressures stemming from an aging population and declining birth rates, and a diminishing industrial competitiveness in the face of global rivals and high energy costs.
The outlook for 2027 appears particularly complicated by the prospect of further inflationary pressures. The unresolved Middle East crisis poses a significant threat, as any further escalation or prolonged instability could lead to a sustained surge in energy and transportation costs. Such an outcome would inevitably place additional strain on the cost of living and household finances across Europe, at a time when consumer confidence remains generally weak. This confluence of factors could stifle economic recovery, exacerbate social tensions, and present formidable challenges for policymakers attempting to navigate a path toward sustainable growth and stability.
The contrasting fortunes within the Eurozone, exemplified by Spain’s relative strength and France’s contraction amidst widespread protests, highlight the complex and multi-faceted challenges facing the bloc. While the Eurozone collectively demonstrated a degree of resilience, the underlying vulnerabilities and disparities among its member states suggest that the path to a robust and equitable recovery remains fraught with obstacles, requiring concerted policy efforts and a careful balancing act between fiscal discipline, social cohesion, and sustainable economic growth. The coming months will be critical in determining whether the Eurozone can overcome these structural headwinds and maintain its trajectory towards a more stable future.