Gilang Muhammad
Wall Street’s latest projections for the Federal Reserve’s preferred inflation gauge, the Personal Consumption Expenditures (PCE) price index, now anticipate an acceleration beyond the levels that recently prompted the central bank to tighten monetary policy. This development places increased scrutiny on the Federal Open Market Committee (FOMC) as it navigates its dual mandate of achieving maximum employment and maintaining price stability amidst persistent inflationary pressures. The renewed concerns stem from a confluence of factors, including recent hotter-than-expected economic data, ongoing geopolitical tensions, and structural shifts in global supply chains that have collectively fueled a sustained period of elevated prices.
The Alarming Producer Price Index Signals Broadening Inflation
The catalyst for these revised inflation expectations was the release of the September Producer Price Index (PPI) data, which painted a concerning picture of inflationary pressures building at the wholesale level. Published on Thursday, the PPI registered a significant monthly gain of 1.3%, far exceeding economists’ consensus estimate of 0.6% and marking the largest monthly increase since March 2022. This substantial jump propelled the year-over-year increase in the PPI to 6.3%, the most considerable rise since December 2022, underscoring the broad-based nature of the price increases.
A primary driver of this surge was a dramatic 20% escalation in gasoline prices. However, the inflationary impulse was not confined solely to volatile energy components. When excluding the more erratic categories of food, energy, and trade services, the "core" PPI still demonstrated a robust 0.5% increase. This underlying strength suggests that inflationary forces are deeply embedded across various sectors of the economy, rather than being merely a transient phenomenon driven by specific commodity fluctuations. Such widespread price increases at the producer level inevitably translate into higher costs for consumers, further complicating the Fed’s efforts to rein in inflation.
PCE: The Fed’s Preferred Gauge and Its Troubling Outlook
While the Consumer Price Index (CPI) garners significant public attention, the Federal Reserve primarily monitors the Personal Consumption Expenditures (PCE) price index as its preferred measure of inflation. The Fed favors the PCE because it is believed to more accurately reflect how Americans actually spend their money, dynamically adjusting its weightings as consumer spending patterns evolve. This characteristic makes it a more comprehensive and representative indicator of inflationary trends impacting households.
Against this backdrop, seven prominent Wall Street estimates compiled by CNBC now forecast that the core PCE inflation for September, slated for publication later this month, will increase by 0.32%. This represents an uptick from the 0.25% rise observed in August, signaling a worrying acceleration. Should this forecast materialize, it would push the year-over-year core inflation rate to 3.1%, up from 3.01% in August. This upward trajectory contrasts sharply with the Fed’s long-term target of 2% inflation, suggesting that the central bank’s battle against rising prices is far from over. Economist estimates for the September core PCE varied slightly, with Barclays projecting a high of 0.35% and Oxford Economics forecasting a low of 0.29%, but the overall consensus points to an uncomfortable upward trend.
Kathy Bostjancic, chief economist at Nationwide, articulated the growing concern, stating, "We see real risks the Fed will deliver another rate hike in two weeks’ time even as recent Fedspeak tempered expectations for back-to-back increases." This sentiment highlights the delicate balancing act the Fed faces: managing market expectations while responding decisively to inflationary data.
The Federal Reserve’s Persistent Dilemma: Balancing Growth and Price Stability
The Federal Reserve operates under a dual mandate: to foster maximum employment and maintain price stability. The current inflationary environment poses a significant challenge to the latter, forcing the central bank to consider further aggressive monetary policy actions that could, in turn, impact the former. The Fed’s target inflation rate of 2% is considered optimal for a healthy, growing economy, providing sufficient buffer against deflation while avoiding the corrosive effects of excessively high prices. However, both headline and core PCE inflation have consistently remained above this target since 2021, a trend that has prompted the current cycle of interest rate hikes.
Since the initial signs of persistent inflation emerged, the FOMC has embarked on an aggressive campaign of monetary tightening, raising the federal funds rate from near-zero levels. This has been a departure from the accommodative policies pursued for over a decade, designed to stimulate economic growth in the wake of financial crises and global pandemics. The current debate within the Fed reflects the inherent complexities of this tightening cycle. While some officials have advocated for a more cautious approach, arguing that the economy does not need to rush into further rate increases, a prevailing sentiment suggests that additional hikes are indeed necessary to firmly anchor inflation expectations and restore price stability.
Fed Chairman Kevin Warsh has previously outlined a critical litmus test for pausing rate hikes: a clear and demonstrable confidence that inflation will return to the Fed’s 2% target in a timely manner. The current data, however, appears to fall short of this criterion, intensifying the internal discussions among policymakers. The market’s interpretation of these signals is dynamic; Fed futures on Thursday indicated a mere 29% probability of a rate hike at the upcoming FOMC meeting at the end of this month. Yet, the probability of at least one hike by December soared to 91%, reflecting the market’s conviction that the cumulative weight of inflationary pressures will eventually compel the Fed to act further.
A Chronicle of Rising Prices: Triggers and Trajectories
The current inflationary environment is not an isolated event but rather the culmination of several interconnected economic and geopolitical developments stretching back several years. Prior to 2021, the global economy, including the United States, experienced a prolonged period of relatively low and stable inflation, often struggling to even meet the 2% target. This era was characterized by globalization, technological advancements, and ample labor supply, all contributing to subdued price pressures.
However, the landscape began to shift dramatically around 2021. The unprecedented fiscal and monetary stimulus deployed to combat the economic fallout of the global pandemic, combined with a swift rebound in consumer demand, overwhelmed global supply chains that were simultaneously grappling with lockdowns, labor shortages, and logistical bottlenecks. This classic demand-supply imbalance laid the groundwork for the initial surge in inflation.
Further complicating this trajectory was the imposition of new tariffs in April 2025. While the specifics of these tariffs are multifaceted, they generally aimed at specific imported goods, often in response to trade imbalances or geopolitical considerations. Such tariffs, by increasing the cost of imported raw materials and finished products, inevitably filtered through the domestic economy, contributing to higher input costs for businesses and subsequently higher prices for consumers. This policy move added a layer of cost-push inflation, exacerbating existing pressures.
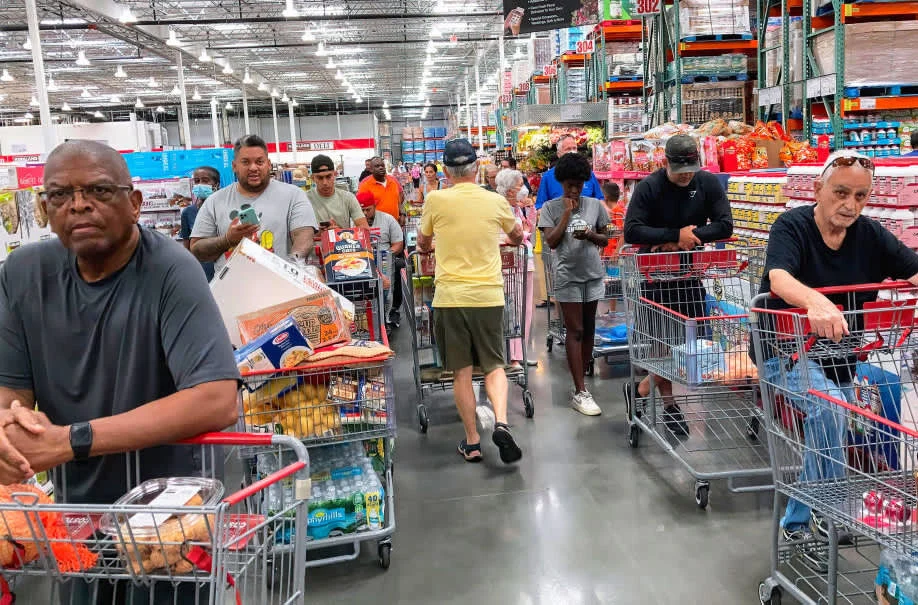
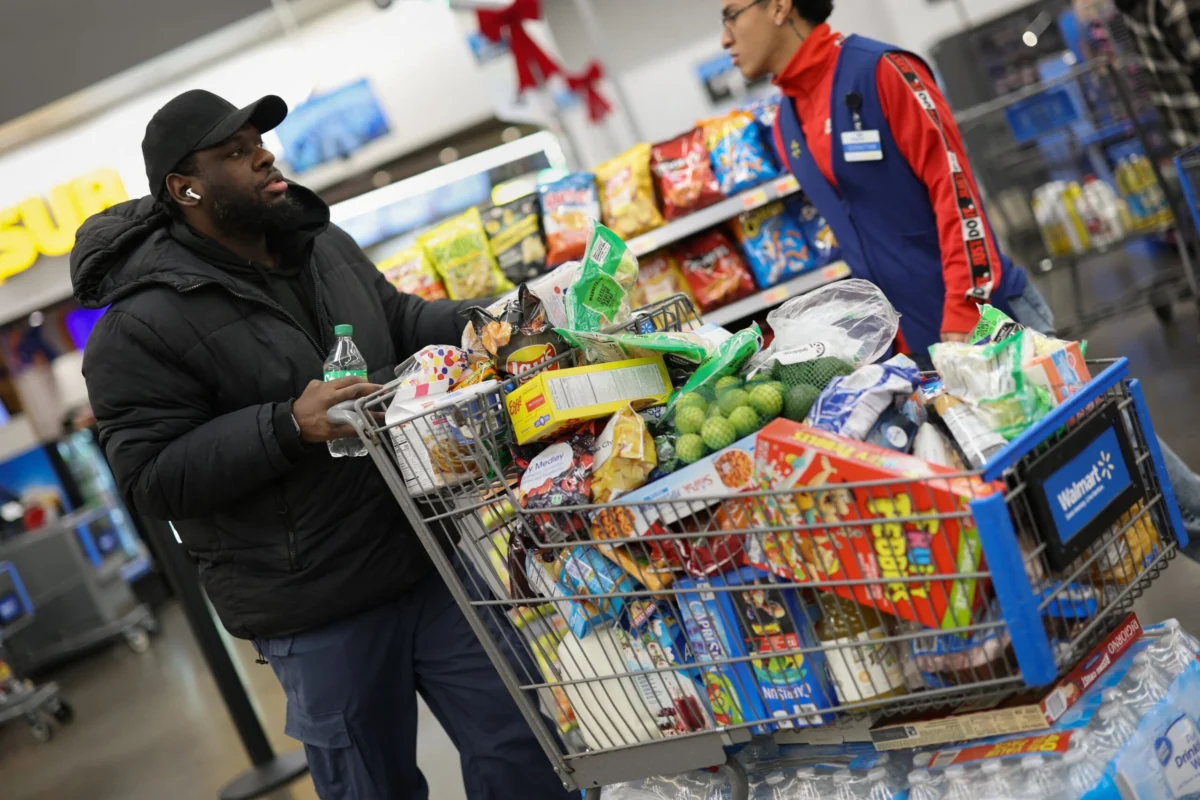
The beginning of the Iran war in early 2026 marked another significant inflection point. Geopolitical conflicts, particularly in energy-rich regions, inherently introduce immense volatility into global commodity markets. The conflict immediately disrupted established trade routes, tightened oil and gas supplies, and injected a significant risk premium into energy prices. Given energy’s foundational role in nearly all economic activities, this shock reverberated across industries, from transportation and manufacturing to food production, significantly contributing to the broad-based inflation observed in the PPI data. The image of a customer with a loaded shopping cart at a Walmart Supercenter in North Bergen, New Jersey, in November 2025, serves as a poignant reminder of the robust consumer demand that characterized the economy leading up to these more acute inflationary pressures in 2026.
Voices from Wall Street: Consensus on the Need for Action
Economists across Wall Street are increasingly unified in their assessment of the inflation outlook, with many advocating for continued vigilance from the Federal Reserve. Alex Pelle, senior U.S. economist at Mizuho Securities, provided a stark assessment: "The picture is not benign with inflation elevated and intensifying. On the economic data alone, there is little reason for the Fed to hesitate to continue moving the policy rate higher." This perspective reflects a growing consensus that the recent data provides ample justification for further monetary tightening, irrespective of concerns about economic growth.
The market’s reaction to these economic signals and the Fed’s potential responses is critical. Higher inflation forecasts, particularly for core PCE, often lead to an upward adjustment in bond yields as investors demand greater compensation for the erosion of purchasing power. This, in turn, can affect borrowing costs for businesses and consumers, from corporate bonds to mortgage rates. Equity markets, meanwhile, tend to react with increased volatility, balancing the impact of rising rates on corporate profitability against the potential for continued economic resilience. The confluence of a strong labor market and persistent inflation presents a challenging environment for investors seeking clarity on future economic performance.
Broader Economic Implications: Households, Businesses, and the Specter of Slowdown
The implications of sustained, elevated inflation and the Federal Reserve’s response extend far beyond financial markets. For average households, persistent inflation erodes purchasing power, making everyday necessities more expensive and squeezing household budgets. Wages, even if rising, often struggle to keep pace with the accelerating cost of living, leading to a decline in real incomes. This can particularly impact lower-income households, who spend a larger proportion of their earnings on essentials like food and energy. Moreover, rising interest rates translate into higher costs for borrowing, affecting everything from mortgage rates and auto loans to credit card debt, further straining consumer finances.
Businesses, too, face significant challenges. Higher input costs, as reflected in the PPI, compress profit margins, forcing companies to either absorb the costs, which can dampen investment and job creation, or pass them on to consumers, thereby perpetuating the inflationary cycle. Increased borrowing costs also make it more expensive for businesses to expand, innovate, or manage existing debt, potentially slowing overall economic growth.
The Fed’s aggressive stance in combating inflation, while necessary for long-term stability, carries the inherent risk of tipping the economy into a recession. The delicate art of a "soft landing" – bringing inflation down without causing a significant economic downturn – is notoriously difficult. The current environment, marked by robust employment but also persistent price pressures, makes the Fed’s task particularly challenging.
Global Reverberations: The Dollar’s Strength and International Spillovers
The Federal Reserve’s monetary policy decisions do not occur in a vacuum; they have profound implications for the global economy. When the U.S. Fed raises interest rates, it typically strengthens the U.S. dollar as international investors seek higher yields on dollar-denominated assets. A stronger dollar makes U.S. exports more expensive and imports cheaper. More significantly, it can create financial strain for countries and companies that have borrowed in dollars, as their debt becomes more expensive to service in their local currencies.
Emerging markets, in particular, often bear the brunt of U.S. monetary tightening. Capital tends to flow out of these economies and into the perceived safety and higher returns of U.S. assets, potentially leading to currency depreciation, higher domestic interest rates, and financial instability in those nations. The interconnectedness of global supply chains also means that inflationary pressures originating in one major economy can quickly spread, further complicating the efforts of central banks worldwide to manage their own domestic price stability.
Looking Ahead: The Path for Monetary Policy
As the Federal Reserve approaches its next policy meetings, the trajectory of inflation, particularly the PCE, will be the paramount concern. Should the September core PCE data confirm the Wall Street estimates of an accelerating trend, the pressure on the FOMC to deliver another rate hike, possibly sooner rather than later, will intensify significantly. The central bank will need to carefully weigh the risk of overtightening, which could lead to an economic slowdown, against the risk of undertightening, which could allow inflation to become entrenched, necessitating even more aggressive and potentially disruptive measures down the line.
The coming months will be critical in determining whether the current inflationary wave begins to recede or if it proves more stubborn than anticipated. Factors such as the evolution of geopolitical conflicts, particularly the Iran war, the stability of global energy markets, the resilience of supply chains, and the underlying strength of consumer demand will all play pivotal roles. For now, the consensus from Wall Street and the signals from recent economic data point towards a continued hawkish stance from the Federal Reserve, underscoring the ongoing challenges in the pursuit of price stability.