Gilang Muhammad
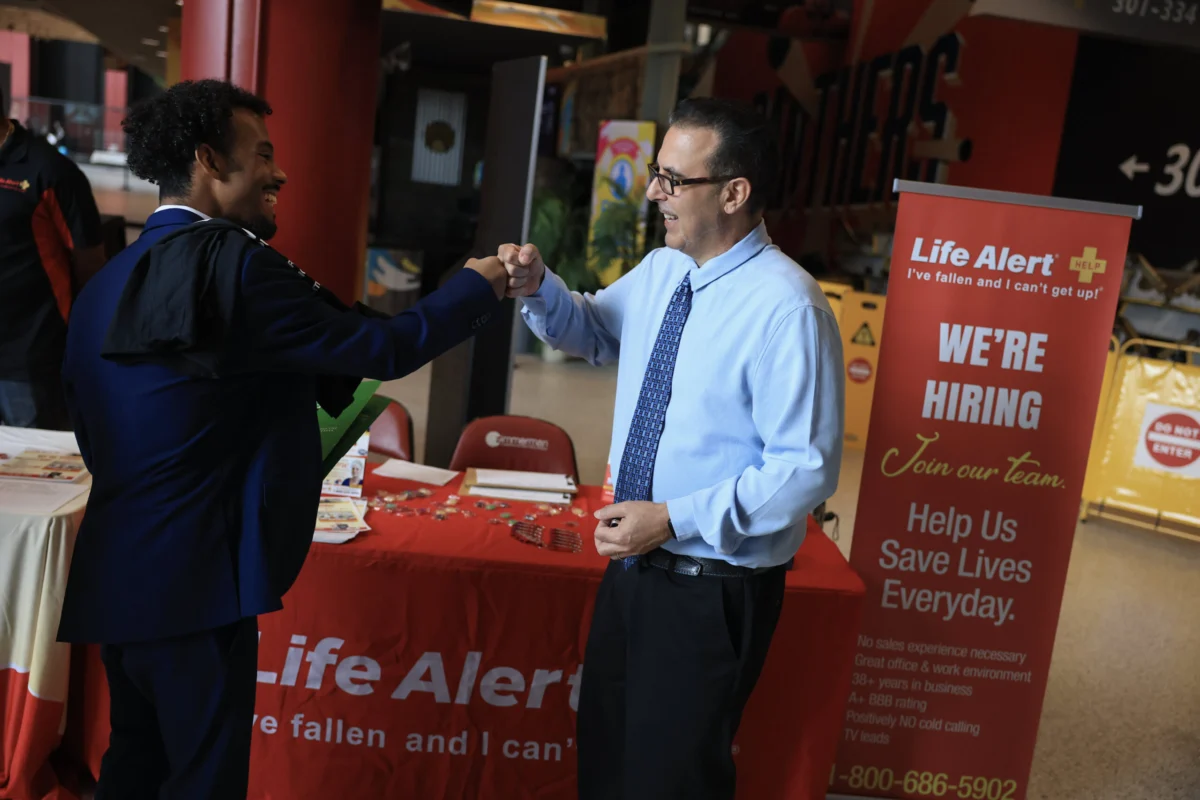
The latest jobs report for October has delivered a robust affirmation of the American economy’s resilience, significantly surpassing expert forecasts and providing a compelling counter-narrative to prevailing fears of an impending slowdown. The Bureau of Labor Statistics (BLS) announced Friday that nonfarm payrolls surged by a seasonally adjusted 165,000 positions for the month, dramatically outperforming the Dow Jones consensus estimate of a modest 59,000. This unexpected vigor was complemented by a downward tick in the national unemployment rate, which reached 4.1%, marginally lower than the 4.2% anticipated by analysts. The confluence of strong job creation and declining joblessness underscores a labor market that continues to defy gravity in the face of persistent inflation and restrictive monetary policy.
Key Figures and Surpassing Expectations
The headline figures from the October jobs report paint a picture of undeniable strength. The addition of 165,000 nonfarm payrolls marks a substantial acceleration from the more subdued figures observed in recent months and represents a clear deviation from predictions. Economists had largely braced for a cooler labor market, anticipating that the cumulative impact of aggressive interest rate hikes by the Federal Reserve and broader global economic uncertainties would begin to manifest in slower hiring. The actual outcome suggests a more deeply entrenched demand for labor than previously assumed.
Beyond the monthly gains, the report also brought significant upward revisions to prior months’ data, further bolstering the narrative of a stronger underlying trend. The August nonfarm payroll figure was revised upwards by a substantial 53,000, settling at a more robust 186,000. Similarly, September’s initial count was adjusted higher by 31,000, bringing it to 60,000. These revisions are particularly noteworthy as they indicate that the labor market’s strength in previous periods was underestimated, suggesting a more consistent and powerful growth trajectory leading into October. Such revisions often provide economists with a clearer, albeit delayed, understanding of economic momentum, and in this instance, they point to sustained expansion rather than a fleeting surge.
While the primary unemployment rate (U-3) showed improvement, a more encompassing measure, U-6, which includes discouraged workers and those holding part-time jobs for economic reasons, did see a slight increase. This broader measure rose by 0.3 percentage points to 7.9% in October, coinciding with an expansion of 421,000 in the civilian labor force. This nuance suggests that while the core unemployment rate improved, more individuals either entered the workforce and found part-time roles or were categorized as underemployed, highlighting a dynamic labor supply responding to opportunities, albeit not always full-time.
Wage Growth and Workweek Stability
The report also delivered notable insights into wage dynamics, a critical factor for both consumer purchasing power and inflationary pressures. Average hourly earnings increased by 0.4% on a monthly basis, exceeding the forecast of 0.3%. Annually, wages rose by 3.1%, surpassing the estimated 2.9%. This acceleration in wage growth, while beneficial for workers, will undoubtedly capture the attention of Federal Reserve policymakers who monitor wage inflation closely as a potential driver of broader price increases. The average workweek remained unchanged at 34.4 hours, indicating that businesses are largely maintaining their existing operational structures and staffing levels rather than significantly extending employee hours or rapidly increasing their workforce. This stability in hours suggests a balanced approach by employers, neither cutting back nor dramatically expanding capacity through increased overtime.
A Broad-Based Recovery: Shifting Sectoral Dynamics
A particularly encouraging aspect of the October report was the breadth of job growth across various sectors, signaling a more diversified economic expansion compared to previous periods. This contrasts sharply with earlier trends where job creation was heavily concentrated in a few specific industries, most notably healthcare.
Leading the charge in October was the professional and business services sector, which added a robust 70,000 jobs. This category, encompassing a wide array of roles from administrative support to technical consulting, is often seen as a bellwether for business confidence and investment. Its strong performance suggests that companies are continuing to invest in their operations, expand their service offerings, and seek external expertise, indicating optimism about future growth.
Healthcare, while no longer singularly dominating job gains, continued its consistent expansion, adding 42,000 positions. This sector’s steady growth is a long-term trend driven by an aging population and ongoing demand for medical services, proving to be a reliable engine of employment.
Other sectors also contributed significantly to the overall strength. Transportation and warehousing saw an increase of 25,000 jobs, reflecting sustained consumer demand for goods and the logistical infrastructure required to move them. Manufacturing, often considered a cyclical industry sensitive to economic fluctuations, added a respectable 19,000 jobs, indicating resilience in the industrial sector. This broad-based distribution of job gains across diverse industries underscores the underlying strength and adaptability of the U.S. economy.
Expert Reactions: Relief and Reassessment
Economists and strategists quickly weighed in on the report, largely expressing surprise and relief at the unexpected strength. Dan North, senior economist at Allianz Trade North America, characterized the report unequivocally, stating, "You have to look pretty hard to find something to dislike in there. It’s a really, really good report, and all around I think you’d say it’s stronger than expected and the best one in a while, and it kind of fits with what I call the stable but perhaps unexciting labor market." North’s assessment highlights the consistent, albeit not explosive, growth that underpins current economic conditions.
Seema Shah, chief global strategist at Principal Asset Management, echoed this sentiment, emphasizing the report’s role in dispelling economic anxieties. "Today’s jobs report is a strong rebuttal to fears that the economy is heading into a meaningful slowdown," Shah commented. She further noted, "Payrolls growth surprised firmly to the upside, unemployment fell back to 4.1%, and job creation remains broad-based, pointing to an economy that is still absorbing labor comfortably rather than one beginning to buckle under tighter financial conditions." This perspective is crucial as it suggests that the economy is successfully navigating the challenges posed by tighter financial conditions without experiencing a significant contraction in employment.
Heather Long, chief economist at Navy Federal Credit Union, provided a valuable comparative perspective, highlighting the significant improvement over previous periods. "The overall picture is a labor market that is on much better footing than a year ago," Long observed. She contrasted the current broad-based growth with a past period, noting that "In [a prior year], the economy added barely 10,000 jobs a month and basically all were in healthcare. … There’s a much more broad based range of opportunities." This comparison underscores a qualitative improvement in the labor market, offering more diverse career paths and greater economic mobility for workers.
Background Context: A Nation Grappling with Economic Crosscurrents
The October jobs report lands amidst a complex and often contradictory economic landscape. For months, the specter of inflation has loomed large, pushing the Federal Reserve to embark on its most aggressive interest rate hiking cycle in decades. Since March 2022, the central bank has steadily increased the federal funds rate, aiming to cool demand and bring inflation down from its multi-decade highs. These rate hikes have filtered through the economy, raising borrowing costs for consumers and businesses, and leading many to anticipate a slowdown, or even a recession.

Simultaneously, the U.S. economy has demonstrated remarkable resilience. Consumer spending has remained robust, corporate earnings have largely held up, and GDP growth has shown signs of acceleration. However, this strength has been accompanied by persistent inflationary pressures, with the Consumer Price Index (CPI) remaining stubbornly above the Fed’s 2% target. The debate between a "soft landing"—where inflation cools without a significant economic downturn—and a harder recessionary outcome has been central to economic discourse.
Politically, the economy, and particularly inflation, has been at the forefront of national conversations. The report comes just days after a pivotal election where affordability issues and economic management were central themes. The strong jobs data could offer a favorable narrative for the incumbent administration, suggesting effective economic stewardship and a resilient recovery. Conversely, concerns about ongoing wage inflation could still fuel opposition arguments about the rising cost of living.
Implications for Monetary Policy and the Federal Reserve
For the Federal Reserve, the October jobs report presents a complex dilemma as central bankers weigh their next steps on interest rates. The strong employment and wage growth data, while positive for workers, could be interpreted as a sign that the economy remains overheated, potentially fueling further inflation. This increases the pressure on the Fed to continue its fight against rising prices.
Traders in the futures market immediately reacted to the report, significantly increasing the probability of another quarter percentage point interest rate hike when the Federal Open Market Committee (FOMC) meets in December. According to the CME Group’s FedWatch tool, the odds of such a hike rose to 76.8% following the release of the data. This indicates that market participants now largely expect the central bank to maintain its hawkish stance, prioritizing price stability over concerns about economic deceleration.
However, the report also offers a nuanced view. While the immediate probability of a December hike surged, the indicator pointed to only one more increase after that, with the odds of further hikes in 2027 (likely referring to subsequent years or 2024-2025) having fallen somewhat in recent days. This suggests that while the Fed might tighten policy once more, the market perceives the end of the hiking cycle to be near, perhaps due to other factors such as the recent sell-off in tech stocks or broader global economic uncertainties. The Fed’s dual mandate—to promote maximum employment and stable prices—is put to the test by such a report. While the employment side of the mandate appears robust, the implications for price stability remain a critical concern.
Market Reaction and Labor Force Dynamics
The immediate market reaction to the jobs report was somewhat mixed, reflecting the complex signals within the data. Stock market futures showed a muted and varied picture heading into the open, suggesting that investors were still processing the implications. This could be due to the report’s dual nature: strong economic data is generally positive for corporate earnings, but it also increases the likelihood of further interest rate hikes, which can dampen equity valuations.
Conversely, Treasury yields saw an increase across the board. Higher bond yields typically reflect expectations of stronger economic growth and higher inflation, which can prompt the Fed to maintain a restrictive monetary policy. This reaction in the bond market aligns with the increased probability of a December rate hike, indicating that fixed-income investors are pricing in a tighter monetary environment.
On the labor supply side, the labor force participation rate, which measures the share of the workforce either looking for a job or already working, edged higher to 61.9%. This is a crucial metric, as the labor force had been shrinking in previous periods due to demographic changes and reductions in immigration. The expansion of the labor force by 421,000 in October, as reported by the BLS, suggests that more individuals are being drawn back into the job market, potentially easing some of the tightness in labor supply.
The household report, which is used to calculate the unemployment rate and provides a complementary view to the establishment survey for payrolls, also showed positive trends. It indicated that 463,000 more people were at work in October, reinforcing the overall message of a strengthening labor market.
A Lingering Concern: Long-Term Unemployment
Despite the overwhelmingly positive aspects of the report, one particular area presented a notable concern: long-term unemployment. The average duration of unemployment jumped sharply to 27.1 weeks, an increase of 2.3 weeks from the prior month and the highest level since September 2021. Furthermore, the number of individuals unemployed for more than 27 weeks increased significantly to 1.96 million, marking the highest count since December 2021.
This rise in long-term unemployment, even amidst overall job growth and a declining headline unemployment rate, indicates potential structural challenges within the labor market. It suggests that while new jobs are being created and many are finding employment, a segment of the workforce continues to face persistent difficulties in securing work. This could be due to skills mismatches, geographic immobility, or other barriers that prevent these individuals from re-entering the workforce, even in a strong hiring environment. The Fed and policymakers will need to monitor this trend closely, as prolonged unemployment can have significant social and economic consequences, including erosion of skills and reduced lifetime earnings potential.
Broader Economic Outlook and Conclusion
The October jobs report serves as a powerful testament to the underlying dynamism and resilience of the U.S. economy. Its strength significantly complicates the narrative of an economy on the brink of a severe downturn, instead bolstering the case for a potential "soft landing." The broad-based nature of job growth, coupled with positive revisions to prior data, suggests that economic momentum is more robust than previously understood.
However, the report also intensifies the challenge for the Federal Reserve. The ongoing strength in employment and wages, while beneficial for American households, keeps inflationary pressures on the front burner. The balancing act between fostering full employment and achieving price stability remains delicate, and the strong jobs data will likely encourage the Fed to remain vigilant, potentially leading to further monetary tightening in the near term.
Looking ahead, the U.S. economy appears to be on a much firmer footing than many had anticipated. While concerns about inflation and specific pockets of the labor market, such as long-term unemployment, persist, the overall picture is one of continued growth and adaptability. The coming months will be crucial in determining whether this surprising strength can endure without reigniting inflationary spirals, ultimately shaping the trajectory of monetary policy and the broader economic landscape into the new year.