Gilang Muhammad
The United States economy is bracing for another month of subdued job growth, with economists anticipating a modest increase in nonfarm payrolls for October 2026. Projections suggest a gain of just 59,000 jobs, a slight improvement from the 29,000 jobs reported in September, yet still indicative of a continuing pattern of sparse expansion in the labor market. This subdued hiring environment unfolds against a backdrop of employers showing reluctance to significantly expand their workforces, even as they largely refrain from widespread layoffs. The situation is further complicated by a shrinking labor force and the growing challenge of long-term unemployment, painting a nuanced picture of the nation’s economic health.
Despite the meager job creation figures, the unemployment rate is widely expected to hold steady at a very low 4.2%. This seemingly contradictory stability is largely attributed to a stagnant labor force, which naturally reduces the number of new jobs required to maintain a low jobless rate. This demographic shift is profoundly altering how economists evaluate the vitality of the labor market. Nicole Bachaud, a labor economist at ZipRecruiter, articulated this evolving dynamic, stating, "Long-term, we’re not going to need as many jobs added to the economy to have stable employment because we have fewer people who are available to work." She elaborated on the underlying causes: "An aging workforce is pushing a lot of people into retirement. We have had decades of low birth rates, meaning we don’t have a lot of people who are coming in to replace those retiring workers. And immigration is now down pretty significantly, which is reducing some of that prime-age employment." This confluence of factors creates a unique economic environment where traditional metrics for assessing labor market strength may no longer fully capture the underlying realities.
The Shifting Landscape of Labor: Demographics and Workforce Participation
The demographic headwinds facing the U.S. labor market are significant and structural. The baby boomer generation, a massive cohort that swelled the ranks of the workforce for decades, is now steadily exiting into retirement. According to recent demographic analyses, an average of 10,000 baby boomers reach retirement age daily, a trend that is projected to continue for several more years. This exodus is not being adequately offset by younger generations. Low birth rates since the 1990s mean fewer individuals are entering the labor pool, creating a demographic deficit. Furthermore, shifts in immigration policy and global events have led to a notable reduction in net immigration, historically a vital source of new workers, particularly in prime working-age demographics.
These factors have tangible effects on labor force participation. The share of the population either working or actively seeking employment, the labor force participation rate, has seen a marked pullback. It currently stands at 61.8%, representing a 0.8 percentage point slide over the past year. This decline, while partly a reflection of structural factors like an aging population, also indicates that a significant segment of potential workers remains outside the active labor market. This trend is a stark departure from the pre-pandemic era, when the participation rate hovered closer to 63%, and even further from its peak of over 67% in the late 1990s. The implications are far-reaching, potentially constraining economic growth and placing upward pressure on wages in specific sectors where labor supply is particularly tight.
Behind the Numbers: A Closer Look at Key Indicators
While overall job growth appears sluggish, a deeper dive into other labor market indicators reveals a complex picture of both underlying strength and persistent challenges. The U.S. Bureau of Labor Statistics (BLS) is scheduled to release the comprehensive October nonfarm payrolls report on Friday, at 8:30 a.m. ET, which will provide definitive data to confirm or adjust these preliminary assessments.
-
Low Layoffs and High Quits: One of the strongest signs of employer confidence and worker mobility remains the low level of layoffs. Initial jobless claims recently slid to 189,000, the lowest since July 2026, and hovering around the lowest levels recorded since 1969. This indicates that employers, while cautious about hiring, are largely retaining their existing staff, suggesting a degree of stability in current employment relationships. Concurrently, the number of workers quitting their jobs, often seen as a proxy for confidence in the ability to find new or better work, hit 3.36 million in September, reaching its highest level in a year and a half. This "Great Resignation" or "Great Reshuffle" trend, while perhaps less pronounced than its peak during the pandemic recovery, continues to signal that many workers perceive opportunities elsewhere, despite the overall slowdown in hiring.
-
Job Openings Rebound: Another positive sign emerged with a significant pickup in job openings, which increased by 333,000 in September. This rebound suggests that demand for labor, while not translating into massive hiring sprees, is still present. It might reflect companies struggling to fill specific roles or a cautious expansion in certain sectors. The discrepancy between rising job openings and slow hiring could point to skill mismatches, geographical disparities, or employers being more selective in their recruitment processes.
-
The Shadow of Long-Term Unemployment: Despite these pockets of strength, a concerning aspect of the current labor market is the persistent rise in long-term unemployment. The total number of workers unemployed for more than 25 weeks has increased by a substantial 495,000 since January 2025. The average duration of unemployment has also climbed to 24.8 weeks, an increase of 2.8 weeks over the same period, according to BLS data through September. This indicates that for those who do lose their jobs or are new entrants struggling to find work, the path back to employment is becoming increasingly difficult and protracted. Long-term unemployment can lead to skill degradation, reduced earning potential, and significant social and economic costs. Bachaud highlighted this struggle: "For people who are out of work because of the slowdown in turnover, people aren’t vacating their jobs, employers aren’t expanding and adding new jobs. That makes it very difficult to kind of break back in."
Sectoral Nuances and the Productivity Paradox
The aggregate job numbers often mask significant variations across different economic sectors. While specific data for October is pending, trends from earlier in 2026 suggest that growth has been concentrated in areas like healthcare, social assistance, and certain segments of the professional and business services sector. Manufacturing and construction, while showing resilience, have faced headwinds from supply chain issues and interest rate sensitivity. The technology sector, after a period of rapid expansion and subsequent retrenchment in 2024-2025, appears to be stabilizing, with some specialized hiring but generally not contributing to broad-based job growth.

A crucial element in understanding the current labor market is the concept of productivity. Bachaud’s inquiry, "Do we have an economy where we have a lot of productivity but not as many jobs?" points to a potential "productivity paradox" or a new phase of economic development. Advancements in automation, artificial intelligence, and other technologies could be enabling businesses to produce more goods and services with fewer human inputs. If this trend holds, it could explain how the economy continues to grow (as evidenced by GDP figures) even with slower job creation. This shift would necessitate a re-evaluation of what constitutes a "healthy" labor market, potentially shifting focus from raw job numbers to metrics like wage growth, skill development, and the equitable distribution of productivity gains.
Policy Implications and the Federal Reserve’s Stance
Federal Reserve officials generally continue to characterize the labor market as "solid," largely owing to the low unemployment rate and relatively stable wage growth that has, at times, outpaced inflation. However, the slowing pace of job creation and the rise in long-term unemployment present new complexities for monetary policy. The Fed’s dual mandate of maximum employment and price stability means it must carefully balance its actions. If inflation remains a concern, the central bank might be hesitant to signal a pivot towards more accommodative policies, even if job growth is weak, given the tight labor supply implied by low unemployment and high quits. Conversely, a sustained period of anemic job growth combined with rising long-term unemployment could eventually prompt the Fed to consider easing monetary conditions to stimulate hiring.
Government officials, including those at the Department of Labor and economic advisors to the White House, are likely monitoring these trends closely. The persistent challenge of long-term unemployment could spur calls for increased investment in workforce development programs, retraining initiatives, and enhanced support for job seekers. Policies aimed at boosting labor force participation, such as affordable childcare, expanded access to education, and potentially even re-evaluating immigration policies, could gain traction as long-term solutions to the demographic crunch.
Voices from the Field: Economists and Industry Leaders
Beyond ZipRecruiter’s Bachaud, other economists have weighed in on the evolving labor landscape. Dr. Alan Greenspan, a prominent economic analyst, recently noted, "The current labor market defies easy categorization. It’s a testament to the economy’s resilience in retaining workers, but also highlights a structural rigidity in expanding employment." He suggested that businesses are prioritizing efficiency and technology adoption over headcount expansion. Meanwhile, a recent survey by the National Association of Manufacturers indicated that nearly 70% of manufacturing firms continue to struggle with finding qualified workers, despite an overall slowdown in hiring. This points to a persistent skills gap, where available workers do not always possess the specialized skills demanded by modern industries.
Addressing Structural Challenges: Workforce Development and Targeted Initiatives
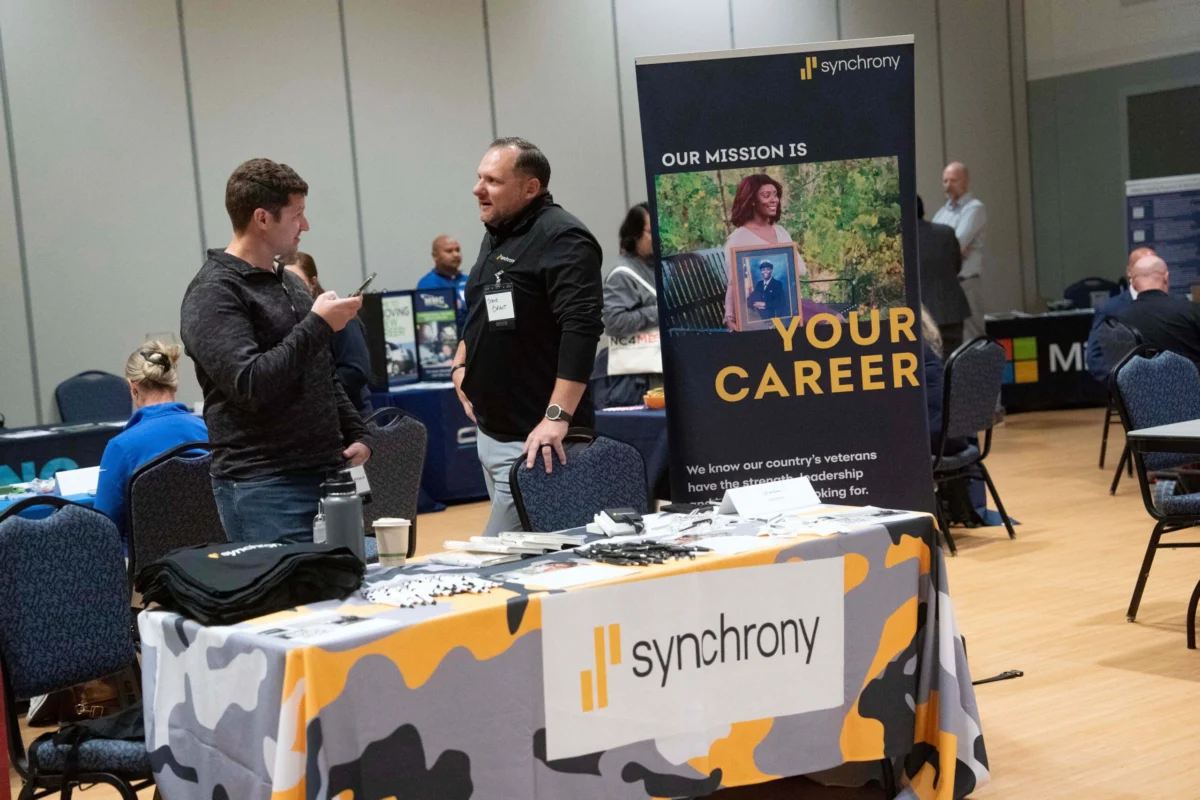
The image accompanying this report, depicting a Synchrony booth at the NC4ME hiring event for military veterans in Wilmington, North Carolina, on October 28, 2026, serves as a poignant illustration of efforts to address specific labor market challenges. NC4ME (North Carolina for Military Employment) is an organization dedicated to connecting North Carolina’s military community with meaningful employment opportunities. Such events are crucial in a labor market characterized by a shrinking overall workforce, as they tap into valuable, often underutilized, talent pools. Military veterans bring a unique skill set—discipline, leadership, technical aptitude—that is highly sought after by employers. However, transitioning from military service to civilian employment can present its own set of hurdles, from translating military experience into civilian résumés to navigating corporate cultures. Initiatives like NC4ME, supported by companies like Synchrony, are vital in bridging these gaps and ensuring that highly capable individuals find suitable employment, thereby contributing to the broader economy and helping to alleviate specific labor shortages. These targeted efforts are becoming increasingly important as the traditional sources of labor supply diminish.
Beyond veterans, similar programs are being developed to support other demographics facing barriers to employment, such as individuals with disabilities, formerly incarcerated individuals, and older workers seeking to re-enter or extend their careers. These efforts underscore a growing recognition that maximizing human capital is essential in an era of demographic constraint.
The Path Forward: Navigating a New Normal
The U.S. labor market is undoubtedly in a period of significant transition. The expectation of meager job growth for October 2026, coupled with a low unemployment rate and structural demographic shifts, signals a "new normal" where the economy may not require the robust job creation seen in past recovery cycles. The focus, as Bachaud suggested, may increasingly shift towards metrics like real wage growth, productivity gains, and the quality of jobs, rather than just the sheer volume of new positions.
The challenge for policymakers, businesses, and workers alike will be to adapt to this evolving landscape. For businesses, this may mean investing more heavily in automation and technology, alongside targeted recruitment and retention strategies for specialized talent. For workers, it emphasizes the importance of lifelong learning, skill adaptation, and resilience in the face of structural change. And for the nation as a whole, it necessitates a thoughtful approach to demographic challenges, ensuring that every available talent pool is effectively integrated into the workforce to sustain economic vitality and inclusive prosperity. The upcoming BLS report will offer another crucial data point in understanding this complex and continually evolving narrative of the American labor market.