Gilang Muhammad
David Zervos, the newly appointed counselor to the U.S. Treasury Secretary, issued a sharp rebuttal on Thursday to the International Monetary Fund (IMF), suggesting the global financial institution should scrutinize its own history of economic predictions before critiquing American fiscal policy. Zervos’s comments were made in the context of a burgeoning debate between U.S. economic officials and international bodies regarding the sustainability of the nation’s rapidly expanding federal debt, which recently surpassed the $40 trillion mark.
"When we see pieces on the IMF, it’s good to remember how messy their forecasts have been in the past," Zervos stated in emailed remarks to CNBC. This pointed observation from the former Wall Street economist comes at a pivotal moment, as global economic leaders gather to discuss pressing financial challenges and national fiscal strategies. His remarks directly addressed concerns raised by IMF Managing Director Kristalina Georgieva, who, during the IMF-World Bank annual meetings in Bangkok on Wednesday, cautioned that even robust U.S. economic growth might prove insufficient to steer the nation’s escalating federal debt onto a sustainable trajectory.
Georgieva’s admonition was, in turn, a response to an earlier assertion by U.S. Treasury Secretary Scott Bessent. In an exclusive interview with CNBC in August, Bessent articulated a confident vision, suggesting that the United States possesses the capacity to "grow our way out" of a rising debt-to-GDP ratio. This declaration followed closely on the heels of the U.S. government debt reaching an unprecedented $40 trillion, a milestone that ignited renewed scrutiny over the nation’s long-term financial health. The exchange underscores a fundamental disagreement on the efficacy of economic growth alone to address profound fiscal imbalances and highlights the differing perspectives between domestic policymakers and international watchdogs.
A Chronology of Fiscal Debate and Rising Debt
The current exchange between the U.S. Treasury and the IMF is the latest chapter in an ongoing, multi-faceted debate about the health of the U.S. economy and its fiscal responsibilities. The timeline of recent events provides critical context:
August 19, 2026: The U.S. government debt officially surpasses the $40 trillion mark for the first time in history. This unprecedented figure, a stark indicator of accumulated federal borrowing, immediately reignites calls for fiscal restraint and triggers widespread concern among economists and financial analysts globally. The milestone highlights decades of deficit spending, exacerbated by recent economic shocks, expansive fiscal stimulus measures, and structural spending commitments.
August 20, 2026: U.S. Treasury Secretary Scott Bessent, in an exclusive interview with CNBC, responds to the growing concerns about the national debt. He posits that sustained U.S. economic dynamism and growth could provide the necessary impetus to reduce the debt-to-GDP ratio, effectively allowing the nation to "grow our way out" of its fiscal challenges. Bessent’s argument typically hinges on the idea that robust economic expansion generates higher tax revenues and, crucially, increases the denominator (GDP) in the debt-to-GDP ratio, thereby improving the perceived sustainability of the debt even if the nominal debt continues to rise.
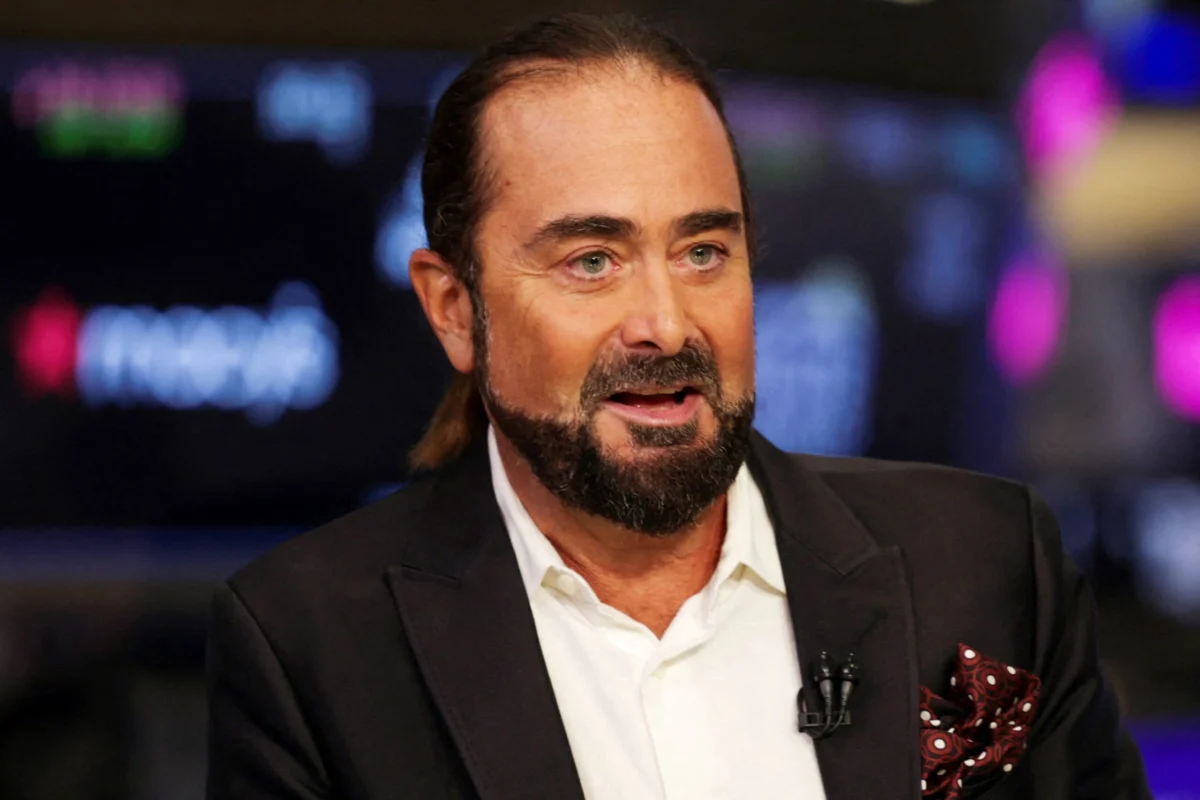
September 3, 2025: David Zervos, Chief Market Strategist of Jefferies LLC, is pictured speaking during an interview with CNBC at the New York Stock Exchange. While this predates his Treasury appointment, it illustrates his prominent role in financial commentary prior to joining the government.
September 28, 2026: David Zervos is formally appointed as a counselor to the Treasury Secretary, bringing his extensive experience from the financial markets directly into the policymaking sphere. His appointment signals a reinforcement of market-oriented perspectives within the Treasury Department.
October 15, 2026 (Wednesday): During the annual IMF-World Bank meetings in Bangkok, IMF Managing Director Kristalina Georgieva addresses the burgeoning U.S. debt issue. She publicly cautions that while strong U.S. economic growth is commendable, it would likely be insufficient on its own to place the mounting federal debt on a sustainable course. Georgieva’s statements reflect the IMF’s institutional mandate for global financial stability and its long-standing advocacy for prudent fiscal management among member states. Her concerns implicitly call for more direct fiscal consolidation measures beyond simply relying on growth.

October 16, 2026 (Thursday): David Zervos, now representing the U.S. Treasury, responds to Georgieva’s critique. He challenges the IMF’s authority on forecasting, pointing to what he describes as the organization’s "messy" track record in past economic predictions. This counter-critique aims to deflect the IMF’s admonition by questioning the credibility of its analytical foundation, suggesting that its historical forecasting inaccuracies diminish its standing as an infallible arbiter of fiscal health.
This sequence of events frames the current debate as a clash of philosophies: the U.S. Treasury’s confidence in growth-driven solutions versus the IMF’s call for more explicit fiscal tightening, all set against the backdrop of record national debt.
The IMF’s Stance and Role: A Global Watchdog’s Perspective
The International Monetary Fund, established in 1944, serves as a central pillar of the international financial system. Its primary mandates include fostering global monetary cooperation, securing financial stability, facilitating international trade, promoting high employment and sustainable economic growth, and reducing poverty around the world. A key function of the IMF is its "surveillance" role, which involves monitoring the economic and financial policies of its 190 member countries, as well as global and regional economic developments. Through this surveillance, the IMF identifies risks and advises on needed policy adjustments.
Kristalina Georgieva’s comments on U.S. fiscal policy fall squarely within this surveillance mandate. Her caution regarding the insufficiency of U.S. growth alone to address debt sustainability reflects a long-held IMF position that while economic expansion is vital, it must be accompanied by responsible fiscal policy to ensure long-term stability. The IMF often advocates for fiscal consolidation – a reduction in government budget deficits and debt accumulation – particularly in advanced economies with large and growing debt burdens. Their concern stems from several factors:
- Crowding Out: High government borrowing can compete with private sector investment for available capital, potentially driving up interest rates and stifling long-term economic growth.
- Inflationary Pressures: Persistent large deficits, especially if monetized, can contribute to inflationary pressures, eroding purchasing power and economic stability.
- Intergenerational Equity: Mounting debt represents a transfer of financial burden to future generations, who will bear the cost of servicing it through higher taxes or reduced public services.
- Global Spillovers: Given the U.S. dollar’s role as the world’s primary reserve currency and the sheer size of the U.S. economy, its fiscal health has significant global implications. Excessive U.S. debt could lead to volatility in global financial markets, impact international interest rates, and potentially weaken confidence in the dollar, affecting trade and investment worldwide.
- Limited Fiscal Space: High debt levels reduce a government’s "fiscal space" – its ability to respond effectively to future economic downturns, crises, or unforeseen national emergencies without exacerbating its financial predicament.
The IMF’s analysis typically incorporates a range of metrics beyond just the nominal debt figure, including the debt-to-GDP ratio, the trajectory of interest payments as a percentage of government revenue, and the demographic pressures on social security and healthcare systems. From the IMF’s vantage point, relying solely on economic growth, while desirable, often overlooks the structural components of debt accumulation and the need for deliberate policy choices to manage expenditures and revenues.
The U.S. Treasury’s Position: The "Grow Our Way Out" Thesis
Treasury Secretary Scott Bessent’s assertion that the U.S. can "grow our way out" of its debt challenges is a position rooted in a particular school of economic thought. This argument is not entirely new; it has been invoked at various points in history, often during periods of significant economic expansion or technological advancement. The core tenets of the "grow our way out" thesis include:
- Denominator Effect: The debt-to-GDP ratio is a key measure of debt sustainability. If nominal GDP grows faster than the nominal debt, the ratio decreases, even if the absolute amount of debt continues to rise. This makes the debt appear more manageable relative to the economy’s capacity to service it.
- Increased Tax Revenue: Robust economic growth typically leads to higher employment, increased corporate profits, and greater consumer spending. These factors translate into higher tax revenues for the government (income tax, corporate tax, sales tax), which can then be used to service or reduce the national debt.
- Productivity Gains and Innovation: Advocates of this approach often point to the unique dynamism of the U.S. economy, its capacity for innovation, and its flexible labor markets. They argue that technological breakthroughs (e.g., in artificial intelligence, biotechnology, green energy) can unlock significant productivity gains, leading to higher sustainable growth rates than typically forecast by more conservative models. Bessent’s confidence likely stems from a belief in the U.S.’s enduring capacity for such innovation.
- Low Interest Rates: Historically, periods of strong economic growth have sometimes been accompanied by relatively low interest rates, which reduce the cost of servicing the national debt, thereby freeing up fiscal resources. However, this dynamic is not guaranteed and can reverse rapidly.
The "grow our way out" strategy implicitly suggests that aggressive fiscal austerity measures might be counterproductive, potentially stifling the very growth needed to address the debt. Instead, the focus shifts to policies that foster innovation, investment, and competitiveness. For the U.S. Treasury, this approach aligns with a broader narrative of American economic exceptionalism and the belief that the nation’s unique economic engine can overcome challenges that might overwhelm other economies. This viewpoint often emphasizes the importance of maintaining strong aggregate demand and supporting sectors that drive future growth.
David Zervos’s Critique: Questioning the IMF’s Forecasting Acumen
David Zervos’s direct challenge to the IMF’s forecasting record injects a crucial element of institutional credibility into the fiscal debate. His characterization of the IMF’s predictions as "messy" taps into a long-standing criticism leveled against major international organizations and even national central banks: the inherent difficulty and frequent inaccuracies of macroeconomic forecasting.
Macroeconomic forecasting is notoriously complex. It involves modeling intricate relationships between countless variables, including consumer behavior, business investment, government policy, global trade, technological advancements, and unforeseen shocks (e.g., pandemics, geopolitical conflicts, natural disasters). Even sophisticated econometric models struggle to capture these dynamics perfectly.
Historical examples of forecasting challenges, which Zervos implicitly references, include:

- Underestimating Crises: The IMF, along with many other institutions, has sometimes been criticized for failing to predict major economic downturns or financial crises with sufficient accuracy or lead time. For instance, critics point to the organization’s initial assessments preceding the 1997 Asian Financial Crisis or the 2008 Global Financial Crisis, suggesting that the severity and scope of these events were not fully anticipated.
- Overly Optimistic Projections: The IMF has occasionally been accused of issuing overly optimistic growth forecasts for certain economies, particularly those undergoing structural reforms, which sometimes fail to materialize as expected. This can lead to misjudgments in policy recommendations.
- Missing Inflationary/Deflationary Shifts: Predicting inflation has proven particularly challenging. For example, after the 2008 crisis, many forecasts, including the IMF’s, anticipated a quicker return to higher inflation than actually occurred in many advanced economies. Conversely, during the post-COVID recovery, the persistence and magnitude of inflation often surprised forecasters.
- Political Economy Factors: Forecasts can sometimes be influenced by political considerations, either to avoid alarming markets or to support a particular policy agenda. This can lead to a bias in projections.
- Data Lags and Quality: Forecasting relies on timely and accurate data, which can be challenging to obtain, especially for developing economies. Even in advanced economies, initial data releases are often revised significantly, adding another layer of complexity.
Zervos, with his background as a market strategist, understands the practical implications of such forecasting inaccuracies. In financial markets, even slight deviations from predicted economic outcomes can trigger significant movements in asset prices. His critique suggests that if the IMF’s predictive models are flawed, then its policy prescriptions, especially those critical of sovereign nations, should be viewed with a degree of skepticism. This strategy aims to diminish the persuasive power of the IMF’s counsel by highlighting its fallibility, thereby strengthening the U.S. Treasury’s position that its own domestic assessments and strategies are valid.
The Nuances of Debt Sustainability: Economic Theory and Practical Challenges
The concept of "debt sustainability" is central to this debate, yet it is far from a simple, universally agreed-upon metric. While a common indicator is the debt-to-GDP ratio, sustainability involves a more complex interplay of factors:
- Interest Rates: The cost of servicing the debt is paramount. Even a high debt-to-GDP ratio can be manageable if interest rates are low and stable. Conversely, rising interest rates can quickly make a seemingly sustainable debt burden unsustainable by significantly increasing annual interest payments. The U.S. currently faces substantial interest rate exposure, with many economists concerned about the rising cost of servicing the $40 trillion debt.
- Primary Balance: This refers to the government’s budget balance excluding interest payments. A sustained primary surplus (revenues exceeding non-interest expenditures) is generally seen as a strong indicator of debt sustainability, as it allows for debt reduction or at least stabilizes the debt-to-GDP ratio.
- Growth Rate vs. Interest Rate (r-g differential): If the economy’s growth rate (g) consistently exceeds the effective interest rate on government debt (r), then the debt-to-GDP ratio can stabilize or even fall without requiring significant primary surpluses. This "r-g" differential is a crucial component of the "grow our way out" argument. However, if r > g, then debt accumulation becomes more challenging to contain without fiscal tightening.
- Demographics: Aging populations in many advanced economies, including the U.S., place increasing pressure on public finances through rising healthcare and pension costs. These structural demographic shifts make it harder to achieve fiscal sustainability without significant reforms.
- Contingent Liabilities: Governments often have off-balance-sheet liabilities, such as guarantees for state-owned enterprises, deposit insurance, or implicit promises for future bailout. These can materialize unexpectedly, adding to the debt burden.
- Credibility and Market Confidence: Ultimately, debt sustainability depends on the confidence of investors that a government will be able and willing to honor its obligations. A loss of confidence can lead to higher borrowing costs and potentially a fiscal crisis, regardless of the numerical debt ratio.
For the U.S., the debate is not just about the absolute $40 trillion figure but its trajectory and the ability to manage it without compromising future economic prosperity. While the U.S. benefits from the dollar’s reserve currency status, which grants it greater flexibility in borrowing, this advantage is not limitless.
U.S. National Debt: A Historical Perspective and Drivers
The U.S. national debt’s journey to $40 trillion is a story spanning decades, marked by wars, economic crises, and shifting fiscal priorities.
- Early History: The U.S. has carried debt since its inception, largely due to wars. Post-Revolutionary War debt, Civil War debt, and World War I debt were significant but eventually managed.
- World War II Peak: The debt-to-GDP ratio peaked dramatically after World War II, exceeding 100% of GDP, as the nation mobilized its economy for the war effort. However, robust post-war economic growth and relatively modest primary surpluses allowed the ratio to decline steadily for decades.
- The Reagan Era and Beyond: Debt began to climb again significantly in the 1980s, driven by tax cuts and increased defense spending. This trend continued with subsequent administrations, punctuated by periods of fiscal tightening (e.g., late 1990s) and expansion.
- 21st Century Accelerations:
- Tax Cuts and Wars (Early 2000s): The Bush administration’s tax cuts and military engagements in Afghanistan and Iraq contributed to rising deficits.
- Global Financial Crisis (2008-2009): The financial crisis and subsequent recession necessitated massive government spending on bailouts, stimulus packages, and automatic stabilizers, leading to a sharp increase in debt.
- COVID-19 Pandemic (2020-2021): The most recent and significant surge in debt came during the pandemic, with unprecedented fiscal responses (stimulus checks, unemployment benefits, business support) to mitigate the economic fallout. These measures added trillions to the national debt in a very short period.
- Ongoing Structural Deficits: Beyond crises, the U.S. faces persistent structural deficits driven by mandatory spending programs like Social Security, Medicare, and Medicaid, which are growing due to an aging population and rising healthcare costs. Interest payments on the existing debt also consume an increasing share of the federal budget.
- Tax Policy: Recent tax cuts, such as the 2017 Tax Cuts and Jobs Act, have also contributed to lower government revenues relative to spending, further exacerbating the debt situation.
The $40 trillion figure represents the culmination of these historical trends and recent shocks. While the U.S. economy remains the world’s largest and most dynamic, the sheer magnitude and rapid increase of this debt raise legitimate questions about its long-term implications, prompting the very debate now unfolding between the Treasury and the IMF.
Broader Economic Implications and the Path Forward
The disagreement between the U.S. Treasury and the IMF carries significant implications for both domestic and global economic policy.
For the U.S. Economy:
- Interest Rates and Inflation: A perception of unsustainable debt could lead bond markets to demand higher yields on U.S. Treasury securities, increasing the cost of borrowing for the government and potentially for businesses and consumers. This could dampen economic growth. Persistent deficits could also contribute to inflationary pressures if they are perceived as fueling excessive demand or if the Federal Reserve is pressured to monetize the debt.
- Fiscal Space and Future Crises: A high debt burden limits the government’s ability to deploy fiscal stimulus in future recessions or crises without further destabilizing its finances.
- Investment and Productivity: If a significant portion of government spending goes towards servicing debt rather than investing in infrastructure, education, or research and development, it could hinder long-term productivity growth.
For the Global Economy:
- Dollar’s Role: While the U.S. dollar’s status as the world’s primary reserve currency provides considerable latitude, persistent concerns about U.S. fiscal health could, in the very long run, erode confidence in the dollar, potentially leading to currency volatility and shifts in global capital flows.
- International Cooperation: A contentious relationship between a major member state like the U.S. and an institution like the IMF could strain international cooperation on critical global economic issues.
- Precedent for Other Nations: The fiscal strategies adopted by the U.S. and the outcomes of its debt management can set precedents or influence policy choices in other countries.
The debate is ultimately about balancing immediate economic needs with long-term fiscal prudence. While the U.S. Treasury emphasizes the dynamism of the American economy and its capacity for growth-driven debt management, the IMF underscores the need for proactive fiscal adjustments to ensure stability. The exchange highlights the enduring tension between national sovereignty in economic policymaking and the collective interest in global financial stability, with the ultimate trajectory of the U.S. national debt remaining a central concern for policymakers and markets worldwide. The ongoing discourse, characterized by Zervos’s direct challenge, suggests that this fundamental policy divergence will continue to shape economic headlines and decisions in the foreseeable future.