
 Ena Muazin
The German savings banks are entering the price war for the new subsidized retirement savings depot, aiming to compete with neo-brokers. Deka, the central fund service provider for the Sparkassen, has announced it will offer a standard retirement savings depot product for an annual fee of just 0.1 percent. This move signals a significant escalation in the competition for long-term investment products, particularly those aimed at retirement planning, as traditional financial institutions seek to retain and attract customers in an increasingly digital and cost-sensitive market.
This strategic pricing by Deka represents a direct challenge to the low-cost models popularized by neo-brokers and other fintech companies, which have steadily eroded the market share of traditional banks by offering significantly lower fees for investment products. The Sparkassen, with their extensive branch network and established customer base, are leveraging their collective strength through Deka to present a competitive alternative that combines digital accessibility with the perceived security and trustworthiness of a large, established financial group.
The new offering from Deka will utilize exchange-traded index funds (ETFs) for its standard depot. Specifically, it will include an international equity ETF and a bond ETF, providing a diversified investment strategy. This approach aligns with the growing trend of passive investing, which has gained traction due to its generally lower costs and historical performance, often matching or exceeding actively managed funds. Customers will have the flexibility to open and manage these accounts digitally, including through the Sparkassen app, as well as in person at the branches of the 340 participating Sparkassen across Germany. This hybrid model aims to cater to a broad spectrum of customer preferences, from those comfortable with fully digital solutions to those who value personal consultation and support.
Background and Context: The Evolving Landscape of Retirement Savings
The German retirement savings market has undergone a significant transformation in recent years. Historically, financial products for long-term savings, such as life insurance policies and traditional bank savings accounts, were characterized by higher fees and often less transparent structures. This led to a growing dissatisfaction among consumers, particularly younger generations, who sought more cost-effective and flexible investment options.
The emergence of neo-brokers, such as Trade Republic, Scalable Capital, and Finanzen.net Zero, has been a pivotal factor in this shift. These platforms have democratized access to investment by offering commission-free trading or extremely low transaction fees, often coupled with attractive interest rates on uninvested cash and low management fees for ETFs. This has put considerable pressure on traditional financial institutions to adapt their offerings and pricing strategies.
The German government has also played a role in shaping the retirement savings landscape. Initiatives like the Riester pension and the Rürup pension (Basisrente) were introduced to encourage private retirement planning. However, these products have also faced criticism for their complexity and associated costs. The recent introduction of the "Altersvorsorgedepot" (retirement savings depot) by regulators aims to create a more streamlined and potentially more cost-effective framework for subsidized retirement savings. Deka’s move to offer a competitive product within this framework is a direct response to this evolving regulatory and market environment.
Deka’s Strategy: Leveraging Scale and Trust
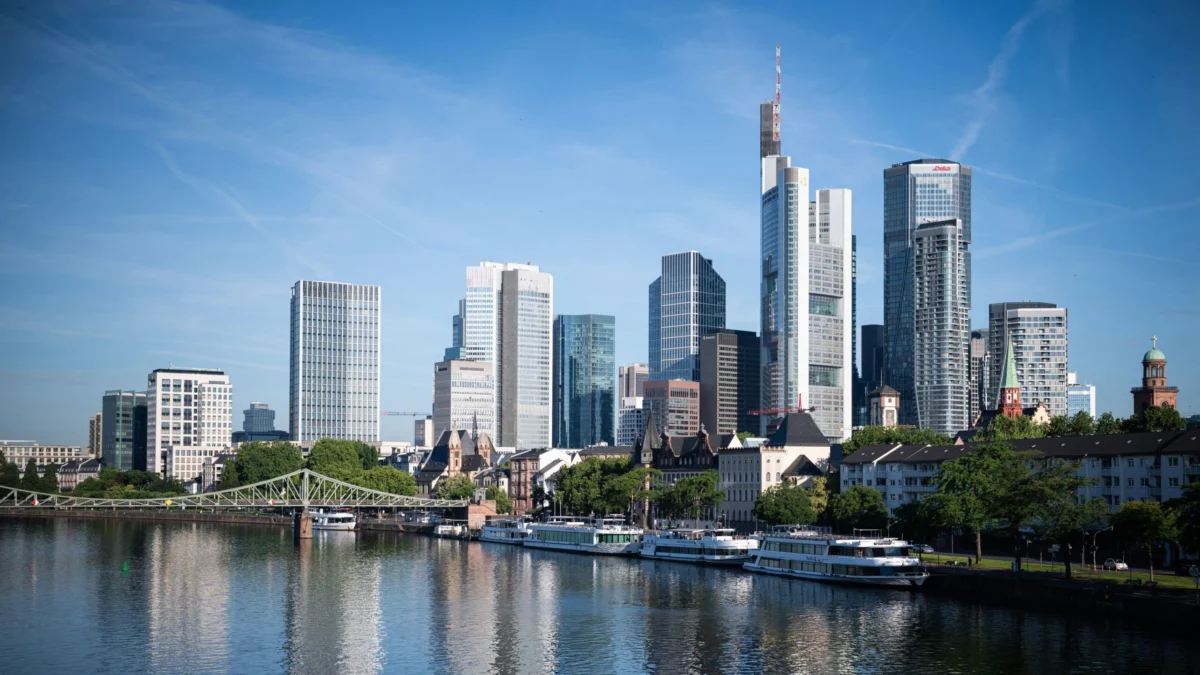
Deka Investment GmbH, headquartered in Frankfurt, serves as the central asset management company for the Sparkassen-Finanzgruppe, one of Germany’s largest financial conglomerates. By pooling the resources and customer base of hundreds of Sparkassen, Deka can achieve significant economies of scale, enabling it to offer products at highly competitive price points.
The decision to offer the retirement savings depot at a mere 0.1 percent annual fee is a bold one. This fee structure is reportedly on par with or even lower than some of the most aggressive offerings from neo-brokers. It suggests a strategic intent to capture a substantial share of the market for subsidized retirement savings, potentially drawing customers away from both neo-brokers and other traditional providers.
The inclusion of ETFs in the product is also a testament to the growing acceptance and popularity of passive investment strategies. ETFs offer diversification across a wide range of assets and geographies, providing a robust foundation for long-term wealth accumulation. By utilizing well-established index funds, Deka aims to deliver consistent returns while minimizing management overheads.
The emphasis on digital accessibility through the Sparkassen app and online platforms is crucial for appealing to younger, tech-savvy investors. However, the continued availability of in-branch services ensures that customers who prefer face-to-face interaction and personalized advice are not excluded. This dual approach is likely to broaden the appeal of the product across different demographic segments.
Competitive Landscape and Market Implications
The 0.1 percent fee for the Deka retirement savings depot directly challenges the pricing models of neo-brokers. For instance, Scalable Capital, a prominent neo-broker, offers its "Prime+ Broker" for a monthly fee which, when annualized, can lead to significantly higher costs for active traders or those with larger portfolios. While specific fee structures vary, Deka’s flat 0.1 percent annual fee on the depot’s value presents a clear and attractive proposition for long-term savers, especially those who may not trade frequently.
This move could force other providers, including neo-brokers, to re-evaluate their own fee structures. The pressure to offer lower costs is likely to intensify, potentially leading to further price reductions across the industry. This ultimately benefits consumers, who gain access to more affordable investment options.
Furthermore, the Sparkassen’s entry into this segment could bolster trust and confidence in retirement savings products. While neo-brokers have gained popularity for their low costs, some consumers may still harbor reservations about the long-term stability and regulatory oversight of newer platforms. The association with the established Sparkassen network could alleviate these concerns.
Data Supporting the Trend:
- Growth of ETF Investments: The global ETF market has experienced exponential growth, with assets under management reaching trillions of dollars. In Germany, ETFs have become increasingly popular, particularly for long-term savings and retirement planning, due to their cost-effectiveness and diversification benefits.
- Market Share of Neo-Brokers: Neo-brokers have captured a significant portion of the retail investment market, especially among younger investors. Their low-fee models have been a primary driver of this success.
- Retirement Savings Gap: Germany, like many developed countries, faces challenges in ensuring adequate retirement income for its aging population. Government initiatives and private sector innovations are crucial for addressing this gap.
Deka’s product offering is a significant development that reflects the ongoing disruption and innovation within the German financial sector. The ability of a large, established group like the Sparkassen, through its service provider Deka, to match or even undercut the pricing of agile neo-brokers is a notable shift.
Potential Challenges and Future Outlook
While the 0.1 percent fee is attractive, the overall profitability for Deka and the Sparkassen will depend on the volume of assets managed and the performance of the underlying ETFs. The success of this initiative will also be measured by its ability to attract new customers and retain existing ones who might have been considering alternatives.
One potential challenge could be the complexity of retirement savings products, even with the new framework. Ensuring that customers fully understand the implications of their investment choices, the risks involved, and the long-term benefits is paramount. Deka and the Sparkassen will need to provide clear communication and robust educational resources.
The digital component of the offering will also be critical. The Sparkassen app and online banking platforms must provide a seamless and intuitive user experience to compete effectively with the dedicated apps of neo-brokers. Integration with existing banking services could be a key advantage.
The broader implications of Deka’s move extend beyond just the retirement savings depot. It signals a more aggressive stance from traditional financial institutions in responding to market changes. We may see further price reductions and product innovations from other large German banks and insurance companies as they seek to defend their market positions.
The competitive dynamic established by this move suggests a future where cost-effectiveness becomes an even more significant differentiator in the financial services industry. Consumers are likely to benefit from a wider array of low-cost, accessible investment products, empowering them to make more informed decisions about their financial future.
In conclusion, the Sparkassen’s entry into the subsidized retirement savings depot market with a 0.1 percent fee is a strategic maneuver designed to combat the rise of neo-brokers. By leveraging their scale, trust, and a hybrid digital-physical service model, they aim to capture a significant share of this growing market. This development underscores the ongoing transformation of the financial landscape, where traditional players are increasingly adopting the competitive strategies of disruptors to remain relevant and serve their customers effectively in an evolving economic environment. The long-term success of this initiative will depend on its ability to attract and retain customers while navigating the complexities of the retirement savings market and the ever-present pressure for competitive pricing.









