Gilang Muhammad
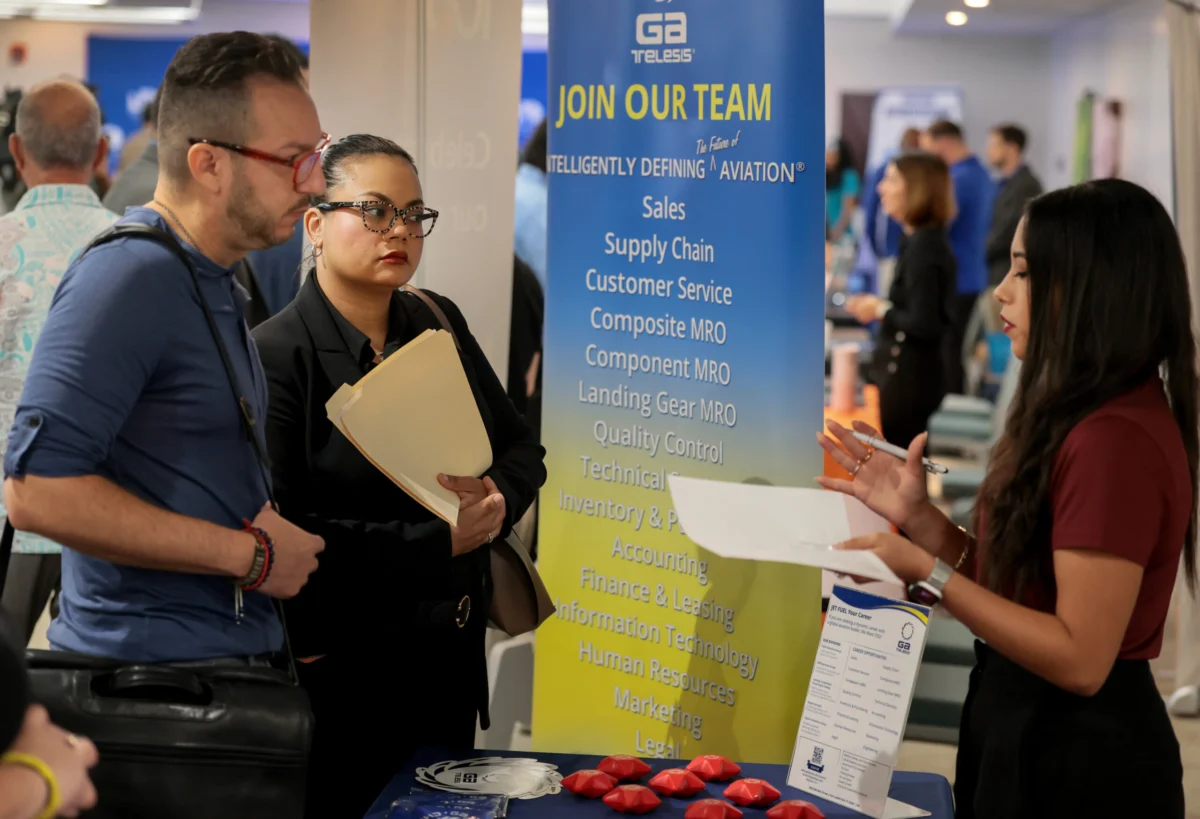
Private sector employment in the United States expanded by a modest 38,000 positions in August, falling short of both market expectations and the pace observed in previous months, according to data released by ADP. This figure marks the smallest monthly increase in private payrolls since January, underscoring a discernible cooling trend within the nation’s labor market, which has been a key focus for economic policymakers. The gains were notably concentrated in a select few sectors, primarily healthcare, while several other industries experienced significant declines, painting a picture of uneven growth across the economic landscape.
The August ADP National Employment Report indicated that the 38,000 new jobs added were fewer than the upwardly revised 46,000 jobs reported for July. It also missed the Dow Jones consensus estimate, which had projected a gain of 47,000 private payrolls. This slowdown is being closely monitored by economists and policymakers alike, as the Federal Reserve continues to assess the impact of its monetary tightening policies on inflation and employment. The report serves as a significant precursor to the more comprehensive nonfarm payrolls data from the Bureau of Labor Statistics (BLS), scheduled for release on Friday, which is expected to provide further clarity on the overall health of the U.S. job market.
A Closer Look at August’s Sectoral Shifts
The granular data from ADP revealed a stark divergence in employment trends across different sectors. Education and health services emerged as the undisputed leader in job creation, adding a robust 45,000 positions. This sector has consistently demonstrated resilience and growth, driven by demographic shifts, an aging population, and ongoing demand for healthcare services. Within this category, health services alone accounted for a substantial portion of the employment expansion, reflecting structural demands that appear largely insulated from broader economic fluctuations.
Beyond healthcare, only a few other sectors posted positive, albeit smaller, gains. Leisure and hospitality, a sector still navigating its post-pandemic recovery and adapting to evolving consumer behaviors, added 16,000 jobs. This indicates a continued, albeit moderated, resurgence in travel, dining, and entertainment activities. The construction sector also saw an increase, adding 12,000 positions. This growth, however, must be viewed in the context of fluctuating interest rates and their impact on housing demand and infrastructure projects, suggesting a nuanced picture within the industry.
Conversely, a significant portion of the economy experienced job losses. Manufacturing, a sector sensitive to global supply chain dynamics, international trade, and consumer demand for goods, shed 17,000 jobs. This decline highlights potential challenges faced by industrial firms, possibly due to inventory adjustments, softening demand, or increased operational costs. Professional and business services, often considered a bellwether for corporate sentiment and investment, also saw a notable contraction, losing 16,000 jobs. This could signal a cautious approach by businesses, potentially deferring hiring or even streamlining operations in response to economic uncertainties.
Further declines were reported in natural resources and mining, which decreased by 5,000 positions, reflecting commodity price volatility and investment cycles. Trade, transportation, and utilities also reported a loss of 5,000 jobs, a development that could be attributed to a normalization of supply chains, shifting consumer spending patterns away from goods towards services, and efficiency gains in logistics. The broad distribution of these losses across several key sectors suggests a more widespread deceleration than merely isolated incidents.
Company Size and Wage Growth Dynamics
An intriguing aspect of the August report was the distribution of job gains by company size. Almost all of the recorded employment growth originated from large businesses, defined as those employing 500 or more workers, which collectively added 34,000 jobs. In stark contrast, small businesses, those with fewer than 50 employees, contributed a mere 3,000 new positions. Mid-sized companies, employing 50 to 499 workers, also showed minimal growth, underscoring a significant disparity in hiring momentum across different organizational scales. Historically, small businesses have been potent engines of job creation in the U.S. economy, making their current subdued performance a point of concern for overall labor market vitality. This trend might reflect smaller firms’ greater sensitivity to rising interest rates, tighter credit conditions, and increased operational costs compared to their larger, more financially robust counterparts.
The ADP report also provided an updated look at pay gains, which remained largely steady for the month. For individuals who stayed in their jobs, base pay increased by 3% from a year ago, while gross pay, which encompasses tips, commissions, bonuses, and other variable earnings, rose by 4.4%. Both figures were unchanged from July, indicating a stable but moderate pace of wage appreciation for incumbent workers. For all workers, including new hires, the respective increases were 3.2% for base pay and 4.7% for gross pay.
The introduction of the base pay versus gross pay distinction in August by ADP offers a more nuanced understanding of compensation trends. Base pay typically reflects underlying structural wage pressures, whereas gross pay can be influenced by more volatile components like bonuses, which might fluctuate based on company performance or economic cycles. The steady growth in both metrics, while moderating from peak inflationary periods, continues to be a factor in the Federal Reserve’s assessment of persistent inflationary pressures. While a cooling labor market is generally expected to temper wage growth, the current rates suggest that wage inflation, though decelerating, remains a component of the broader inflation picture.
Contextualizing the Labor Market Slowdown: A Timeline of Recovery and Adjustment
The August ADP report must be understood within the broader context of the U.S. labor market’s journey over the past few years. Following the unprecedented job losses at the onset of the COVID-19 pandemic in early 2020, the economy embarked on a rapid and robust recovery. From mid-2020 through early 2022, job growth was exceptionally strong, driven by pent-up demand, massive fiscal stimulus, and accommodative monetary policy. Monthly job gains often exceeded 300,000, and at times even 500,000, as businesses rehired furloughed workers and expanded to meet surging consumer demand.

By late 2022 and early 2023, the pace of job creation began to moderate, a deliberate outcome of the Federal Reserve’s aggressive interest rate hikes aimed at cooling an overheating economy and bringing down persistent inflation. The Fed’s objective has been to achieve a "soft landing" – a scenario where inflation returns to its 2% target without triggering a severe recession and significant job losses. The labor market has shown remarkable resilience throughout this tightening cycle, with unemployment rates remaining historically low. However, recent data points, including the August ADP figures, indicate that the cumulative effect of higher rates is now more clearly manifesting in hiring decisions. The shift from robust, broad-based job growth to more concentrated, slower gains signals a transition towards a more balanced labor market, a condition many economists believe is necessary to sustainably achieve price stability.
ADP vs. BLS: Methodologies and Interpretations
The ADP National Employment Report is widely regarded as an important preliminary indicator for the official government employment statistics. However, it is crucial to understand the differences in their methodologies. The ADP report is based on actual payroll data from approximately 25 million U.S. workers across more than 400,000 companies, making it a robust snapshot of private sector employment. The Bureau of Labor Statistics’ (BLS) nonfarm payrolls report, in contrast, is derived from two primary surveys: the Current Employment Statistics (CES) survey, which polls about 122,000 businesses and government agencies representing 666,000 worksites, and the Current Population Survey (CPS), a household survey.
Because of these distinct methodologies, the ADP report and the BLS report do not always align perfectly, though they often indicate similar trends. The ADP data tends to be more volatile month-to-month and is subject to revisions. Historically, the ADP report has offered directional guidance, but its precise numerical correlation with the BLS report can vary significantly. For instance, the BLS nonfarm payrolls report for July showed a decline of 23,000 positions, which included government jobs, while ADP reported an upwardly revised gain of 46,000 private jobs for the same month. This divergence highlights the importance of not relying solely on one report for a complete picture. Market participants closely watch both, using ADP as an initial gauge of momentum ahead of the BLS’s more comprehensive and widely anticipated figures.
Implications for Monetary Policy and the Federal Reserve
The August ADP report adds another layer of complexity to the Federal Reserve’s ongoing assessment of the U.S. economy and its monetary policy decisions. The central bank operates under a dual mandate: to foster maximum employment and maintain price stability. While the unemployment rate has remained low, indicating a strong labor market by historical standards, the Fed has been actively seeking a moderation in job growth and wage pressures to bring inflation back down to its 2% target.
A cooling labor market, as suggested by the latest ADP data, aligns with the Fed’s objectives. Slower job creation and moderating wage growth could alleviate some of the upward pressure on prices, reducing the risk of a persistent wage-price spiral. If the BLS report on Friday corroborates this trend, showing a more significant slowdown in overall hiring, it could reinforce the Fed’s current "wait-and-see" approach regarding further interest rate hikes. Policymakers have emphasized that future decisions will be data-dependent, and signs of a normalizing labor market, alongside progress on inflation, could provide justification for holding rates steady at upcoming meetings.
However, the uneven nature of job growth, with strong gains in some sectors and declines in others, presents a challenge for the Fed. While overall numbers suggest cooling, the continued strength in certain areas, particularly services, combined with steady wage growth, means the battle against inflation is far from over. Analysts will be scrutinizing the BLS report for details on the unemployment rate, labor force participation, and average hourly earnings, as these metrics will offer a more complete picture of labor market slack and inflationary pressures. The Fed’s ultimate decision will weigh these labor market dynamics against inflation data, consumer spending, and broader economic activity.
Market Reactions and Expert Commentary
Financial markets typically react swiftly to employment data, as it profoundly influences expectations for economic growth, corporate earnings, and monetary policy. A weaker-than-expected ADP report often triggers shifts in bond yields, stock market indices, and currency valuations. Bond yields might soften on expectations of a less aggressive Fed, while equity markets could react cautiously, balancing the potential for reduced rate hikes against concerns about slowing economic momentum.
Economists generally interpret a report like August’s ADP as a signal that the economy is gradually decelerating, potentially moving closer to the "soft landing" scenario the Fed desires. However, the unevenness of the report, with certain sectors performing robustly while others contract, suggests underlying complexities. Analysts would likely point to the concentration of job gains in large businesses as a factor indicating a more cautious hiring environment among smaller firms, which are often more sensitive to economic headwinds. The sustained wage growth, while moderating, would also likely be highlighted as an indicator that inflationary pressures, particularly from the labor cost side, are still present, albeit less acutely than before. The consensus among many economic observers is that the labor market is in a delicate transition phase, and the upcoming BLS report will be critical in confirming these nascent trends.
Looking Ahead: The BLS Report and Beyond
The immediate focus now shifts to the Bureau of Labor Statistics’ nonfarm payrolls release, due on Friday. Economists are forecasting an increase of 53,000 nonfarm payrolls for August, following a decline of 23,000 in July, and expect the unemployment rate to hold steady at 4.1%. Should the BLS report align with or undershoot these forecasts, it would largely corroborate the ADP’s indication of a cooling labor market. Conversely, a significantly stronger BLS number could suggest that the ADP report was an outlier or that its methodology captured a different facet of the job market than the government’s more extensive surveys.
Beyond the immediate data release, the trajectory of the U.S. labor market in the coming months will be shaped by several factors. The continued impact of elevated interest rates, global economic conditions, geopolitical developments, and consumer confidence will all play pivotal roles. While a slowdown in hiring is generally seen as a necessary step to tame inflation, policymakers and market participants will be keenly watching to ensure that this cooling does not tip into an outright contraction, which could signal a broader economic downturn. The balance between achieving price stability and maintaining maximum employment remains a critical challenge, and the labor market’s ongoing evolution will be central to that delicate equation. The August ADP report serves as a timely reminder that the era of rapid, broad-based job creation is likely behind us, ushering in a period of more measured and sector-specific growth as the economy continues to adapt to new realities.