 Gilang Muhammad
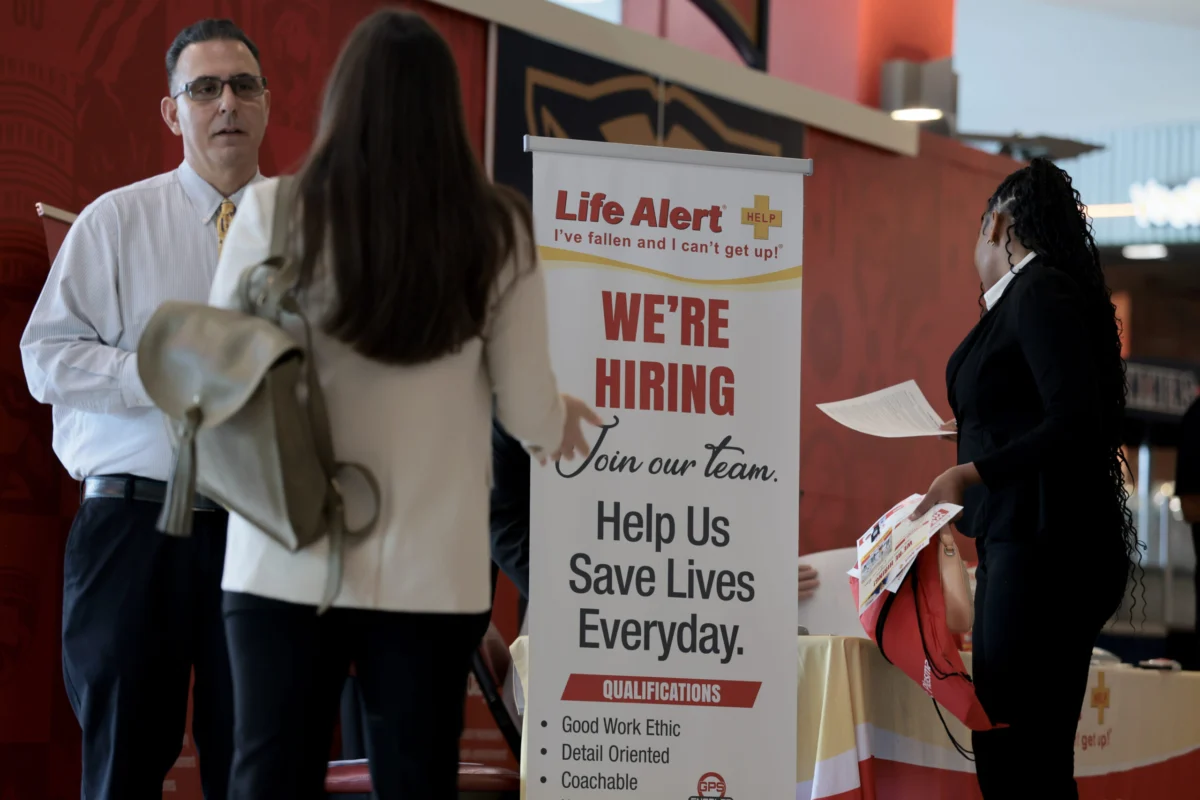
The U.S. labor market demonstrated a notable resurgence in September, with private sector employment experiencing a significant rebound after a period of deceleration. This renewed vigor, as reported by ADP/Stanford Digital Economy Lab on Wednesday, offers further compelling evidence that the nation’s employment landscape has achieved a degree of stabilization following recent economic volatilities. The uptick in job creation surpassed economists’ expectations, providing a critical data point for policymakers and market watchers assessing the trajectory of the American economy.
ADP, a leading payrolls processing firm, announced that companies added a robust 90,000 positions in September. This figure marks a substantial acceleration from the downwardly revised 36,000 jobs added in August and comfortably exceeded the Dow Jones consensus estimate of 68,000. The report’s findings paint a picture of resilience, suggesting that despite ongoing monetary tightening by the Federal Reserve, businesses continue to expand their workforces, albeit at a more measured pace than the rapid growth seen in the immediate post-pandemic recovery.
A Balanced Expansion Across Sectors
A key characteristic of the September ADP report was the balanced nature of job creation across different segments of the economy. Service-providing sectors, which typically account for the lion’s share of U.S. employment, led the gains by adding 59,000 positions. This continued strength in services underscores robust consumer demand and the ongoing recovery in sectors heavily impacted by the pandemic. Simultaneously, goods-producing industries contributed a healthy 31,000 new jobs, indicating sustained activity in areas like manufacturing and construction.
Digging deeper into the sectoral contributions, education and health services emerged as the primary engine of growth, accounting for a significant 55,000 new hires. This reflects persistent demand for healthcare services and educational infrastructure. Leisure and hospitality, a sector often seen as a bellwether for consumer confidence and discretionary spending, also saw strong gains with 22,000 new jobs. Manufacturing added 17,000 positions, defying some expectations of a slowdown in industrial activity, while the construction sector contributed 15,000 jobs, suggesting ongoing investment in infrastructure and housing despite higher interest rates.
However, not all sectors experienced growth. A handful of industries registered job losses, highlighting the uneven impact of current economic conditions. Financial activities shed 16,000 positions, potentially reflecting the impact of rising interest rates on lending and investment, as well as a more cautious approach from financial institutions. Professional and business services saw a decrease of 11,000 jobs, an area that can be sensitive to overall business spending and economic uncertainty. Natural resources and mining experienced a modest loss of 1,000 jobs.
Wage Growth and Inflationary Pressures
Beyond job numbers, the ADP report also provided crucial insights into wage dynamics. Base pay for workers who remained in their jobs rose by 3.2% from a year ago. For those who switched jobs, gross pay accelerated by 4.7% year-over-year. While these figures indicate continued wage growth, they also suggest a moderation from the elevated rates observed in previous periods, which had fueled concerns about a potential wage-price spiral.
Nela Richardson, ADP’s chief economist, characterized the report as "strong," emphasizing the rebound in job creation after a three-month slowdown and the sustained, albeit moderating, pay growth. Her statement underscores the sentiment that the labor market, while no longer exhibiting the explosive growth of 2021-2022, remains fundamentally sound and continues to provide employment opportunities. The balance between job growth and wage moderation is a delicate one, closely watched by the Federal Reserve for its implications on inflation. If wage growth outpaces productivity gains too significantly, it can contribute to inflationary pressures, making the Fed’s task of bringing inflation back to its 2% target more challenging.
Geographic and Business Size Trends
The September report also shed light on where job growth is concentrated geographically and by company size. The Northeast region emerged as a significant driver of employment gains, adding 56,000 jobs. This regional strength could be attributed to various factors, including robust economic activity in major metropolitan areas, specific industry concentrations, or perhaps a delayed recovery compared to other regions.
In terms of business size, companies employing between 50 and 499 workers, often referred to as mid-sized businesses, were the primary contributors to job growth, recording a gain of 54,000 positions. This indicates that these agile and often growing enterprises are actively hiring, playing a crucial role in the broader employment picture. Larger enterprises (500+ employees) also saw gains, albeit smaller, while small businesses (1-49 employees) showed a more subdued performance. This distribution suggests that mid-sized firms may be less susceptible to the same economic headwinds as very small businesses, which often lack the capital buffers, or the cautious hiring strategies sometimes adopted by very large corporations.
The Federal Reserve’s Stance and Economic Context

The findings of the ADP report align with the broader sentiment expressed by multiple Federal Reserve officials, who have consistently indicated that the labor market is largely sound. This assessment follows a period of concern about economic growth in early 2025, which has since dissipated, giving way to a focus on persistent inflation. Policymakers at the central bank view the greater policy risk now as the continued upward pressure on prices, rather than a significant weakening of the job market. This perspective was a key factor in the Fed’s decision to raise benchmark borrowing rates by a quarter percentage point earlier in September, continuing its aggressive campaign to cool the economy and bring inflation under control.
The Fed’s dual mandate includes maximizing employment and maintaining price stability. With the labor market showing resilience, the central bank’s attention has squarely shifted to the latter. The target inflation rate for the Fed is 2%, and while some progress has been made, inflation has remained stubbornly above this goal for an extended period. The continued strength in job creation and wage growth, while positive for workers, could complicate the Fed’s efforts to curb inflation without triggering a significant economic downturn, a scenario often referred to as a "soft landing."
Timeline of Economic Indicators and Monetary Policy
To fully appreciate the significance of the September ADP report, it’s essential to place it within a broader economic timeline. The Federal Reserve began its aggressive cycle of interest rate hikes in early 2022, responding to inflation that had surged to multi-decade highs. Since then, the federal funds rate has been incrementally increased, moving from near-zero to significantly higher levels, with the latest quarter-point hike occurring in September 2025. Each hike aims to make borrowing more expensive, thereby slowing economic activity, reducing demand, and ultimately easing inflationary pressures.
Throughout 2023 and 2024, the labor market defied many predictions of a sharp slowdown, maintaining robust job growth and low unemployment rates even as interest rates climbed. This resilience was a source of both relief (avoiding a deep recession) and concern (potential for persistent inflation). The "three-month slowdown" mentioned by ADP’s chief economist refers to a period prior to September where monthly job gains had tapered off, leading some to believe the Fed’s policies were finally having a more pronounced effect on employment. The September rebound, therefore, suggests that the labor market’s underlying strength may be more entrenched than previously thought, or that businesses are adapting to the higher interest rate environment.
Other key economic indicators in the preceding months have shown a mixed picture. While the Consumer Price Index (CPI) has moderated from its peak, it has remained elevated, largely driven by sticky service sector inflation and, at times, volatile energy prices. Retail sales data has generally indicated resilient consumer spending, supported by a strong job market and accumulated savings, although some softening has been observed. The Job Openings and Labor Turnover Survey (JOLTS) has shown a gradual decline in job openings and quit rates from their pandemic highs, indicating a rebalancing of labor supply and demand, but still suggesting a relatively tight labor market.
ADP Report as a Precursor to Official Data
The ADP count serves as an important precursor to the more comprehensive nonfarm payrolls report released by the Bureau of Labor Statistics (BLS). The BLS report, typically published on the first Friday of each month, is considered the gold standard for U.S. labor market data. While ADP and BLS reports use different methodologies and scopes, economists and analysts often look to the ADP data for an early indication of the BLS figures.
For the upcoming BLS nonfarm payrolls report, scheduled for release on Friday, the Wall Street consensus is for a gain of 84,000 jobs. This forecast is a significant reduction from the 162,000 increase reported by the BLS in the prior month. The unemployment rate is projected to hold steady at 4.1%. The ADP report, coming in higher than its own consensus, might lead some analysts to revise their BLS expectations slightly upwards, suggesting the official figures could also surprise to the upside. However, it’s crucial to remember that the two reports do not always perfectly correlate, and discrepancies can arise due to differences in sampling, definitions, and collection periods. The BLS survey includes government workers and a broader range of establishments, whereas ADP primarily focuses on private sector payrolls.
Implications for Monetary Policy and the Economy
The strong September ADP report carries significant implications for the Federal Reserve’s future monetary policy decisions. With job creation rebounding and wage growth remaining solid, the Fed will likely interpret this as further evidence that the economy can withstand current interest rate levels. This could reinforce the central bank’s resolve to maintain a restrictive monetary policy for longer, or even consider further rate hikes if inflation does not show clearer signs of deceleration. The prospect of higher-for-longer interest rates could impact various segments of the economy, including mortgage rates, corporate borrowing costs, and investment decisions.
For businesses, the continued availability of labor, even at moderating wage growth, provides opportunities for expansion and investment. However, firms in sectors experiencing labor shortages may still face challenges in hiring and retaining talent. Consumers, bolstered by job security and rising wages, are likely to maintain their spending patterns, which will continue to support economic activity but also contribute to demand-side inflationary pressures.
From a broader economic perspective, the report strengthens the argument for a "soft landing" scenario, where the Fed successfully tames inflation without pushing the economy into a deep recession. The resilience of the labor market is a critical component of this optimistic outlook. However, the path remains fraught with challenges, including geopolitical uncertainties, supply chain disruptions, and the unpredictable nature of consumer and business sentiment. The upcoming BLS report, along with other key economic indicators, will be closely scrutinized to confirm whether September’s job rebound represents a sustained trend or a temporary fluctuation in the dynamic U.S. labor market.