Gilang Muhammad
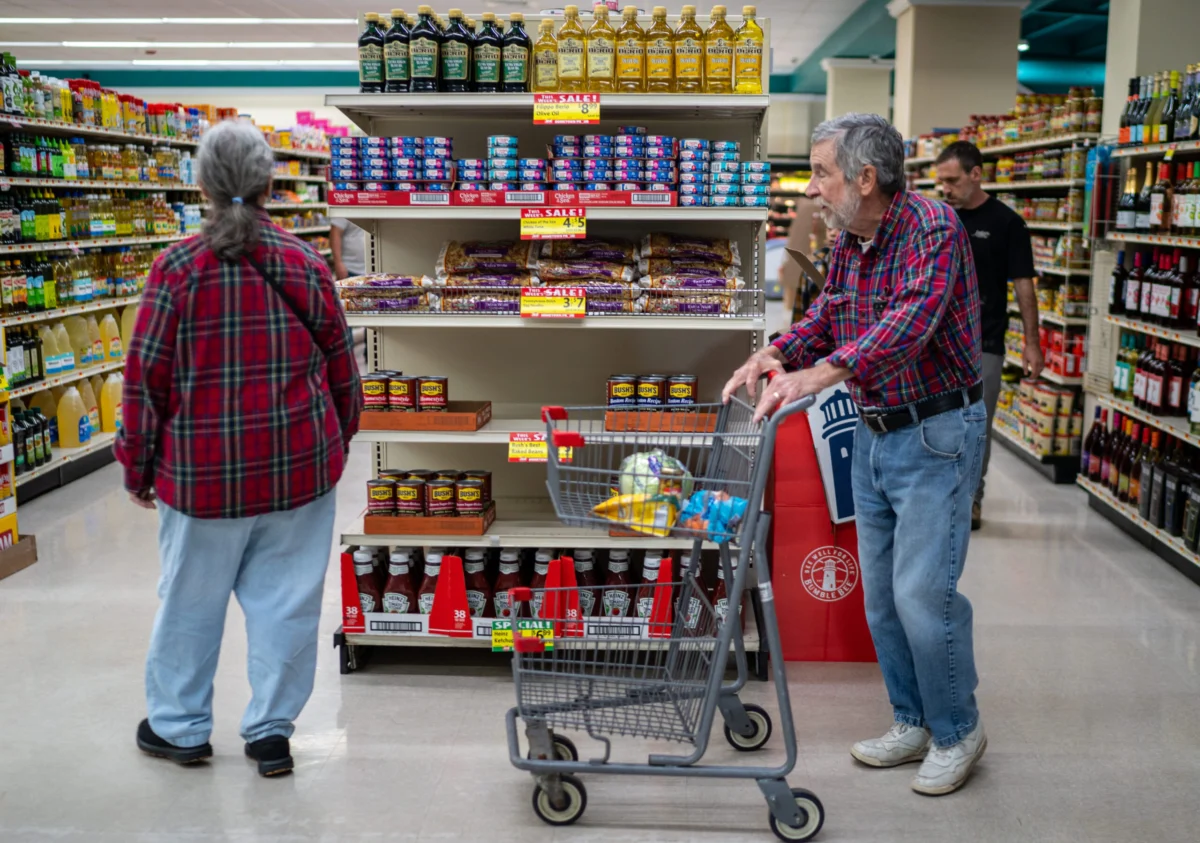
September delivered a sobering reminder of the persistent inflationary pressures facing the U.S. economy, as consumer prices continued their upward trajectory, maintaining an inflation rate significantly above the Federal Reserve’s long-term target. This latest data point underscores the challenges policymakers face in taming price growth without stifling economic activity, especially amidst ongoing geopolitical tensions and robust domestic demand in certain sectors.
The September Snapshot: Unpacking the Latest Inflation Data
The Bureau of Labor Statistics (BLS) released its eagerly anticipated Consumer Price Index (CPI) report on Wednesday, revealing a seasonally adjusted monthly increase of 0.6% for September. This pushed the 12-month headline inflation rate to 3.7%. These figures largely met, and in some cases, slightly exceeded, the expectations of economists surveyed by Dow Jones, who had projected respective gains of 0.6% for the month and 3.6% on an annual basis. The report highlighted that the accelerating cost of living continues to be a formidable hurdle for American households and a central concern for financial markets.
A crucial metric for policymakers, the so-called "core CPI," which strips out the often-volatile food and energy components, also demonstrated upward momentum. Core CPI rose by 0.3% for the month, translating to an annual increase of 2.6%. This also surpassed analyst forecasts, which had anticipated a 0.2% monthly rise and a 2.5% annual increase. The core inflation figure is particularly scrutinized by the Federal Reserve as it is considered a more accurate gauge of underlying, persistent price trends, less influenced by transient supply shocks.
Comparing September’s data to the preceding month, the acceleration in inflation becomes evident. In August, the annual rate for headline inflation stood at 3.4%, while the core rate was 2.4%. This month-over-month increase in both headline and core measures signals a broadening of inflationary pressures, moving beyond just a few isolated categories. The persistence of core inflation above the Fed’s 2% target, even if moderating from peak levels, indicates that price stability remains an elusive goal.
The Primary Culprits: Energy Surges and Broadening Pressures
The primary driver behind September’s elevated inflation figures was unequivocally the surging cost of energy. The energy index experienced a significant jump of 5.2% during the month, a direct reflection of heightened geopolitical tensions and supply concerns. This increase is largely attributable to the ongoing conflict between the U.S. and Iran, which escalated following strikes launched in late February and has shown no immediate signs of de-escalation. Such conflicts invariably disrupt global energy markets, leading to price volatility and upward pressure on fuel costs.
Within the energy complex, gasoline prices were a standout contributor to the overall CPI increase, soaring by 9.1% in September alone. According to the BLS, this dramatic increase in gasoline costs accounted for approximately half of the gain in the headline CPI. Looking at a broader historical perspective, gasoline prices have posted an alarming 34.2% rise over the past year. Even more striking, fuel oil prices have roared higher by an astounding 74.2% over the same 12-month period, demonstrating the profound impact of global energy market dynamics on consumer budgets. These energy price hikes filter through the economy, affecting transportation costs for goods and services, and ultimately, consumer prices.
While energy dominated the headlines, other components of the CPI also contributed to the overall inflationary picture, albeit with varying degrees of intensity. Food prices, which have been a significant concern for households over the past couple of years, remained flat on a monthly basis in September, offering a slight reprieve. However, on an annual basis, food costs were still up 2.5% from a year ago, reflecting the cumulative impact of past price increases.
Shelter costs, a notoriously "sticky" component of inflation due to its slower-moving nature, continued their upward march, increasing by 0.4% for the month. Shelter, which includes rent and owner’s equivalent rent, represents a substantial portion of household budgets and its persistent increase contributes significantly to the feeling of an accelerating cost of living. Used car and truck prices, another segment that saw dramatic increases during the pandemic-era supply chain disruptions, jumped by 0.7% in September, indicating renewed demand or constrained supply in that market. Apparel prices, which are often sensitive to trade policies and tariffs, also increased by 0.3% for the month and are up 3.4% on an annual basis, suggesting that various economic factors continue to exert upward pressure across a range of consumer goods.
The Federal Reserve’s Tightrope Walk: Policy Implications and Market Reactions
The release of September’s CPI data immediately sent ripples through financial markets, signaling a likely recalibration of expectations regarding the Federal Reserve’s future monetary policy path. Stock market futures turned negative shortly after the report’s release, reflecting investor anxiety about higher interest rates and their potential impact on corporate earnings and economic growth. Simultaneously, bond yields, which move inversely to prices, rose sharply as traders anticipated a more hawkish stance from the central bank.
Futures traders, utilizing tools like the CME Group’s FedWatch, swiftly adjusted their probabilities for an upcoming interest rate hike. For the Federal Open Market Committee (FOMC) meeting scheduled for October 27-28, the odds of a rate hike climbed to approximately 54%. Looking further ahead, the likelihood of a rate increase before the end of the year surged to better than 96%, with a near 50-50 chance of the Fed boosting rates by a more aggressive half a percentage point by December. These market movements underscore the immediate and significant impact of inflation data on monetary policy expectations.

This CPI reading holds particular significance as it is the final comprehensive inflation report that FOMC officials will receive before their pivotal October meeting. The BLS is also slated to release the September reading on the Producer Price Index (PPI) on Thursday, a measure of wholesale costs, which provides further insight into pipeline inflationary pressures that could eventually pass through to consumers.
The Federal Reserve operates under a dual mandate: to foster maximum employment and maintain price stability. Its long-standing target for inflation, as measured by the Personal Consumption Expenditures (PCE) price index, is 2%. The CPI, while a broader and more frequently cited measure, has consistently surpassed this 2% benchmark since March 2021. The gauge had shown signs of moderating earlier in the year, but then experienced a renewed spike following the geopolitical events involving the U.S. and Israel’s strikes against Iran. While the year-over-year trend has shown some moderation over the past few months, it has stubbornly held well above the Fed’s target, presenting a persistent challenge.
In response to these enduring inflationary pressures, Fed officials approved their first interest rate hike in more than three years in September, a quarter-percentage-point move that lifted the benchmark federal funds rate to a target range of 3.75%-4%. While markets currently expect the Fed to potentially skip an increase in October, the consensus strongly points towards another hike in December. Beyond the current year, market pricing implies that the Fed could raise rates at least twice more in 2027, signaling a prolonged period of tighter monetary policy.
The Fed’s dilemma is complex. Supply shocks, such as those driving the recent energy surge, are often considered temporary and policymakers sometimes choose to "look through" them when setting rates, believing their impact will naturally dissipate. However, a significant concern among Fed officials is that the longer the U.S.-Iran conflict drags on, the higher the likelihood that the spike in energy prices and other related costs will permeate through the broader economy, becoming embedded in consumer and business expectations. If inflation expectations become unanchored, it becomes far more difficult to bring actual inflation back down.
Adding to these pressures, prices have also faced upward momentum from President Donald Trump’s tariffs, which increase import costs, as well as robust demand for goods and services associated with the artificial intelligence (AI) build-out. The burgeoning AI sector requires significant investment in hardware, software, and infrastructure, contributing to demand-side inflationary pressures in specific markets.
Despite the latest CPI data, a number of key policymakers have recently expressed the belief that the Fed doesn’t need to rush into implementing another rate hike, advocating for a cautious, data-dependent approach. However, the prevailing sentiment among most officials is that at least one more increase will likely be necessary this year to ensure inflation is firmly on a downward path towards the 2% target. It is important to note that while the Fed closely monitors the CPI, its primary forecast and policymaking metric is the Commerce Department’s Personal Consumption Expenditures (PCE) price index. The PCE numbers for September will not be released until later in the month, offering another critical data point for the central bank.
Expert Analysis and Broader Economic Landscape
Economic analysts were quick to dissect the implications of the September CPI report. Sonu Varghese, chief macro strategist at Carson Group, succinctly captured the sentiment, stating, "CPI came in hot and it wasn’t just fuel prices, as core inflation ran at a 3.7% annualized pace in September and 3.2% over three years." Varghese further noted, "The only surprise is that investors keep getting surprised by broad-based inflation. And we’ve yet to see the full impact of higher diesel prices and the AI boom." His commentary highlights the pervasive nature of current inflationary pressures, extending beyond just energy, and points to potential future drivers that could keep prices elevated. The impact of higher diesel prices, for instance, has a widespread effect on supply chains and transportation costs for nearly all goods.
The broader economic landscape presents a challenging environment. For consumers, persistent inflation erodes purchasing power, forcing households to allocate a larger portion of their budgets to essential goods and services, potentially curtailing discretionary spending. This disproportionately affects lower-income households, which spend a greater percentage of their income on necessities like food, energy, and shelter. Businesses, in turn, face higher input costs, which may be passed on to consumers in the form of higher prices, or absorbed, potentially squeezing profit margins.
The Federal Reserve’s primary objective is to engineer a "soft landing," where inflation is brought back to target without triggering a significant economic downturn or recession. This is a notoriously difficult task, often likened to threading a needle. The combination of supply-side shocks from geopolitical events, demand-side pressures from a resilient labor market and specific sector booms like AI, and lingering effects from past fiscal stimulus creates a complex environment for monetary policy. The risk remains that if the Fed tightens too aggressively, it could push the economy into a recession, while insufficient tightening could allow inflation to become entrenched.
Looking ahead, the global economic interconnectedness means that events far beyond U.S. borders, particularly in energy-producing regions, will continue to play a crucial role in the domestic inflation narrative. The ongoing U.S.-Iran conflict, global demand trends, and the pace of economic growth in major economies like China will all contribute to the dynamics of commodity prices and supply chains. Domestically, the continued strength of the labor market, wage growth, and consumer spending patterns will be critical factors influencing the trajectory of inflation. The coming months will be a critical period for the Federal Reserve as it navigates these complex forces, striving to restore price stability while preserving economic growth.