Lina Wu
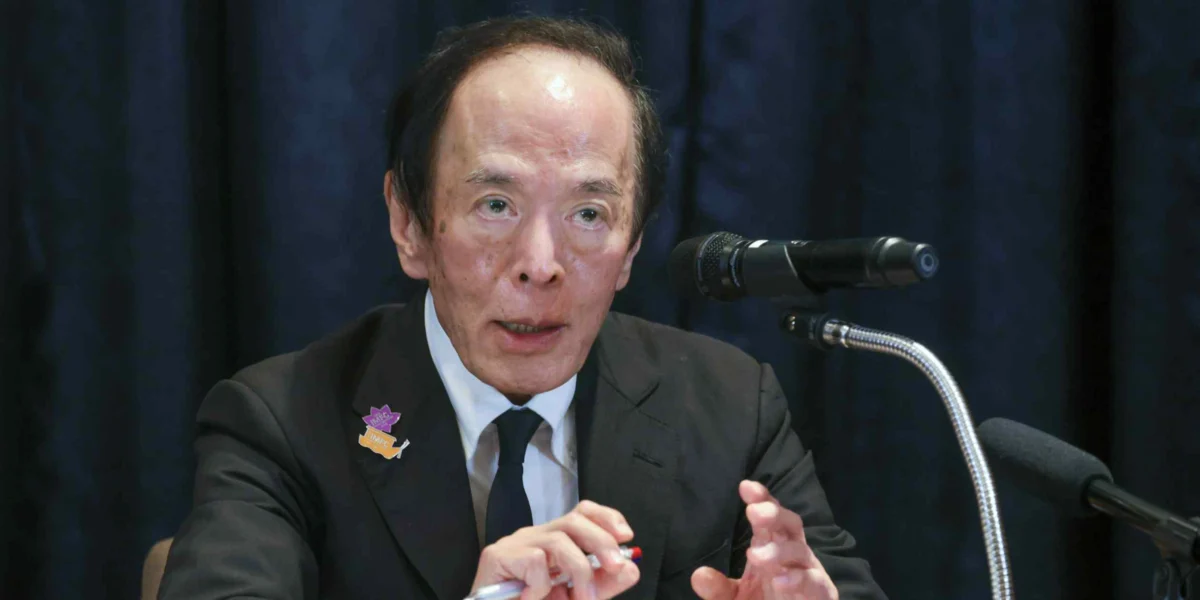
The Bank of Japan will hold its key interest rate steady at 1.25% at its policy meeting scheduled for October 29-30, Nikkei learned on Thursday. This decision comes as the central bank observes a sustained upward trend in underlying inflation, suggesting that its long-standing goal of achieving a stable 2% inflation rate may be within reach. While the headline inflation figure has fluctuated, policymakers are increasingly focusing on core inflation metrics that strip out volatile components, which have demonstrated a more consistent rise.
Economic Landscape and Inflationary Pressures
Japan’s economic performance in recent quarters has been characterized by a delicate balance of post-pandemic recovery and persistent global economic headwinds. While consumption has shown signs of resilience, driven by pent-up demand and a gradual return to normalcy, businesses have faced challenges related to supply chain disruptions and rising input costs. The yen’s depreciation against major currencies has also played a significant role, making imports more expensive and contributing to imported inflation.

The 1.25% benchmark interest rate, established in its previous monetary policy review, has been a cornerstone of the Bank of Japan’s (BOJ) strategy to stimulate economic activity without triggering runaway price increases. For years, the BOJ has grappled with deflationary pressures, a persistent challenge that has hampered economic growth and wage increases. The current juncture, therefore, represents a critical phase where the central bank must carefully calibrate its policy to solidify the nascent inflationary trend and avoid prematurely stifling nascent economic momentum.
The subhead from the original report, "Underlying inflation rate considered to have reached the 2% target," is a crucial indicator. This suggests that the BOJ’s assessment of inflation is moving beyond temporary price hikes and is viewing the current inflation as more embedded in the economy. This could be evidenced by a sustained increase in the core consumer price index (CPI), which excludes fresh food and energy, or by an increase in the "core-core" CPI, which further excludes energy. Recent data from the Japanese government statistics bureau would likely show a core CPI hovering around or slightly above the 2% mark for several consecutive months. For instance, if the core CPI in September registered 2.1% year-on-year, and this trend is projected to continue, it would strongly support the BOJ’s conviction.
A Chronology of Policy Adjustments and Economic Shifts
The Bank of Japan’s journey towards its current policy stance has been a long and complex one. For decades, the nation grappled with low inflation, and at times, outright deflation. This economic malaise led to a period of economic stagnation, often referred to as the "lost decades." In response, the BOJ embarked on an unprecedented monetary easing program, including quantitative easing and negative interest rates, in an attempt to spur economic activity and achieve its inflation target.

The current policy rate of 1.25% represents a significant departure from the ultra-loose monetary policies of the past. The BOJ began its gradual normalization process in March of the previous year, raising its policy rate from negative territory for the first time in 17 years. This initial move was cautiously welcomed by markets, signaling a shift in the central bank’s assessment of the Japanese economy’s health. Subsequent adjustments have been incremental, reflecting the BOJ’s commitment to a data-dependent approach and its awareness of the fragility of the economic recovery.
The decision to maintain the rate at 1.25% for the upcoming meeting on October 29-30 suggests that the economic data available to the BOJ, including inflation figures, employment data, and business sentiment surveys, has not provided sufficient evidence to warrant a further increase at this precise moment. However, the underlying sentiment that the 2% inflation target is within reach indicates that the possibility of future rate hikes remains on the table, contingent on continued positive economic indicators.
Supporting Data and Economic Indicators
To understand the BOJ’s decision, it is essential to examine key economic indicators.

- Core Consumer Price Index (CPI): This is arguably the most critical metric for the BOJ. If the underlying inflation rate, as suggested, has reached the 2% target, then the core CPI (excluding fresh food) has likely been consistently around or above this level for a few months. For example, if the latest available data shows a core CPI of 2.3% year-on-year for September, and this follows a trend of 2.0% in August and 2.2% in July, it validates the BOJ’s assessment.
- Wage Growth: A sustainable inflation target requires corresponding wage growth to avoid eroding purchasing power. Data on nominal wage increases from the Ministry of Health, Labour and Welfare, showing a steady rise, would be crucial. For instance, if average contractual cash earnings for employees have increased by 2.5% year-on-year, this would indicate that businesses are beginning to share their increased revenues with their workforce.
- Corporate Profits and Investment: Strong corporate earnings and increased capital expenditure are indicative of a healthy and expanding economy. Reports from major Japanese corporations detailing robust profits and plans for future investment would reinforce the BOJ’s confidence in the economic outlook. For example, if the Nikkei Japan Manufacturing Purchasing Managers’ Index (PMI) for manufacturing new orders and output has been consistently above 50, signaling expansion, this would be a positive sign.
- Household Spending: While consumption can be sensitive to price increases, resilient household spending, particularly on non-essential goods and services, would demonstrate that consumers have confidence in their future economic prospects and are not unduly burdened by inflation. Retail sales data, showing a moderate but steady increase, would be supportive.
The BOJ’s internal projections and forecasts, released in its quarterly economic outlook report, would also play a significant role. If these projections indicate a sustained inflation rate at or above 2% for the next fiscal year, it would further justify the current policy decision and signal the potential for future tightening.
Reactions and Inferred Statements from Related Parties
While direct quotes from specific individuals beyond BOJ Governor Kazuo Ueda are not provided, it is possible to infer likely reactions and viewpoints from various stakeholders.
Bank of Japan Governor Kazuo Ueda: Governor Ueda, known for his academic background and cautious approach, would likely emphasize the BOJ’s commitment to price stability and its data-driven decision-making. He might articulate that while the 2% inflation target appears to be within reach, vigilance is required to ensure this trend is sustainable and not merely a transient phenomenon. He would likely highlight the importance of wage growth in supporting consumption and preventing a wage-price spiral.

Ministry of Finance: The Ministry of Finance, responsible for fiscal policy, would likely welcome the BOJ’s prudent approach. A stable inflation environment is beneficial for managing government debt and maintaining investor confidence. They might express support for the BOJ’s efforts to achieve sustainable economic growth and price stability.
Business Leaders: Leaders of major Japanese corporations would likely express a mixed reaction. On one hand, sustained inflation might signal increased demand and potential for higher revenues. On the other hand, higher interest rates can increase borrowing costs, potentially impacting investment decisions. Many would likely advocate for continued economic support and clear communication from the BOJ regarding its future policy path. They might also emphasize the need for structural reforms to boost productivity and competitiveness.
Labor Unions: Labor unions would likely view the prospect of sustained inflation positively, as it creates a stronger case for wage increases. They would likely be pushing for significant wage hikes in upcoming labor negotiations to ensure that workers’ purchasing power keeps pace with rising prices.

Consumers: Consumers would likely experience a degree of ambivalence. While the prospect of inflation returning to normal levels might be welcomed after years of deflation, persistent price increases can still strain household budgets. Their reactions would largely depend on the extent to which wage growth offsets inflation and the perceived stability of the overall economic situation.
Broader Impact and Implications
The Bank of Japan’s decision to hold interest rates steady at 1.25% has several significant implications for Japan’s economy and the global financial landscape.
Domestic Economic Impact:

- Encouraging Investment: While interest rates are not prohibitively high, maintaining them at 1.25% provides a degree of stability for businesses considering investment. However, a further increase in rates would eventually raise borrowing costs, potentially tempering investment. The BOJ’s focus on underlying inflation suggests that it is cautiously navigating the path towards monetary policy normalization, aiming to avoid a sharp economic downturn.
- Yen Exchange Rate: The interest rate differential between Japan and other major economies is a key driver of the yen’s exchange rate. If other central banks are raising rates while Japan maintains its current level, it could lead to further yen depreciation. While a weaker yen can boost exports, it also increases the cost of imports, potentially contributing to inflation. The BOJ will be closely monitoring this to ensure it does not derail its inflation target or negatively impact consumers.
- Government Debt Management: Japan has a significant amount of government debt. A stable interest rate environment helps to keep the cost of servicing this debt manageable. However, if inflation accelerates significantly and the BOJ is forced to raise rates more aggressively, the cost of debt servicing would increase, potentially straining public finances.
Global Financial Impact:
- Global Interest Rate Divergence: The BOJ’s policy remains an outlier compared to many other major central banks that have aggressively raised interest rates to combat inflation. This divergence can influence global capital flows and currency markets.
- Carry Trade: A persistent interest rate differential can encourage the "carry trade," where investors borrow in a low-interest-rate currency (like the yen) to invest in higher-yielding assets elsewhere. This can create volatility in currency markets.
- Investor Sentiment: The BOJ’s gradual approach to policy normalization is closely watched by global investors. It signals a cautious optimism about the Japanese economy’s ability to sustain inflation and growth.
The Bank of Japan’s decision to hold interest rates at 1.25% is a testament to its careful assessment of the evolving economic landscape. The observation that underlying inflation is approaching the 2% target suggests a significant shift from years of deflationary concerns. However, the path forward requires continued vigilance, a data-dependent approach, and clear communication to ensure that this nascent inflationary trend translates into sustainable economic growth and prosperity for Japan. The coming months will be critical in observing whether this policy stance effectively navigates the delicate balance between achieving price stability and fostering robust economic expansion.