Gilang Muhammad
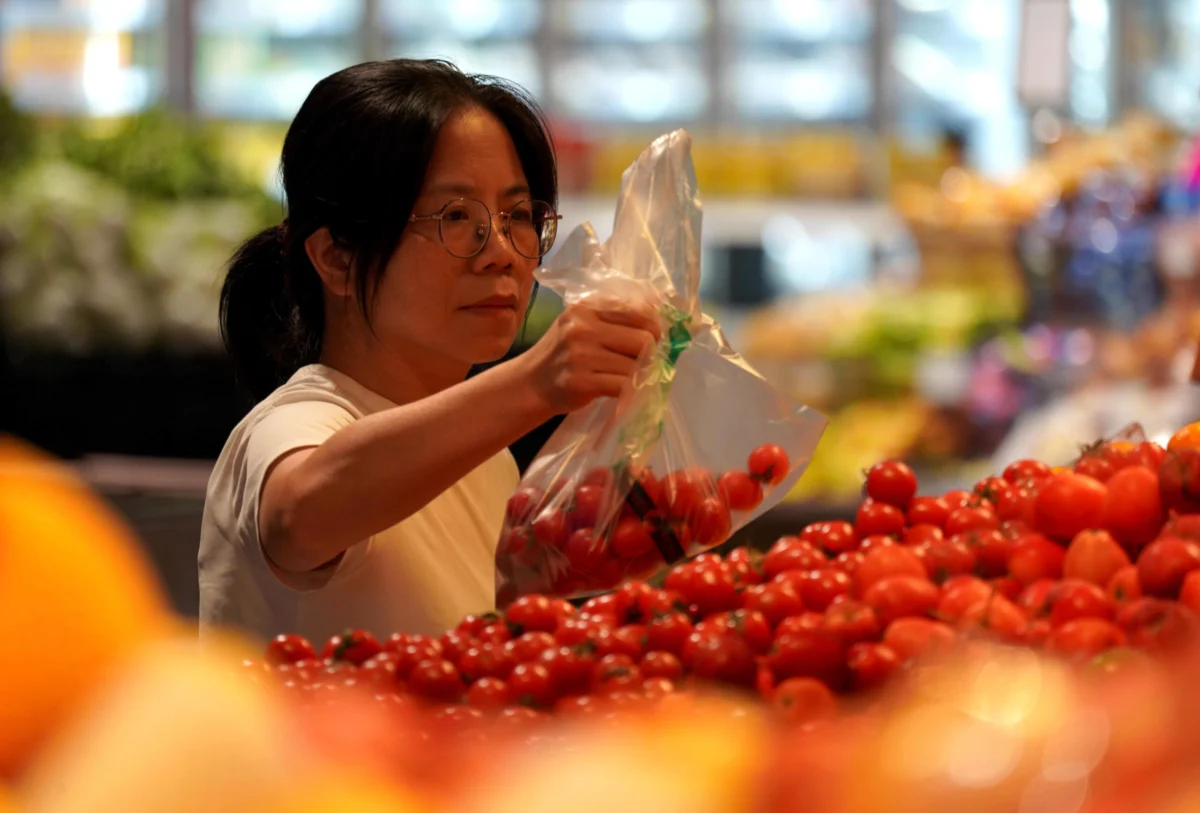
YUEQING, CHINA – October 14, 2026, saw shoppers navigating the aisles of a bustling supermarket in Yueqing, Zhejiang Province, a commonplace scene that belies the complex and divergent inflationary pressures currently shaping China’s vast economy. Fresh data released for October 2026 has revealed a striking bifurcation: producer prices are accelerating at their fastest pace in over two years, fueled by powerful external demand, while consumer inflation is cooling, underscoring persistent weaknesses in domestic spending. This delicate balance presents a significant challenge for policymakers seeking to foster stable economic growth.
Producer Price Inflation (PPI) Reaches Multi-Year Peak
China’s Producer Price Index (PPI), a key gauge of factory-gate inflation, registered a notable 5.7% year-on-year increase in October. This figure not only surpassed economists’ expectations of 5.3% in a Reuters poll but also marked the third consecutive month of acceleration, hitting a growth rate unseen since June 2022. The upward trajectory of the PPI signals intensifying cost pressures for Chinese manufacturers, primarily driven by a sharp escalation in prices within the crucial mining and raw materials industries.
The impetus behind this surge is, as Zhang Zhiwei, president and chief economist at Pinpoint Asset Management, articulated to CNBC’s "Squawk Box Asia," "very strong external demand." This robust global appetite for Chinese goods, coupled with elevated international commodity prices, has translated directly into higher input costs for domestic producers. For instance, global energy prices, particularly for crude oil and natural gas, have remained volatile throughout 2026, often spiking due to geopolitical tensions and supply chain constraints. Similarly, industrial metals like copper, aluminum, and iron ore, essential components for manufacturing, have seen their prices buoyed by a resurgence in global industrial activity and strategic stockpiling in various economies. This confluence of factors has pushed raw material costs upwards, leaving Chinese factories to grapple with expanding operational expenses.
The last time China’s PPI reached such heights in June 2022, the global economy was still grappling with the lingering effects of the COVID-19 pandemic, exacerbated by the initial shocks of the conflict in Ukraine, which sent energy and food prices soaring worldwide. The current surge, while distinct in its drivers, evokes a similar sense of cost-push inflation for businesses. For many manufacturers, especially those operating on thin margins, these rising input costs can erode profitability if they cannot be passed on to consumers or international buyers. This dynamic is particularly pertinent for export-oriented industries that form the backbone of China’s manufacturing prowess.
Consumer Price Inflation (CPI) Decelerates Amidst Domestic Weakness
In stark contrast to the escalating producer prices, China’s Consumer Price Index (CPI), the primary measure of retail inflation, demonstrated a deceleration in October. The CPI rose by a modest 0.7% year-on-year, missing Reuters’ polled economist forecast of 0.8% and falling from the 0.9% recorded in September. This marked the first deceleration in consumer inflation after two consecutive months of increases, suggesting a cooling in domestic price pressures.
Delving deeper into the components, Dong Lijuan, chief statistician of the urban division at China’s National Bureau of Statistics (NBS), highlighted the complex interplay of factors influencing consumer prices. Gasoline prices remained the largest contributor to the overall increase in consumer prices, reflecting the impact of higher global oil benchmarks on domestic fuel costs. However, this upward pressure was significantly offset by a "sharper than expected fall in food prices." Food, which constitutes a substantial portion of the CPI basket in China, often experiences seasonal fluctuations, and favorable harvest conditions for key agricultural products like vegetables and grains, along with stable pork prices – a critical meat staple – likely played a crucial role in mitigating overall inflation. Furthermore, government interventions to stabilize food supply chains and ensure market abundance could have contributed to this decline.
Core inflation, which strips out volatile food and energy prices to provide a clearer picture of underlying demand-driven inflation, also saw a dip. It registered 0.8% in October, down from 1% in the preceding month. This particular metric is often viewed by central banks as a more reliable indicator of demand-side inflationary pressures, and its softening reinforces the narrative of subdued domestic consumption.
The Shadow of Weak Domestic Demand and the Property Market
The divergence between soaring producer costs and cooling consumer prices points directly to a fundamental imbalance within the Chinese economy: robust external demand coexisting with persistent weakness in domestic consumption. Zhang Zhiwei of Pinpoint Asset Management underscored this point, stating that domestic demand has been "rather weak due to the property market," identifying it as a "key reason why inflation is not picking up in China."
China’s property sector has been a significant drag on economic sentiment and growth for several years. A series of regulatory crackdowns on debt-laden developers, coupled with a broader slowdown in housing sales and construction, has left a profound mark. The sector’s woes extend beyond just property firms; it impacts household wealth, local government revenues (which rely heavily on land sales), and consumer confidence. As Zhang noted, "There’s no clear sign of stabilization [in that sector] yet," adding that this continuous uncertainty "was weighing on the household consumer confidence and local government revenue."
The psychological impact on consumers is palpable. A significant portion of Chinese household wealth is tied up in real estate. When property values stagnate or decline, and developers face liquidity crises, consumers become more cautious about spending, preferring to save rather than consume. This "wealth effect" in reverse contributes to hesitant retail sales and a general reluctance to engage in discretionary spending, thereby suppressing overall domestic demand and, consequently, consumer price inflation. Local governments, facing reduced income from land transfers, also have less fiscal capacity to invest in infrastructure or provide social welfare, further dampening economic activity.
"So the overall economic momentum has been weak and hasn’t really seen [a] clear sign of recovery," Zhang explained, succinctly capturing the prevailing sentiment among many economists. Despite targeted stimulus measures and efforts to boost consumption, the structural challenges in the property sector continue to act as a significant headwind, preventing a robust recovery in internal demand.
Economic Performance: A Mixed Picture
Despite the underlying domestic challenges, the broader Chinese economy has shown some signs of expansion in recent months. The third quarter of 2026 saw China’s economy grow "faster than expected," driven primarily by a surge in exports and the rollout of various stimulus measures. Furthermore, September recorded a "sharp beat" in retail sales, offering a glimmer of hope for a potential pickup in consumer activity, even if October’s CPI data suggests this momentum was not sustained. These positive indicators, however, appear to be heavily weighted towards external trade and specific policy-induced boosts rather than a broad-based, self-sustaining recovery in domestic demand.
The mainland Chinese CSI 300 index, a benchmark of the largest companies listed in Shanghai and Shenzhen, gained 0.56% immediately following the release of the inflation data. This modest positive reaction from the market could be interpreted in several ways. Investors might be taking comfort in the robust external demand driving PPI, viewing it as a sign of China’s continued strength in global trade. Alternatively, the cooling CPI might be seen as providing the People’s Bank of China (PBOC) with more room for potential monetary easing if domestic demand falters further, without immediately stoking inflationary fears.
Implications for Monetary Policy and Future Outlook
The divergent inflation figures present a complex dilemma for China’s central bank, the People’s Bank of China (PBOC). Typically, rising producer prices can signal future consumer inflation, as businesses eventually pass on higher costs. However, with consumer demand remaining soft and core inflation subdued, the PBOC faces a balancing act. Aggressive monetary tightening to curb PPI might further stifle domestic consumption and economic growth, exacerbating the property sector’s woes. Conversely, significant easing to stimulate domestic demand could risk stoking cost-push inflation from the factory gate, potentially squeezing corporate profits even more if price pass-through remains challenging.
Analysts are closely watching whether the PBOC will prioritize supporting domestic demand through targeted liquidity injections or modest interest rate cuts, or if it will lean towards managing potential asset bubbles and financial risks. Given the current global economic landscape, where many major central banks are still navigating high inflation and higher interest rates, China’s cautious approach to monetary policy stands out. The PBOC is likely to maintain a prudent and flexible stance, employing structural tools rather than broad-brush easing, focusing on ensuring financial stability and directing credit to strategic sectors.
Looking ahead, the trajectory of both external demand and domestic consumption will be crucial. Should global demand for Chinese exports remain strong, factory output and producer prices could continue to climb, potentially challenging manufacturers’ profitability. On the other hand, a sustained recovery in consumer confidence and a stabilization of the property market are essential for lifting consumer inflation and ensuring a more balanced and sustainable economic recovery. The government’s continued efforts to de-risk the property sector, boost household income, and enhance social safety nets will be vital in addressing the structural weaknesses underpinning the current subdued domestic demand.
Ultimately, October’s inflation data paints a picture of an economy operating on two speeds: a dynamic export engine responding to global needs, and a more subdued domestic landscape grappling with internal structural adjustments. Navigating this duality will be the central challenge for China’s economic policymakers in the coming months, as they strive to achieve sustainable growth without compromising stability.