Gilang Muhammad
The private sector in the United States demonstrated consistent job growth in October, with a notable spread across various industries, providing fresh indications of a stabilizing labor market. This assessment comes from the latest report released by ADP, the national payrolls processing firm, on Wednesday. According to ADP’s comprehensive analysis, companies collectively added 86,000 jobs during the month. This figure mirrors the downwardly revised total reported for September and slightly surpassed the Dow Jones consensus estimate of 75,000 new positions. The sustained pace of hiring suggests a resilient labor market navigating a complex economic landscape, characterized by ongoing inflationary pressures, fluctuating interest rates, and evolving consumer and business behaviors. The steadiness in job creation, particularly in a period of economic rebalancing, offers a nuanced perspective on the nation’s economic health, moving away from the rapid expansions seen in earlier post-pandemic recovery phases towards a more sustainable growth trajectory. This stability is crucial for policymakers and economists alike, as it provides a clearer picture of the underlying strength of the economy without the volatility that often accompanies periods of significant change or recovery. The report’s findings are instrumental in shaping expectations for the broader economic outlook, influencing decisions ranging from monetary policy to corporate investment strategies and individual career planning.
Steady Growth Signals Labor Market Resilience
The ADP National Employment Report, a closely watched indicator preceding the government’s official jobs data, highlighted that October’s private sector job gains were primarily concentrated within the service-providing sectors. This trend underscores the continued consumer demand and recovery in areas heavily impacted by previous economic disruptions. The robust performance in these sectors suggests that businesses are still expanding to meet customer needs, even as the overall pace of economic activity moderates. The 86,000 jobs added in October, consistent with the revised September figures, points to a labor market that, while cooling from its post-pandemic exuberance, remains fundamentally strong. Economists had projected a slightly lower figure, making the actual reported number a positive surprise that signals underlying resilience. This consistent performance, especially when compared to projections, often indicates that economic fundamentals are stronger than some pessimistic forecasts might suggest. The stability of these numbers, rather than sharp increases or decreases, is a key takeaway, implying that the labor market is finding a new equilibrium after several years of unprecedented shifts. This equilibrium is vital for fostering long-term economic stability and preventing either runaway inflation fueled by excessive demand or a sharp downturn triggered by widespread job losses.
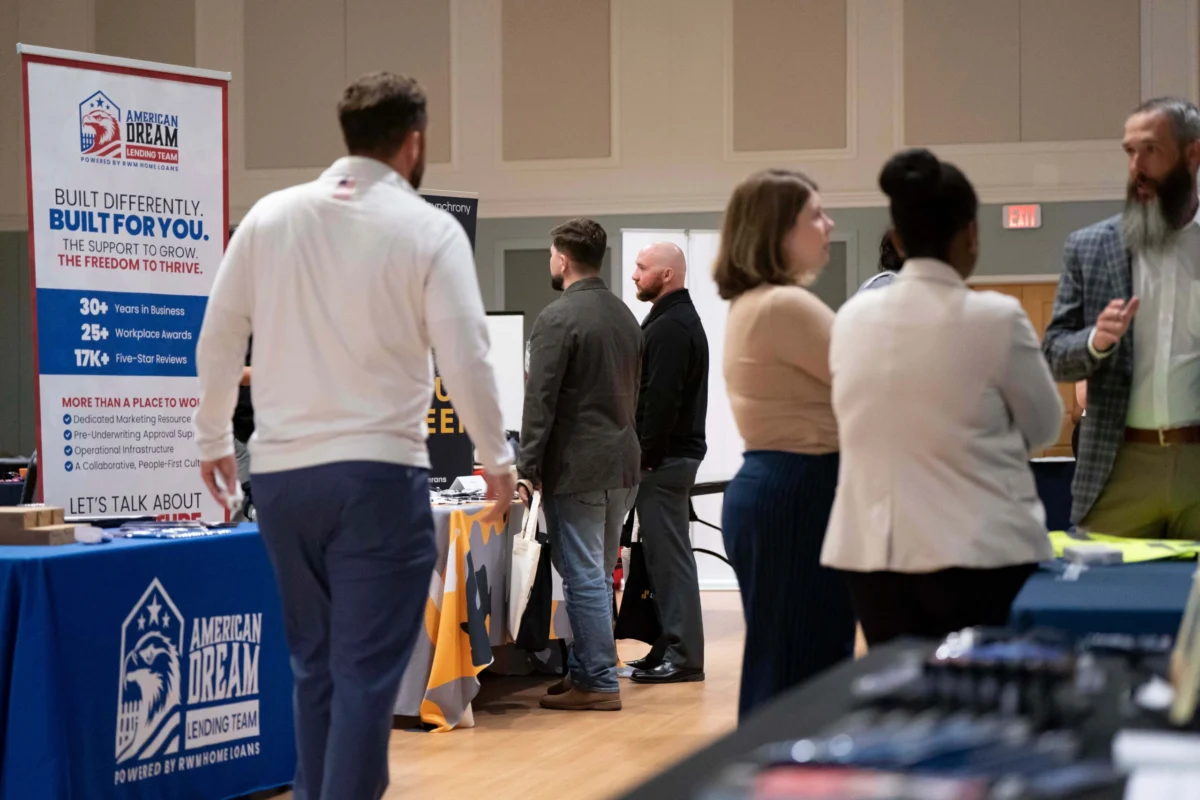
The broader context of these figures is critical. In late 2026, the U.S. economy is grappling with the aftermath of aggressive interest rate hikes by the Federal Reserve aimed at curbing inflation. A stable job market, even with moderating growth, provides a buffer against a severe economic contraction. It supports consumer confidence and spending, which are vital components of economic activity. The image of jobseekers interacting with recruiters at the NC4ME hiring event for military veterans in Wilmington, North Carolina, captured on Wednesday, October 28, 2026, serves as a tangible representation of this ongoing job market activity. Such events across the nation highlight the continuous efforts by various sectors to connect employers with talent, including specialized programs for veterans, underscoring the persistent demand for skilled labor despite overall market stabilization. These localized efforts, combined with national trends, paint a comprehensive picture of a dynamic and active job market, where opportunities are still abundant for those seeking employment or career changes.
A Closer Look at Sectoral Shifts and Disparities
A detailed breakdown of the ADP report reveals distinct patterns of job creation and contraction across different sectors, reflecting ongoing structural shifts within the economy. The service sector was the undeniable engine of growth in October, accounting for the vast majority of new positions. This dominance is not unexpected, given the U.S. economy’s heavy reliance on service industries. Within this broad category, several sub-sectors stood out. Trade, transportation, and utilities led the charge with an impressive 39,000 new jobs. This robust growth can be attributed to several factors, including sustained e-commerce activity, ongoing supply chain adjustments, and preparations for the upcoming holiday shopping season, which typically sees a surge in logistics and retail employment. The transportation sector, in particular, continues to adapt to evolving consumer delivery expectations and global trade dynamics.
Education and health services followed closely, adding 28,000 positions. This sector consistently demonstrates resilience, driven by demographic shifts, an aging population requiring more healthcare services, and sustained demand for educational institutions. The essential nature of these services often shields them from economic downturns that might impact other sectors more severely. Leisure and hospitality, a sector that experienced significant upheaval during the pandemic, continued its recovery trajectory by contributing 19,000 new jobs. While not as explosive as previous recovery periods, this steady growth indicates ongoing consumer confidence in travel, dining, and entertainment, even with potential budget constraints. Other sectors also showed positive, albeit smaller, gains: financial activities added 15,000 jobs, construction saw an increase of 13,000, and other services contributed 10,000 positions. The growth in construction, for instance, suggests continued investment in infrastructure and housing, despite higher interest rates.
However, the picture was not uniformly positive. Some sectors experienced notable declines, highlighting the uneven nature of economic adjustments. Professional and business services recorded a significant loss of 27,000 jobs. This contraction could signal a slowdown in corporate spending on consulting, administrative, and technical services, often an early indicator of businesses tightening their belts in anticipation of slower economic growth or increased efficiency drives. Natural resources and mining also saw a reduction of 8,000 jobs, a sector often susceptible to commodity price fluctuations and environmental policy shifts. Perhaps most interestingly, information services, a sector at the forefront of technological advancement, shed 2,000 jobs. This decline is particularly noteworthy as it could be an early signal of the impacts of artificial intelligence (AI) integration, where automation and efficiency gains might be leading to a reduction in certain types of roles, even as new AI-related jobs emerge. This nuanced sectoral performance underscores the ongoing transformation of the U.S. labor market, where some industries thrive while others face challenges adapting to new economic realities and technological innovations.
Wage Dynamics: Job Changers Lead the Charge Amid Rising Mobility
The ADP report also shed significant light on wage dynamics, revealing a continued upward trend in salaries, particularly for workers actively seeking and securing new employment. This distinction between job changers and job stayers offers crucial insights into labor market fluidity and the ongoing competition for talent. Workers who changed jobs experienced a robust 4.8% annual gain in their pay. This substantial increase suggests that employers are willing to offer higher compensation packages, including bonuses, overtime, and increased hours, to attract new talent in a still-competitive labor market. As ADP’s chief economist, Nela Richardson, noted, "Employers of all sizes were hiring last month, and our data suggests that job-changers were lured by a combination of bonuses, overtime, and more hours in addition to higher base pay." Richardson further emphasized the significance of this trend, stating, "Taken together, earnings growth for these workers hit its fastest pace since March 2024," highlighting a renewed vigor in wage competition for new hires.
This trend of elevated pay for job changers is strongly correlated with increased labor market mobility, a key indicator of worker confidence and opportunity. A separate report released on Tuesday by the Bureau of Labor Statistics (BLS) provided supporting evidence for this mobility, indicating that the number of people quitting their jobs reached its highest level since March 2025. A high "quits rate" is generally viewed as a positive sign, as it suggests workers are confident enough in their prospects to leave their current positions, often for better pay, benefits, or career advancement opportunities elsewhere. This mobility fuels the wage gains for job changers, as businesses vie for available talent, pushing up compensation offers.
For the broader workforce, the report showed that workers overall experienced a 3.2% base pay gain, while gross pay, which includes bonuses and overtime, increased by 4.7% annually. Those who chose to stay in their current jobs saw a more modest, but still positive, 3% rise in their pay. The differential between job changers and job stayers underscores a persistent challenge for employers: retaining existing talent while also attracting new hires. Businesses are often forced to offer more competitive packages to external candidates, which can create internal wage compression issues if not managed carefully. The overall wage growth figures are closely watched by economists and policymakers, particularly the Federal Reserve, as they represent a critical factor in the inflation outlook. While strong wage growth supports consumer purchasing power and economic activity, excessively rapid increases can contribute to inflationary pressures, potentially complicating the Fed’s efforts to achieve its 2% inflation target. The current pace of wage growth, particularly for job changers, suggests that while the labor market is stabilizing, inflationary pressures stemming from labor costs remain a consideration.
The Broader Economic Tapestry: Context and Chronology
The ADP report for October 2026 arrives amidst a crucial week for economic data releases, providing a timely precursor to the more comprehensive government statistics. This chronological sequence of data offers a layered perspective on the state of the U.S. labor market. The week commenced with the Bureau of Labor Statistics (BLS) releasing its Job Openings and Labor Turnover Survey (JOLTS) on Tuesday, which, as mentioned, highlighted increased labor market mobility with a significant rise in the number of people quitting their jobs. This report set the stage, signaling a dynamic environment where workers felt empowered to seek out better opportunities. The ADP report, published on Wednesday, then provided the first detailed look at private sector job creation for October, offering a forward-looking glimpse before the official government figures.
This sequence is critical for economists and analysts, who use ADP’s data to refine their forecasts for the upcoming BLS nonfarm payrolls report. The ADP report, while independently derived from a vast dataset of payroll transactions, is often seen as a bellwether, providing directional insight into the broader labor market trends. The report’s consistency with September’s revised figures, coupled with its slightly exceeding Dow Jones estimates, reinforces the narrative of stabilization rather than accelerating growth or sharp deceleration. This stability is a welcome sign in an economy that has spent much of the past few years grappling with rapid shifts—from pandemic-induced lockdowns and massive job losses to a swift recovery marked by labor shortages and high inflation.
Looking back, September 2026 had shown a modest growth of 29,000 jobs, indicating a cooling trend from earlier in the year. October’s 86,000 figure, therefore, represents an acceleration from September, but one that aligns with a more moderate, sustainable pace rather than a return to the explosive growth of 2021-2022. This moderation is precisely what many economists and Federal Reserve officials have been hoping for, as it suggests the economy is slowing enough to ease inflationary pressures without tipping into a recession. The backdrop for all this data remains the Federal Reserve’s ongoing battle against inflation, with interest rates held at elevated levels to cool demand. A balanced labor market, with steady job creation and moderating but still positive wage growth, is a key component of the "soft landing" scenario, where inflation is brought under control without triggering widespread unemployment. The NC4ME hiring event in Wilmington, North Carolina, on October 28, 2026, featuring jobseekers engaging with recruiters, exemplifies the grassroots level of ongoing labor market activity, even as national data points to broader trends of stabilization. Such initiatives underscore the persistent demand for talent, particularly for specific demographics like military veterans, reinforcing the notion that opportunities remain available across the spectrum of the workforce.
Workforce Demographics and Business Size Impact
The ADP report offers valuable granularity by categorizing job creation based on company size, providing further insights into which segments of the private sector are driving employment growth. This breakdown helps analysts understand the differing dynamics at play across the business landscape. In October, mid-sized businesses, defined as those employing between 50 and 499 workers, were the leading contributors to job growth, adding a significant 33,000 positions. This strong performance by mid-sized firms is often seen as a positive indicator for the broader economy. These businesses are typically agile enough to respond quickly to market demands, yet large enough to have established operational structures and contribute substantially to overall employment. Their sustained hiring can reflect confidence in their growth prospects and an ability to navigate economic uncertainties more effectively than smaller, more vulnerable enterprises, or to find niches that larger corporations might overlook.
Large businesses, those with 500 or more employees, also demonstrated healthy hiring activity, increasing their payrolls by 24,000 jobs. While a smaller contribution than mid-sized firms in this particular month, the consistent job creation by large corporations is crucial for overall economic stability. These companies often represent established industries and global operations, and their willingness to expand their workforce signals confidence in broader economic conditions and long-term investment strategies. Their hiring patterns can also be influenced by factors such as mergers and acquisitions, technological advancements, and shifts in consumer demand at scale.
Small firms, encompassing businesses with fewer than 50 workers, added 28,000 jobs in October. This segment of the economy is often considered the backbone of job creation and innovation, though it can also be more susceptible to economic headwinds, such as rising operating costs, interest rates, and labor expenses. The fact that small businesses continued to add a substantial number of jobs suggests a degree of resilience and entrepreneurial spirit persists, even in a moderating economic environment. Their collective contribution underscores the importance of local economies and the ongoing formation and expansion of new ventures. The balanced distribution of job gains across all three size categories—mid-sized leading, followed by small and large businesses—indicates a broad-based demand for labor across the private sector. This diversified growth pattern suggests that the current economic expansion is not solely reliant on one particular type of business, but rather reflective of a healthier, more widespread demand for labor across the U.S. economy. Such a distribution tends to make job growth more robust and less vulnerable to shocks affecting specific segments of the business world.
Expert Analysis and Market Implications
The ADP report for October 2026, signaling steady private sector job growth, has garnered significant attention from economic analysts and market participants, prompting a range of interpretations regarding its implications for monetary policy, inflation, and the broader economic outlook. Economists widely interpret the report as further evidence that the U.S. labor market is undergoing a "soft landing"—a scenario where inflationary pressures ease without triggering a severe recession and widespread job losses. The sustained, albeit moderating, pace of hiring, coupled with the nuanced wage dynamics, provides crucial data points for this ongoing assessment.
For the Federal Reserve, these figures are particularly salient. The central bank has repeatedly emphasized its data-dependent approach to monetary policy, with labor market strength being a key determinant of future interest rate decisions. The steady job growth, combined with continued wage increases (especially for job changers), suggests that while the labor market is cooling, it remains tight enough to potentially contribute to inflationary pressures. Analysts suggest that the Fed will likely view these numbers with cautious optimism. While the moderation from previous years is positive, the persistent wage growth, particularly the 4.8% annual gain for job changers, indicates that the labor cost component of inflation remains a factor. This could mean that the Fed maintains its hawkish stance longer, or at least refrains from signaling imminent rate cuts, until inflation definitively moves closer to its 2% target. The data could reinforce the Fed’s "higher for longer" interest rate narrative, as it seeks to ensure that demand-side pressures in the labor market are sufficiently subdued.
From a market perspective, stable job growth typically supports consumer confidence and spending, which are vital for economic expansion. A robust labor market ensures that households have income to spend, driving demand for goods and services. However, the slightly higher-than-expected job growth, combined with elevated wage gains, could also fuel concerns among some investors about persistent inflation, potentially leading to volatility in bond markets and influencing equity market valuations. Companies, on the other hand, might view the steady hiring as a sign of continued economic activity, encouraging further investment and expansion. However, they also face the challenge of managing rising labor costs, which could impact profit margins. The sectoral shifts, with declines in professional services and information, could prompt businesses to re-evaluate their staffing strategies and invest further in automation and efficiency-enhancing technologies, including AI, to mitigate rising wage pressures.
Overall, the ADP report paints a picture of an economy that is adjusting to higher interest rates and evolving global dynamics, yet still demonstrating underlying strength. The "stabilization" narrative is gaining traction, suggesting that the most volatile periods of post-pandemic recovery and inflation shock may be receding. However, the implications of wage growth for inflation remain a central concern, keeping the Federal Reserve on high alert and influencing expectations for the future trajectory of monetary policy. The balanced job growth across different business sizes further adds to the robustness of the economic picture, indicating broad-based resilience rather than growth concentrated in just a few areas.
Looking Ahead: The Anticipated BLS Report
As the week progresses, all eyes are now turning to the official nonfarm payrolls report from the Bureau of Labor Statistics (BLS), scheduled for release on Friday. This government report is widely considered the definitive measure of U.S. employment and wage trends, carrying significant weight with financial markets, policymakers, and the public alike. Economists surveyed by Dow Jones are projecting that the BLS report for October will show a gain of 59,000 jobs. This forecast represents a notable increase from September’s modest growth of 29,000 jobs, suggesting an expected acceleration in overall employment figures. However, it also implies a more conservative estimate compared to the 86,000 jobs reported by ADP for the private sector.
The difference in estimates between ADP and BLS is not uncommon and stems from variations in their methodologies and data sources. ADP primarily tracks payroll data from its vast client base, encompassing millions of employees, offering a comprehensive view of private sector employment. The BLS, on the other hand, conducts two extensive surveys: the establishment survey, which polls businesses about their payrolls (similar to ADP but with different sampling and estimation techniques), and the household survey, which polls households about their employment status, providing insights into unemployment rates, labor force participation, and self-employment. While both reports aim to measure employment trends, their specific scopes and calculations can lead to divergences in their monthly figures. For instance, the BLS report includes government jobs, which are excluded from ADP’s private sector focus.
Market participants and economists will be scrutinizing the BLS report for several key metrics beyond the headline job growth number. The unemployment rate, average hourly earnings (a crucial inflation indicator), and the labor force participation rate will be closely analyzed to gauge the overall health and tightness of the labor market. A higher-than-expected job gain from the BLS could reinforce the narrative of a robust economy, potentially leading to increased expectations for the Federal Reserve to maintain its restrictive monetary policy. Conversely, a significantly lower figure could signal a more rapid cooling of the labor market than anticipated, potentially prompting discussions about future policy adjustments. The BLS report will also provide greater detail on sectoral employment, allowing for a more granular comparison with the trends identified by ADP, particularly concerning the shifts in service industries and the declines in professional and information services. Ultimately, Friday’s BLS report will serve as the conclusive assessment of October’s labor market performance, either confirming the signals of stabilization and resilience from the ADP report or presenting a divergent picture that could reshape economic expectations for the coming months.
The October 2026 job data, spearheaded by ADP’s report, paints a picture of a U.S. labor market that is steadily finding its footing. The consistent job growth, predominantly in the service sector, coupled with significant wage gains for job changers, underscores an economy that, while moderating, retains considerable underlying strength and dynamism. This stabilization is a critical development for policymakers aiming to achieve a "soft landing," balancing inflation control with sustained economic activity. As the week culminates with the eagerly awaited BLS report, the full scope of October’s labor market performance will become clearer, providing definitive insights that will shape monetary policy decisions, influence business strategies, and impact the financial well-being of millions of Americans in the months ahead.