Gilang Muhammad
The United States is grappling with a rapidly escalating fiscal challenge, marked by long-term bond yields climbing above 5% and a staggering $2 trillion annual deficit, providing a stark preview of what a full-blown U.S. debt crisis could entail. While a true emergency, characterized by a loss of global investor confidence and a severe economic downturn, is not yet "baked in," the current trajectory raises profound concerns. With the nation poised for midterm elections on November 3, 2026, which are widely expected to solidify divided government, the path forward to address the nation’s worrying fiscal course remains profoundly unclear, threatening to delay critical solutions for years.
A Looming Fiscal Storm: The Confluence of Debt and Rates
The confluence of elevated interest rates, exacerbated by a relentless flood of federal debt issuance, is beginning to exert significant pressure across various sectors of the economy. These rates, in turn, threaten to compound the government’s own debt servicing costs, creating a potentially vicious cycle. The national debt has surged past the $40 trillion mark in 2026, a figure that continues to grow at an alarming pace. The Congressional Budget Office (CBO), the non-partisan agency responsible for providing economic and budget information to Congress, has repeatedly warned that this escalating debt burden poses substantial risks to the nation’s long-term economic and fiscal health. These risks include higher interest rates, increased borrowing costs for the government, a diminished ability to respond to future economic downturns or national emergencies, and a potential reduction in national savings and investment.
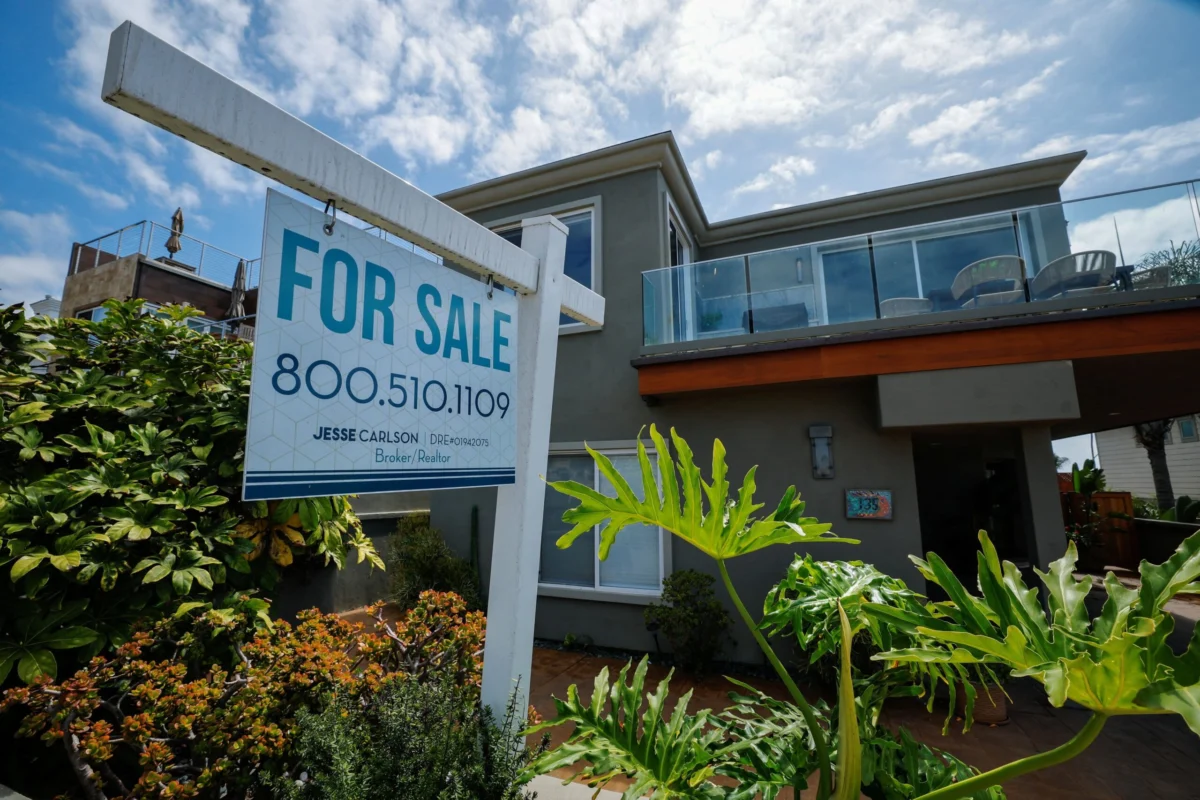
One of the most immediate and visible casualties of this fiscal environment is the housing market. As the average 30-year fixed-rate mortgage hovers around a formidable 7.5%, affordability has plummeted for prospective homebuyers. Data released by Redfin on September 30, 2026, revealed that pending home sales experienced a 4% decline in September, marking the most significant monthly drop in three years. This slowdown is a direct consequence of mortgage rates tracking the benchmark 10-year Treasury yield, which surged by 114 basis points (or 1.14 percentage points) from the end of February to midday Friday, September 27, 2026, when it traded at 5.1%. For context, just a few years prior, during periods of quantitative easing and lower inflation, the 10-year Treasury yield often lingered below 2-3%, illustrating the dramatic shift in borrowing costs.
The Drivers Behind Surging Yields
Several interconnected factors are propelling the 10-year Treasury yield to these elevated levels. A critical geopolitical event that significantly impacted market sentiment was the outbreak of war with Iran on February 28, 2026. This conflict immediately sent shockwaves through global energy markets, leading to sharp increases in oil and diesel prices. Bond traders, in response, began demanding higher yields to account for the heightened inflation risk and the increased likelihood that central banks, including the Federal Reserve, would be compelled to raise interest rates further to curb inflationary pressures. The expectation of persistent inflation erodes the real return on fixed-income investments, making higher nominal yields necessary to attract buyers.
Beyond geopolitical tensions, the sheer volume of U.S. government debt being issued is a primary concern. Investors are increasingly demanding greater compensation to hold longer-term bonds, in part due to the expectation that the U.S. government will continue to inundate the market with new debt. This dynamic creates a supply-demand imbalance, pushing yields upward. Furthermore, the market for corporate debt, particularly in the burgeoning artificial intelligence (AI) sector, is intensifying the competition for capital. Companies are issuing hundreds of billions in new debt to finance the massive infrastructure required for AI development, drawing capital that might otherwise flow into government bonds. Global investors, seeking low-risk, long-term debt, also have increasingly attractive alternatives to the U.S. Treasury market, including sovereign bonds from other developed nations that may offer competitive yields or perceived lower fiscal risk. This diversification away from U.S. Treasuries by international buyers further reduces demand, contributing to higher yields.
A Chronology of Fiscal Erosion (2025-2026)
The current fiscal predicament is not an overnight phenomenon but the culmination of years of accumulating debt and a series of recent events that have accelerated the trend.
- Late 2025: Economic forecasts from the CBO and other institutions begin to paint a concerning picture of future deficits, even before the full impact of geopolitical events and rising interest rates became apparent. Warnings about the long-term sustainability of the national debt become more frequent.
- February 28, 2026: The outbreak of hostilities with Iran significantly alters the global economic landscape. Oil prices spike, and inflationary expectations surge, immediately impacting bond markets as investors price in higher risk and potential Fed tightening.
- Spring/Summer 2026: As the geopolitical situation remains tense, federal spending continues, leading to increased Treasury issuance. Concurrently, the booming AI sector drives unprecedented corporate debt issuance, creating a "crowding out" effect in capital markets.
- June 24, 2026: Treasury Secretary Scott Bessent publicly states that the U.S. ought to target a deficit lower than 4% of its gross domestic product (GDP) by the end of President Donald Trump’s term. This statement acknowledges the severity of the deficit problem but sets an ambitious target given existing trends.
- September 2026: The full effects of higher rates become evident in the housing market, with mortgage rates reaching 7.5% and pending home sales dropping by 4%. The 10-year Treasury yield crosses the 5% threshold, reaching 5.1% by mid-September, highlighting the escalating cost of government borrowing.
- September 27, 2026: The U.S. Treasury releases its final deficit figures for the 2026 fiscal year, revealing a deficit of $1.992 trillion. This represents a 12% increase from the previous year and amounts to approximately 6.2% of estimated third-quarter GDP, significantly above Bessent’s stated target.
- November 3, 2026: The upcoming midterm elections are anticipated to result in a divided government, likely exacerbating the political challenges of implementing comprehensive fiscal reforms.
The Historical Context of U.S. Debt
The trajectory of U.S. national debt has been a persistent concern for decades, but its recent acceleration is particularly striking. Historically, the national debt surged during major wars, such as World War II, before declining in the post-war boom. However, since the 1980s, the debt has seen a more sustained upward trend, fueled by a combination of tax cuts, increased spending on defense and social programs, and economic crises. The 2008 financial crisis and the subsequent Great Recession necessitated massive government interventions, adding trillions to the debt. More recently, the COVID-19 pandemic triggered unprecedented fiscal stimulus, pushing the national debt to new heights. The shift from a sustained period of historically low interest rates, which made servicing this debt relatively inexpensive, to the current environment of higher rates is a critical inflection point. This change means that even maintaining the existing debt burden becomes significantly more costly, creating a feedback loop where higher interest payments contribute to larger deficits.
Official Responses and Proposed Solutions
Treasury Secretary Scott Bessent has articulated a strategy focused on economic growth as the primary means to address the debt. "My view is that we’ve got this mountain of debt, and we have to grow our way out of it," Bessent stated in Dallas last month. He, along with other administration officials, has frequently highlighted artificial intelligence as a crucial source of future economic expansion, capable of driving productivity gains and increasing tax revenues.
However, many independent analysts and non-partisan organizations remain skeptical about growth alone solving the problem. The Committee for a Responsible Federal Budget (CRFB), a research group advocating for balanced budgets, estimates that it would require a decade of sustained 7.2% annual GDP growth to balance the budget purely through economic expansion. This rate of acceleration, implying an almost unimaginable transformation of the economy from the recently revised second-quarter annualized growth rate of 2.2% (up from 1.5%), underscores the enormity of the challenge and the unlikelihood of growth alone being sufficient.
The CBO’s projections further highlight the precarious position. The agency estimates that if interest rates remain just half a percentage point above its expectations, the cumulative deficit over the next 10 years would increase by an additional $1.9 trillion. Should rates overshoot by 1.5 percentage points, an alarming $6 trillion would be added to future deficits. The CBO currently expects the 10-year Treasury to average 4.3% over that period, compared to the current 5.1%. These alarming scenarios would require rates across the economy to remain elevated for years, locking in higher debt servicing costs.
The Impasse of Political Gridlock
While economic solutions are debated, the political landscape presents an even more intractable problem. President Donald Trump is entering the final two years of his presidency, a period often characterized by efforts to define a lasting legacy. However, there are few indications that deficit reduction is a priority for his administration. Instead, campaign pledges, such as providing $5,000 checks to every adult American citizen if Republicans achieved a sweeping electoral victory, signal a continued emphasis on spending rather than fiscal consolidation.
The upcoming midterms are widely forecast to deliver a setback for the Republican party, with many analysts predicting they will lose control of at least the House of Representatives, and potentially the Senate as well. Historically, periods of divided government have sometimes forced bipartisan compromises on difficult issues. However, the current political climate is marked by deep animosity and vastly divergent starting points, making such cooperation seem increasingly remote. For instance, Representative Hakeem Jeffries, who is widely expected to become the next Democratic House Speaker, has publicly stated his intention to reverse the $1 trillion in healthcare cuts enacted last year as part of President Trump’s signature legislative package. Such proposals would directly counteract efforts to rein in spending.
This deep partisan divide extends beyond specific policy proposals, manifesting in a broader unwillingness to engage in the painful but necessary choices required to address the debt. Fiscal responsibility often necessitates a combination of increased revenues (taxes) and reduced spending (on entitlement programs like Social Security and Medicare, or discretionary spending). Both options are politically fraught and typically met with fierce resistance from one party or the other.
Broader Implications and the Path Ahead
The current fiscal strain has far-reaching implications beyond just government budgets. Higher interest rates dampen private sector investment, as the cost of borrowing for businesses increases, potentially slowing economic growth and job creation. Consumers face higher costs for mortgages, car loans, and credit card debt, eroding purchasing power and potentially leading to a slowdown in consumption. The burden of this accumulating debt also falls disproportionately on future generations, who will inherit a nation with less fiscal flexibility and potentially fewer resources for public investments.
Globally, the fiscal health of the United States underpins its economic influence and geopolitical standing. A perceived weakening of U.S. fiscal stability could erode confidence in the dollar as the world’s reserve currency and diminish the nation’s ability to project power and leadership on the international stage.
The prospect of a "full-on debt crisis" remains further out, but the current conditions serve as a stark warning. Such a crisis would manifest as a dramatic loss of confidence in U.S. government solvency, leading to a precipitous spike in debt yields, a mass exodus of global investors selling dollar-denominated assets, and a sharp devaluation of the currency. In such a scenario, both the Treasury and the Federal Reserve would find their tools severely limited, potentially leading to hyperinflation, an inability to fund essential government operations, and a deep, prolonged recession.
For now, while higher yields are indeed attracting some investors to U.S. government bonds, signaling that expensive borrowing is not synonymous with an immediate crisis, the underlying message is clear: economics alone cannot rectify this problem. The complex interplay of spending, taxation, and interest rates requires difficult political decisions. If Americans hope to forestall a full-blown debt crisis, the imperative is to find a way to bridge the profound political divides and forge a consensus on fiscal sustainability. Without such a resolution, the nation risks drifting further down a worrying trajectory, with potentially catastrophic consequences for its economic future and global standing.