 Gilang Muhammad
The Federal Reserve finds itself at a critical juncture, with upcoming economic data expected to provide little solace for those hoping for a pause in the aggressive interest rate hiking cycle. Anticipated figures for the personal consumption expenditures (PCE) price index, the central bank’s preferred inflation gauge, are poised to reveal persistent price pressures coupled with an unexpectedly resilient consumer base, suggesting that the path toward the Fed’s 2% inflation target remains arduous and potentially requires further monetary tightening.
On Wednesday, October 2, 2026, the Bureau of Economic Analysis (BEA) is slated to release the PCE price index for August, with economists surveyed by Dow Jones projecting a 0.3% increase for both the all-items and core PCE levels. Core PCE, which strips out volatile food and energy components, is closely watched by policymakers for underlying inflationary trends. On an annual basis, these measures are expected to show increases of 3.7% and 3.3%, respectively. These figures, consistent with July’s readings, remain stubbornly above the Federal Reserve’s long-term 2% objective, reinforcing concerns that inflation is becoming more entrenched in the economy.
The Fed’s Unwavering Focus on Price Stability
For the Federal Reserve, the PCE index serves as a crucial barometer of price stability, forming the bedrock of its monetary policy decisions. The central bank operates under a dual mandate from Congress: to foster maximum employment and maintain price stability. In an environment where inflation significantly outpaces its target, the Fed’s primary focus shifts decisively towards curbing price pressures, often at the risk of tempering economic growth.
Dan North, senior economist at Allianz Trade, articulated the prevailing sentiment among analysts: "The Fed is going to look at this and say, ‘Hey, you know, the core is not moving, and I don’t have any expectations or anything to believe that it’s going to start going back down in any sort of convincing way.’ It’s still way above target… So I think it’s really embedded in there to the extent that the Fed is not going to be able to ignore it or explain it away." This assessment underscores the challenge facing the Federal Open Market Committee (FOMC) as it navigates a complex economic landscape.
A History of Aggressive Tightening
The current cycle of interest rate hikes commenced in March 2022, marking a decisive pivot from an era of historically low rates designed to stimulate the economy post-pandemic. Initially aimed at combating what was then perceived as "transitory" inflation, the Fed’s policy response has evolved into a sustained campaign of tightening as inflationary pressures proved more durable than anticipated. The September 2026 FOMC meeting saw the committee approve a quarter-percentage-point rate increase, bringing the central bank’s benchmark borrowing rate into a range of 3.75%-4%. This decision was accompanied by updated economic projections, with all but two of the 18 FOMC officials forecasting at least one additional rate hike by the end of 2026, and a consensus PCE inflation outlook that was notably elevated.
Federal Reserve Chairman Kevin Warsh, speaking at his news conference following the September meeting, painted a picture of an economy that, despite the aggressive rate hikes, remains robust. He cited strong hiring data, healthy business investment, and solid private sector earnings as evidence of the economy’s good health. Warsh’s assessment that he would be "hard pressed to describe broad financial conditions as restrictive" is particularly significant, as financial conditions are a key input for the Fed’s calibration of rate policy. This suggests that the current level of interest rates and other financial metrics may not yet be exerting sufficient downward pressure on aggregate demand to bring inflation under control.
Divergent Views, Shared Concerns Among Policymakers
While the FOMC generally operates with a unified front, individual members often express nuanced perspectives on the economy’s trajectory and the appropriate path for monetary policy. These differing viewpoints provide valuable insight into the internal deliberations of the central bank.
Fed Governor Michael Barr, for instance, offered a more direct assessment of the challenges to the inflation target during a Tuesday speech. He pointed to the compounding effects of global trade tensions, specifically tariffs, and the "prolonged war with Iran" as significant factors that have "knocked us off course on our progress toward our 2% goal." Barr’s concern was palpable as he stated, "I don’t yet see a clear trend toward a timely return to 2%." Consequently, he reiterated his belief that "further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion," emphasizing the Fed’s commitment to supporting "sustainable, durable growth in support of maximum employment, and price stability is crucial to that." While not specifying a level, his remarks strongly suggested an openness to continued rate increases.
New York Fed President John Williams, a highly influential voice on the FOMC, introduced another contemporary factor contributing to persistent inflation: the burgeoning "artificial intelligence buildout" and the associated surge in demand for related goods and services. The rapid expansion of AI infrastructure requires significant investment in advanced semiconductors, data centers, and energy, all of which can exert upward pressure on prices across various sectors. However, Williams also offered a glimmer of optimism, noting that "other indicators are more encouraging regarding the inflation outlook." He specifically highlighted decelerating prices for housing services and an absence of evidence that the labor market is currently "adding to inflationary pressures." Furthermore, Williams observed that the pressure on goods prices stemming from tariffs has "largely abated."

From a policy perspective, Williams adopted a somewhat more dovish tone than Barr, stating that "there is no need for urgency, and we have time to gather more information." This suggests a preference for a data-dependent approach, allowing the Fed to observe upcoming economic releases before committing to further action. Nevertheless, even Williams acknowledged the likelihood of "one further upward adjustment" of rates potentially being necessary before the end of the year, underscoring the broad consensus within the Fed that inflation remains a significant threat.
Underlying Drivers of Entrenched Price Pressures
The inflation story of 2026 is a complex tapestry woven from geopolitical events, technological advancements, and domestic demand dynamics. The "prolonged war with Iran," for instance, has had far-reaching implications beyond immediate conflict zones. It has disrupted global supply chains, particularly in energy markets, leading to volatility in oil and gas prices. This, in turn, translates into higher transportation costs for businesses and increased expenses for consumers at the pump, feeding into broader inflationary pressures. Similarly, tariffs, while some pressures may be abating according to Williams, have historically increased the cost of imported goods, pushing up domestic prices.
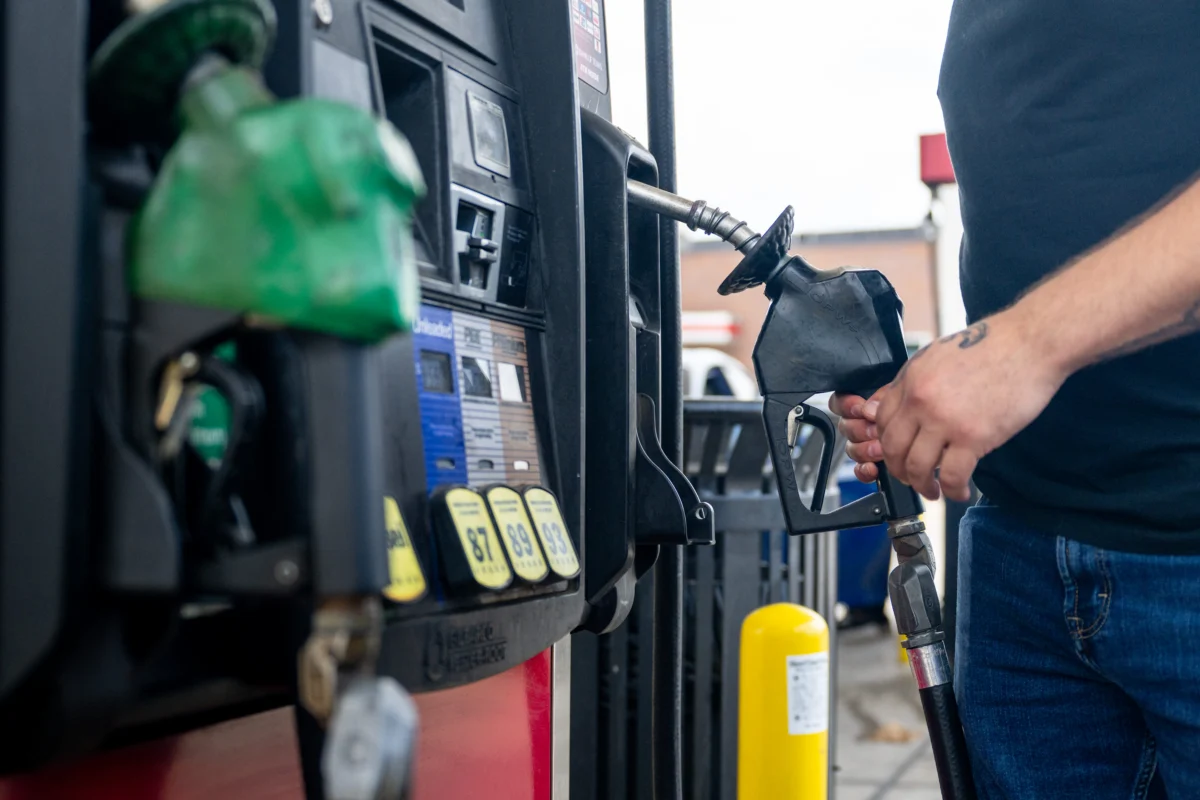
The "artificial intelligence buildout" represents a newer, demand-side driver of inflation. The massive investment required for AI development, from advanced computing chips to server farms and specialized talent, creates intense demand for these resources. This demand can outstrip supply, leading to price increases that ripple through the technology sector and beyond. The energy sector, too, has seen renewed upward pressure, partly due to geopolitical events and partly due to strong global demand. The "surge in gas prices" directly impacts household budgets and the operating costs of businesses, contributing to the stickiness of overall inflation.
Consumer Resilience Amid Headwinds
Perhaps one of the most surprising aspects of the current economic environment is the enduring resilience of the American consumer. Despite "faltering sentiment readings" and persistent price increases that erode purchasing power, consumers continue to spend. The Street consensus anticipates that personal consumption expenditures, a measure of consumer spending on goods and services, rose 0.8% in August, a significant acceleration from the 0.2% increase seen in July. This robust spending is, at least in part, attributed to another surge in gas prices, which naturally inflates spending figures for essential items.
Data from Bank of America further corroborates this trend, reporting that combined debit and credit card spending rose 6.9% from a year ago for the week ended September 19. While a substantial portion of this bump, 26.5%, was attributable to gasoline purchases, even when excluding gas, spending still increased by a healthy 5.7%. This indicates that consumers are not merely spending more on necessities due to higher prices but are also maintaining strong discretionary spending. This continued willingness and ability to spend, even in the face of elevated inflation, poses a dilemma for the Fed. It suggests that the current level of interest rates may not yet be sufficiently restrictive to cool aggregate demand and bring inflation down to target. Sources of this resilience could include accumulated savings from the pandemic era, robust wage growth in certain sectors, and the wealth effect from still-elevated asset prices. However, it also raises questions about the sustainability of this spending, especially if it is increasingly financed through credit, potentially leading to higher household debt levels.
Methodological Revisions and Their Nuanced Impact
Adding a layer of complexity to the inflation picture are upcoming methodological revisions by the Bureau of Economic Analysis (BEA). Wednesday’s release will incorporate retroactive adjustments to how the BEA measures prices for certain services, specifically legal services, software and computer accessories, and portfolio management services, going back to 2021. The expected outcome of these revisions is a downward adjustment of annual PCE inflation readings for July by two or three tenths of a percentage point, potentially bringing the 12-month reading down to 3%, according to various Wall Street estimates.
While such revisions might offer a "better rearview mirror look" at past inflation, they do not necessarily alter the "road ahead." As Goldman Sachs analysts noted, the next couple of months of inflation data are still expected to be "somewhat less favorable before a more benign trend reasserts itself." This distinction is crucial for the Fed, which must base its forward-looking policy decisions on the most current and projected economic conditions, rather than solely on revised historical data. The revisions might suggest that past inflation was slightly less severe than previously thought, but they do not change the reality of ongoing price pressures and strong consumer demand.
Market Expectations and the Path Forward
The combination of persistent inflation and robust consumer spending leaves little doubt in the minds of market participants regarding the Federal Reserve’s likely next steps. Markets are currently pricing in a strong probability of another interest rate hike in October, with a subsequent increase anticipated in either December or January, according to the CME FedWatch Tool. This aggressive outlook reflects the belief that the Fed remains resolute in its commitment to achieving price stability, even if it means pushing borrowing costs higher and potentially risking a slowdown in economic activity.
The trajectory of interest rates has significant implications across the economy. Higher rates translate to more expensive borrowing for businesses, potentially dampening investment and hiring. For consumers, mortgage rates climb, making housing less affordable, and the cost of other loans, such as auto loans and credit card debt, increases. While the Fed’s primary objective is price stability, policymakers are acutely aware of the risk of overtightening, which could trigger a recession and undermine the goal of maximum employment. The delicate balancing act between taming inflation and preserving economic growth will continue to define the Fed’s actions in the coming months. The upcoming PCE data will serve as another critical piece of the puzzle, guiding the central bank’s next moves in its ongoing battle against inflation.