Gilang Muhammad
United States wholesale prices experienced an unexpected surge in August, according to a report released on Thursday, a development poised to significantly influence the Federal Reserve’s forthcoming interest rate deliberations. The Producer Price Index (PPI), a comprehensive measure of final demand costs for goods and services across the economy, advanced by a seasonally adjusted 0.4% for the month. This increase was precisely in line with the consensus forecast from Dow Jones economists, as reported by the Bureau of Labor Statistics. However, the year-over-year figure presented a more concerning picture, with the PPI accelerating to 5.4%, firmly entrenched above the Federal Reserve’s long-term 2% inflation target and exceeding market expectations by 0.1 percentage point. This latest data point, building on a slightly upwardly revised 0.1% increase in July (initially reported as no change), underscores persistent inflationary pressures within the supply chain, complicating the central bank’s delicate balancing act between controlling prices and supporting economic growth.
The Latest Data: August PPI Overview and Key Drivers
The August PPI report serves as a critical barometer of inflation at the wholesale level, reflecting the prices that producers receive for their output. Its movements often foreshadow shifts in consumer prices, making it a closely watched indicator by policymakers and market participants alike. The headline 0.4% monthly increase in final demand prices was primarily propelled by a notable rise in goods costs, particularly within the energy sector. This upward trajectory contrasts with the more subdued performance seen in July, which, despite its revision, suggested a temporary cooling of inflationary forces. The annual PPI rate of 5.4% is particularly significant as it remains substantially elevated, more than double the Fed’s mandated target, signaling that the journey back to price stability is proving more protracted than initially hoped.
Dissecting the Core Inflation Metrics: While the headline PPI captured immediate attention, economists also meticulously scrutinize "core" measures, which strip out volatile components like food and energy to provide a clearer signal of underlying inflationary trends. In August, the core PPI, excluding food and energy, rose by 0.2%, slightly below the forecast of a 0.3% increase. Another refined measure, core PPI less trade services, advanced by 0.3%, aligning with market estimates. These core figures, while less dramatic than the headline number, still indicate that inflationary pressures are not solely confined to transient factors but are somewhat embedded across various sectors of the economy. The divergence between the strong headline and slightly softer core readings highlights the significant role that specific sectors, particularly energy, are currently playing in driving overall wholesale price inflation.
Immediate Market Reactions and Expert Analysis
The release of the August PPI data sent immediate ripples across financial markets, underscoring the report’s perceived implications for monetary policy. Stock market futures registered negative territory following the announcement, reflecting investor anxiety over the potential for higher interest rates and their dampening effect on corporate earnings and economic activity. Concurrently, U.S. crude oil prices breached the significant $100 a barrel threshold, further fueling concerns about energy-driven inflation and its broader economic ramifications. This simultaneous rise in wholesale prices and crude oil costs created a potent cocktail of inflationary fears.
Perhaps the most pronounced market reaction was observed in the bond market, where Treasury yields moved sharply higher. The benchmark 10-year Treasury note yield, a key indicator of long-term borrowing costs and economic outlook, surged to its highest level since November 2023. This sharp increase in yields reflects investors’ expectation of tighter monetary policy and a higher discount rate for future cash flows, signaling a repricing of risk and return in light of persistent inflation.
Economists were quick to interpret the implications of the report. Chris Rupkey, chief economist at Fwdbonds, articulated a widely held sentiment, stating, "Net, net, today’s PPI inflation report does nothing to turn down the warnings about the inflation threats the economy faces, especially if you are an inflation hawk with an itchy trigger finger at the Federal Reserve." This commentary succinctly captures the challenge confronting the Fed: the August PPI data provides little comfort for those advocating for a pause in rate hikes and instead strengthens the hand of policymakers prioritizing aggressive action to curb inflation.
Deeper Dive into PPI Components: The Engine of Inflation
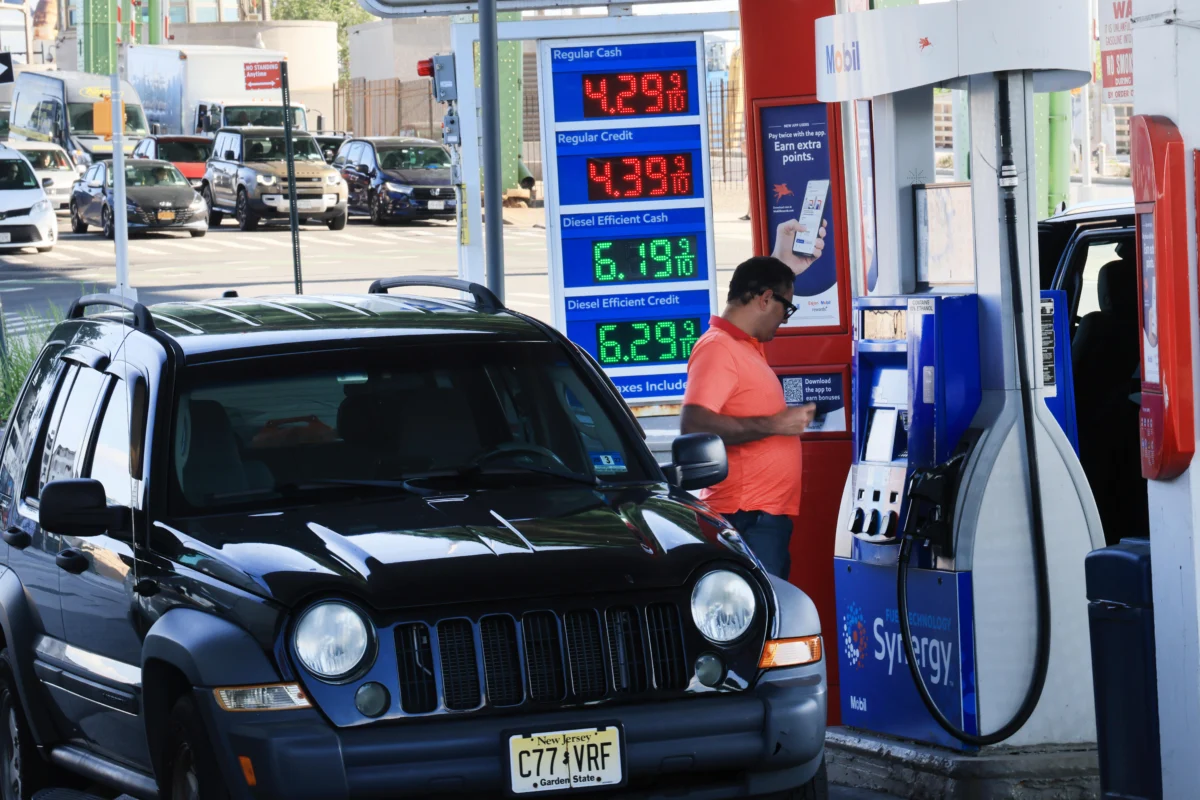
A granular examination of the PPI report reveals the specific categories driving the wholesale price acceleration. Energy prices emerged as the predominant factor, witnessing a substantial 4.2% increase in final demand. This surge was overwhelmingly driven by soaring diesel prices, which recorded an astounding 24.1% monthly jump. The significant rise in diesel costs is particularly concerning given its widespread use across transportation, manufacturing, and agriculture, suggesting broad-based upward pressure on operating costs for businesses throughout the supply chain.
Beyond energy, goods prices broadly increased by 1.1% for the month. This comprehensive rise across various goods categories signals robust demand or constrained supply, or a combination of both. The goods sector has been a significant contributor to inflation since the post-pandemic recovery, initially due to supply chain disruptions and strong consumer demand for tangible products. While some of those initial bottlenecks have eased, the August data suggests that pricing power for producers of goods remains considerable.
In contrast to the goods sector, services prices exhibited a more modest 0.1% increase. However, even within services, certain segments experienced notable upward pressure. Transportation and warehousing services, for instance, saw a 2.3% increase, accounting for a substantial portion of the overall services price rise. This particular increase is directly linked to the higher energy costs, especially diesel, impacting freight and logistics operations. Elevated transportation costs inevitably feed into the prices of goods delivered to retailers and ultimately to consumers.
A closely watched metric within the PPI calculations, portfolio management costs, presented a mixed picture. These costs, which reflect fees charged by investment managers, fell by 1.6% for the month. Despite this monthly decline, they remained up an elevated 18.8% from a year ago, illustrating the volatility and sensitivity of this particular service component, often influenced by market performance and asset valuations.
Pipeline Pressures: Indicators of Future Inflation: The PPI report also provides crucial insights into "pipeline pressures," which are leading indicators of future inflation. Processed goods prices, representing intermediate inputs for further production, increased by 1.8%. Simultaneously, unprocessed goods, which are raw materials, accelerated by 1.1%. The simultaneous rise in both processed and unprocessed goods prices indicates that inflationary pressures are building from the earliest stages of the production process, suggesting that higher costs are being absorbed by manufacturers and are likely to be passed on to subsequent stages of the supply chain, eventually reaching consumers. This robust increase in input costs reinforces the notion that disinflationary forces have not yet fully taken hold in the economy.
The Federal Reserve’s Conundrum: Data Dependence and Policy Decisions
The August PPI report lands on the desks of central bankers less than a week before their critical interest rate decision meeting. The Federal Reserve operates under a dual mandate from Congress: to achieve maximum employment and maintain price stability (typically defined as 2% annual inflation). For much of 2026, the Fed had maintained a "hold" on its benchmark interest rate, observing the impact of previous tightening cycles and hoping for inflation to naturally decelerate. However, the persistent strength of economic data, including the latest PPI figures, challenges this patient approach.
Market Expectations and Policymaker Divergence: Prior to the PPI release, market pricing for the upcoming Fed meeting had been somewhat volatile, reflecting uncertainty about the central bank’s next move. Following the PPI data, traders notably increased their bets on a rate increase, with the odds climbing close to 66%, according to the CME Group’s FedWatch gauge of futures prices. This shift underscores the market’s perception that the latest inflation data tips the scales towards further monetary tightening.
Public statements from Fed officials leading up to the meeting have revealed a split in perspectives, highlighting the complexity of the current economic landscape. Chairman Kevin Warsh has recently reiterated his unwavering commitment to bringing inflation back to the 2% target, explicitly stating that "action may be needed" to achieve this goal. His remarks, delivered at the influential Jackson Hole symposium, signaled a hawkish stance and a readiness to resume rate hikes if data warranted it. Conversely, other policymakers have advocated for a more patient, data-dependent approach, urging for continued observation of economic indicators to assess the trajectory of inflation before committing to further policy adjustments. This internal debate within the Fed underscores the difficulty in navigating an economy characterized by robust employment alongside persistent price pressures.
The Broader Inflation Landscape: CPI and PCE
While the PPI provides crucial insights into wholesale prices, the Federal Reserve ultimately bases its policy decisions on a broader set of inflation measures. A separate and equally critical report, the Consumer Price Index (CPI), is slated for release the day after the PPI. The CPI directly measures the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services. Current expectations for the CPI project a headline annual inflation rate of 3.4%, with the core CPI (excluding food and energy) anticipated at 2.4%. While the CPI is a widely publicized measure, the Fed’s preferred inflation gauge is the Personal Consumption Expenditures (PCE) price index. The PCE index, which offers a broader measure of inflation by accounting for a wider range of goods and services and adjusting for consumer substitution to cheaper alternatives, will not be released until later in the month, after next week’s policy meeting. Nonetheless, both the PPI and CPI reports feed into the Fed’s overall assessment of inflationary trends and will inform their decision-making process, even if the PCE is their ultimate target. The sequential release of these reports creates a dynamic "data calendar" that significantly shapes market expectations and policy outlooks.
Broader Economic Context: Drivers of Persistent Inflation
The persistent inflation observed throughout 2026, including the latest PPI surge, can be attributed to a confluence of factors, both domestic and global. A significant contributor has been the lingering impact of tariffs and trade policies, which increase the cost of imported goods and components, thereby elevating input costs for domestic producers. These trade barriers, imposed in previous years, continue to exert upward pressure on prices across various sectors.
Furthermore, geopolitical tensions, particularly the ongoing war in the Middle East, have played a substantial role in disrupting global energy markets. The recent breach of $100 a barrel for U.S. crude oil is a direct consequence of these tensions, alongside supply constraints and robust global demand. Energy price shocks have a pervasive effect, raising costs for transportation, manufacturing, and ultimately, consumer goods and services. The interconnectedness of global supply chains means that regional conflicts can have far-reaching inflationary consequences.
Beyond these specific factors, global supply chain dynamics, though having shown signs of improvement, continue to present challenges. While some bottlenecks have eased, others persist, contributing to higher logistics costs and production delays that can translate into higher prices. The robust labor market, characterized by low unemployment and strong wage growth in some sectors, also contributes to inflationary pressures by increasing labor costs for businesses, which can then be passed on to consumers. The combination of these demand-side and supply-side factors creates a complex inflationary environment that is proving difficult to dislodge.
Implications for Businesses, Consumers, and the Economic Outlook
The August PPI report carries significant implications for various stakeholders across the economy. For businesses, particularly those in manufacturing, transportation, and retail, rising wholesale prices translate directly into higher input costs. This can compress profit margins if they are unable to fully pass on these increased costs to consumers. Small and medium-sized enterprises, often with less pricing power than larger corporations, may find themselves particularly vulnerable to this squeeze.
For consumers, the upward trend in wholesale prices foreshadows potential increases in retail prices in the coming months. While the PPI measures producer prices, these costs eventually filter down to the consumer level. Higher prices for everyday goods and services erode purchasing power, forcing households to allocate a larger portion of their income to necessities, potentially reducing discretionary spending and impacting overall economic growth.
The prospect of further interest rate hikes by the Federal Reserve, largely influenced by reports like the PPI, also has broad implications. Higher benchmark interest rates translate into increased borrowing costs for businesses seeking to expand or invest, and for individuals taking out mortgages, auto loans, or carrying credit card debt. This can dampen investment, slow job creation, and cool the housing market, potentially impacting broader economic activity. The ultimate goal of the Fed is to engineer a "soft landing" – bringing inflation down without triggering a severe recession. However, the latest data suggests this path is becoming increasingly narrow and challenging.
Looking Ahead: The Path to Price Stability
The August PPI report unequivocally reinforces the narrative of persistent inflationary pressures within the U.S. economy. It places the Federal Reserve in a precarious position, tasked with making a critical interest rate decision amidst conflicting signals of economic strength and price instability. The central bank’s immediate focus will be on analyzing the upcoming CPI report and carefully weighing all available economic data before its policy announcement.
The challenge for the Fed is multifaceted: to continue signaling its commitment to price stability, manage inflation expectations, and avoid overtightening that could push the economy into an unnecessary downturn. The path to achieving the 2% inflation target remains arduous, complicated by global economic dynamics, geopolitical events, and domestic demand pressures. Future policy decisions will undoubtedly hinge on a continuous assessment of incoming data, with each economic report, including the PPI, serving as a vital piece of the intricate puzzle that monetary policymakers are striving to solve. The trajectory of wholesale prices, as highlighted by the August data, will remain a key indicator to watch in the ongoing battle against inflation and the pursuit of long-term economic stability.