Gilang Muhammad
United States wholesale prices experienced a notable surge in August, according to a pivotal report released Thursday by the Bureau of Labor Statistics (BLS). This uptick in producer costs, measured by the Producer Price Index (PPI), arrived at a critical juncture for the Federal Reserve, adding significant weight to its impending interest rate decision and reinforcing concerns about persistent inflationary pressures across the economy. The data immediately sent ripples through financial markets, prompting negative reactions in equities and a sharp ascent in Treasury yields, as investors recalibrated their expectations for monetary policy tightening.
Understanding the Producer Price Index: A Forward-Looking Gauge of Inflation
The Producer Price Index (PPI) serves as a vital economic indicator, tracking the average change over time in the selling prices received by domestic producers for their output. It is a comprehensive measure of final demand costs for goods and services, encompassing prices from various stages of production and distribution. Unlike the Consumer Price Index (CPI), which reflects prices paid by consumers, the PPI captures prices at the wholesale level, providing an early indication of potential future changes in consumer prices. When producer prices rise, businesses often face increased input costs, which they may eventually pass on to consumers in the form of higher retail prices, making the PPI a crucial gauge for anticipating inflationary trends.
The PPI for final demand is composed of six main price indexes: final demand goods, final demand services, final demand construction, final demand for processed goods for intermediate demand, final demand for unprocessed goods for intermediate demand, and final demand for services for intermediate demand. A detailed breakdown of these components offers insights into where inflationary pressures are originating within the supply chain. Economists and policymakers closely monitor the PPI, particularly its core components (excluding volatile food and energy prices), to discern underlying inflationary trends that might persist beyond temporary fluctuations.
August’s Alarming Figures: A Deeper Dive into Wholesale Inflation
For the month of August, the PPI for final demand increased by a seasonally adjusted 0.4%, aligning with the Dow Jones consensus estimate. While the monthly figure met expectations, the year-over-year data painted a more concerning picture. On an annual basis, the PPI accelerated to 5.4%, a substantial increase from the previous period and notably 0.1 percentage point higher than the anticipated 5.3%. This 5.4% annual rate remains considerably above the Federal Reserve’s long-term inflation target of 2%, signaling the entrenched nature of current price pressures. Adding to the concern, the July PPI figure was subject to a slight upward revision, moving from an original estimate of no change to a 0.1% increase, suggesting that inflationary momentum was already building more than initially perceived.
-
Headline vs. Core Inflation: While the headline PPI captured broad price movements, a closer look at core inflation metrics offered mixed signals but generally affirmed persistent pressures. Excluding the volatile categories of food and energy, the core PPI for final demand accelerated by 0.2% for the month. This figure was slightly below the forecast of a 0.3% increase, offering a minor point of relief amidst the broader upward trend. Another closely watched measure, core PPI less trade services, which strips out a particularly volatile component of the services sector, rose by 0.3%, precisely in line with market estimates. These core readings, while somewhat moderating, did not significantly alleviate the overall inflationary narrative presented by the headline numbers.
-
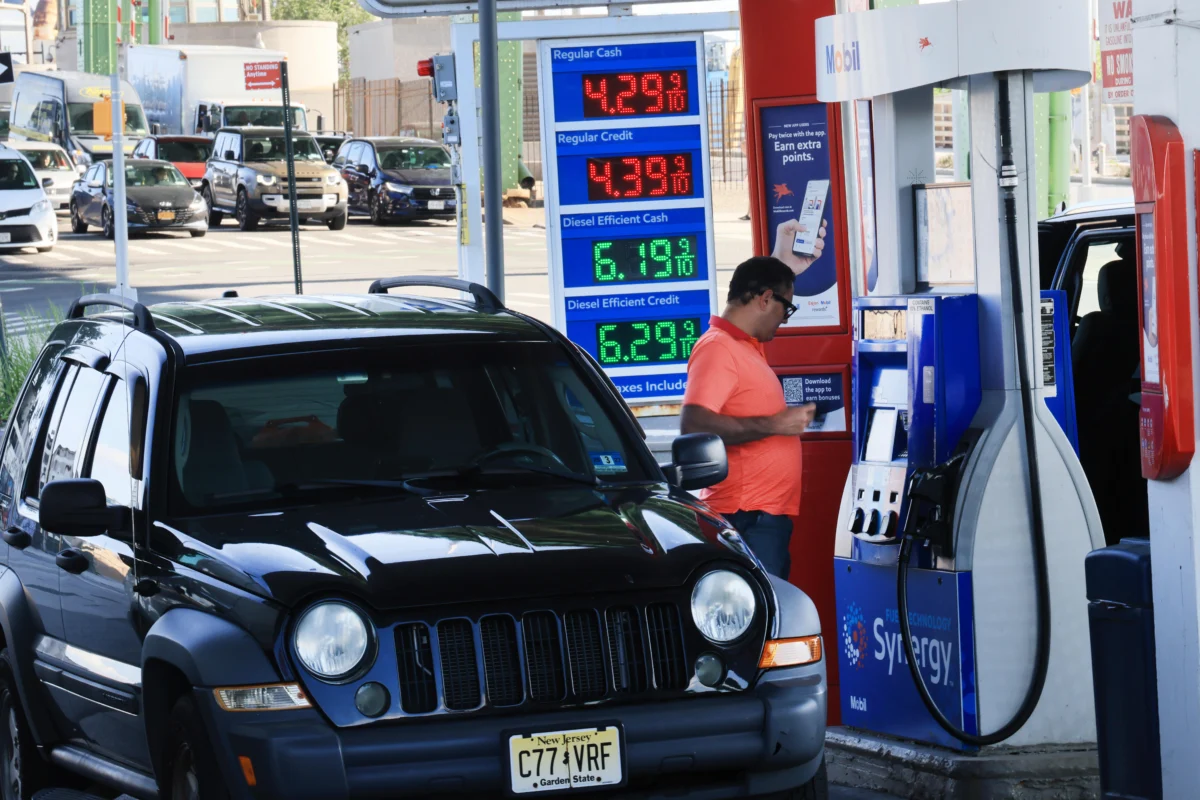
The Energy Price Surge: A primary driver behind August’s PPI increase was a significant jump in energy prices. Final demand energy prices surged by 4.2% for the month, representing a substantial portion of the overall inflation. This sharp increase was predominantly fueled by soaring diesel prices, which experienced an extraordinary 24.1% leap. The dramatic rise in diesel costs has widespread implications, as diesel is a critical fuel for transportation, manufacturing, agriculture, and construction industries. Higher diesel prices directly translate to increased operational costs for businesses, which are then often passed down through the supply chain, ultimately affecting consumer prices for a vast array of goods. The concurrent news of U.S. crude oil prices topping $100 a barrel on the day of the PPI release further underscored the renewed upward trajectory in energy markets, compounding inflation concerns.
-
Goods and Services Dynamics: Broadly, prices for final demand goods increased by 1.1% in August. This significant rise, heavily influenced by the energy component, indicates that the cost of producing and distributing physical products continues to exert upward pressure on wholesale prices. In contrast, prices for final demand services saw a more modest increase of just 0.1%. However, even within this seemingly muted services figure, specific sectors exhibited considerable upward momentum. Transportation and warehousing services, for instance, recorded a substantial 2.3% increase, accounting for a significant portion of the overall services price movement. This highlights the persistent impact of logistics and supply chain challenges on business costs.
-
Persistent Pipeline Pressures: Beyond final demand, the report also revealed further signs of "pipeline pressures" – increases in prices at earlier stages of production that often foreshadow future inflation. Prices for processed goods for intermediate demand, which are inputs for other industries, increased by 1.8%. Similarly, prices for unprocessed goods for intermediate demand, representing raw materials, accelerated by 1.1%. These increases suggest that inflationary forces are not only impacting finished products but are also percolating through the supply chain from its foundational stages, indicating potential for sustained price hikes in the coming months.
-
The Enigma of Portfolio Management Costs: A closely watched metric within the PPI calculations, portfolio management costs, presented a mixed picture. These costs fell by 1.6% for the month, offering a momentary deceleration in a historically volatile category. However, on an annual basis, portfolio management costs remained significantly elevated, up by 18.8% from a year ago. This long-term trend suggests that despite monthly fluctuations, the underlying costs associated with financial services continue to contribute to broader inflationary pressures over a longer horizon.
Market’s Immediate Verdict: Volatility and Heightened Rate Hike Bets
The release of the August PPI report immediately triggered a strong reaction across financial markets, underscoring the data’s critical implications for economic outlook and monetary policy. Stock market futures turned negative following the announcement, signaling investor apprehension about the prospect of higher interest rates and their potential dampening effect on corporate earnings and economic growth.
-
Equities and Fixed Income Volatility: The bond market, often considered more sensitive to inflation and interest rate expectations, reacted even more sharply. Treasury yields moved decisively higher, with the benchmark 10-year note hitting its highest level since November 2023. A rise in bond yields reflects investors demanding greater compensation for holding government debt, typically in response to increased inflation expectations or the anticipation of higher policy rates from the central bank. Higher yields can make borrowing more expensive for businesses and consumers, affecting everything from mortgage rates to corporate investment decisions.
-
Oil Prices Breach Key Threshold: Coinciding with the PPI release, U.S. crude oil prices surpassed the psychological barrier of $100 a barrel. This development further exacerbated inflation fears, as energy costs are a fundamental input for nearly all economic activity. The confluence of rising wholesale prices and escalating oil benchmarks painted a challenging picture for the economic outlook, suggesting that the battle against inflation was far from over.
The Federal Reserve’s Conundrum: Navigating Persistent Inflation
The August PPI report lands less than a week before the Federal Reserve’s Federal Open Market Committee (FOMC) is scheduled to release its latest decision on interest rates. This data point significantly complicates the Fed’s delicate balancing act, as it grapples with its dual mandate of achieving maximum employment and maintaining price stability. With inflation remaining stubbornly above its 2% target, the central bank faces renewed pressure to act decisively.
-
Navigating the Dual Mandate: The Fed’s dual mandate requires it to balance the risks of inflation against the risks to economic growth and employment. Persistent inflation erodes purchasing power and creates economic uncertainty, while overly aggressive rate hikes can stifle economic activity and potentially lead to a recession. The August PPI data clearly leans into the inflation side of this equation, making the path to price stability more arduous.
-
The Path to a Rate Decision: After maintaining a "hold" stance throughout 2026, the Federal Reserve is now widely expected to approve a quarter percentage point hike of its benchmark interest rate at the upcoming meeting. Market pricing, though volatile, reflected this increased probability. Following the PPI release, traders slightly increased their bets on a rate increase, pushing the odds close to 66%, according to the CME Group’s FedWatch gauge, which tracks futures prices. This indicates a growing consensus that the Fed will opt for another rate hike to curb inflationary pressures.
-
A Divided Council: Public statements from Federal Reserve officials have revealed a division within the central bank regarding the appropriate path forward. Chairman Kevin Warsh has recently emphasized his unwavering commitment to getting inflation back to the 2% target, indicating that further action may be necessary to achieve this objective. His remarks, particularly at the Jackson Hole symposium, underscored a hawkish stance, suggesting a willingness to tolerate some economic pain to ensure price stability. However, other Fed officials have advocated for a more patient approach, arguing that policymakers should continue to monitor incoming data for clearer signs of how economic trends are developing before committing to further tightening. This internal debate highlights the complexity of the current economic environment and the varied interpretations of recent data.
-
The Role of Key Economic Indicators: The Fed’s decision-making process is heavily reliant on a comprehensive suite of economic data. The PPI is one such crucial input, offering insights into producer-level costs. Another vital report, the Consumer Price Index (CPI), which directly measures consumer-level inflation, is scheduled for release on Friday. The CPI is expected to show a headline annual inflation rate of 3.4%, with core CPI anticipated at 2.4%. Both the PPI and CPI figures feed into the Fed’s preferred inflation gauge, the Personal Consumption Expenditures (PCE) price index. While the PCE will not be released until later in the month, after next week’s policy meeting, the PPI and CPI provide critical immediate context for the FOMC’s deliberations.
Broader Economic Context and Global Headwinds
The persistent inflation witnessed throughout this year cannot be attributed to a single factor but rather a confluence of domestic and international pressures.
-
Inflation’s Stubborn Roots: A significant portion of this year’s stubborn inflation has been attributed to the lingering impact of tariffs. Trade tariffs, imposed on various imported goods, increase the cost of those goods for domestic businesses and consumers. These higher import costs can ripple through the supply chain, contributing to overall inflationary pressures. Furthermore, geopolitical tensions, particularly the ongoing conflict in the Middle East, have played a substantial role. This conflict has introduced significant uncertainty into global energy markets, disrupting supply chains and pushing up crude oil prices, as evidenced by the recent breach of the $100 per barrel mark. The war’s broader impact on global trade routes and commodity prices has created a complex environment for managing inflation.
-
Historical Perspective on Inflation: The current inflationary period follows an unprecedented era of monetary easing during the COVID-19 pandemic, coupled with significant fiscal stimulus. Initially, many policymakers, including those at the Fed, characterized the rising inflation as "transitory," expecting it to abate as supply chains recovered and demand normalized. However, as inflation proved more persistent, the Fed embarked on an aggressive campaign of interest rate hikes starting in early 2022, rapidly raising rates from near-zero levels to their current multi-decade highs. The August PPI report serves as a stark reminder that despite these efforts, the journey back to the 2% inflation target remains challenging and potentially protracted.
Implications for Businesses and Consumers
The continued rise in wholesale prices carries significant implications for both businesses and ordinary consumers.
-
Passing on Costs: For businesses, higher PPI figures mean increased costs for raw materials, energy, and transportation. Companies face a difficult choice: absorb these higher costs, which can squeeze profit margins, or pass them on to consumers through higher retail prices. The latter often contributes to the very consumer inflation the Fed is trying to combat, creating a cyclical challenge. Sectors heavily reliant on energy and goods, such as manufacturing, logistics, and retail, are particularly vulnerable to these pressures.
-
Impact on Purchasing Power: For consumers, persistent inflation erodes purchasing power. When prices for everyday goods and services rise faster than wages, households find their budgets stretched, making it harder to afford necessities and discretionary spending. This can lead to a slowdown in consumer spending, which is a major driver of economic growth. Higher interest rates, a potential consequence of the PPI report, also translate to more expensive borrowing for consumers, affecting everything from mortgage payments and car loans to credit card interest.
-
Investment and Growth Outlook: The uncertainty surrounding inflation and interest rates can also deter business investment. Companies may postpone expansion plans, hiring, or capital expenditures if they anticipate higher borrowing costs or a potential economic slowdown. This cautious approach can temper overall economic growth and contribute to a more challenging economic environment.
Looking Ahead: The Road to Price Stability
The August Producer Price Index report serves as a potent reminder of the ongoing complexities facing the U.S. economy and the Federal Reserve. The data unequivocally points to persistent wholesale price pressures, driven significantly by surging energy costs and broader goods inflation. As central bankers prepare for their critical interest rate decision, the PPI figures, coupled with the upcoming CPI report and global economic headwinds, will undoubtedly weigh heavily on their deliberations. The path to achieving the Fed’s 2% inflation target appears increasingly challenging, suggesting that the era of higher interest rates may extend further as policymakers remain steadfast in their commitment to restoring price stability, even if it entails further economic adjustments. The coming weeks will be crucial in determining the immediate trajectory of U.S. monetary policy and its ripple effects across the global economy.