Gilang Muhammad
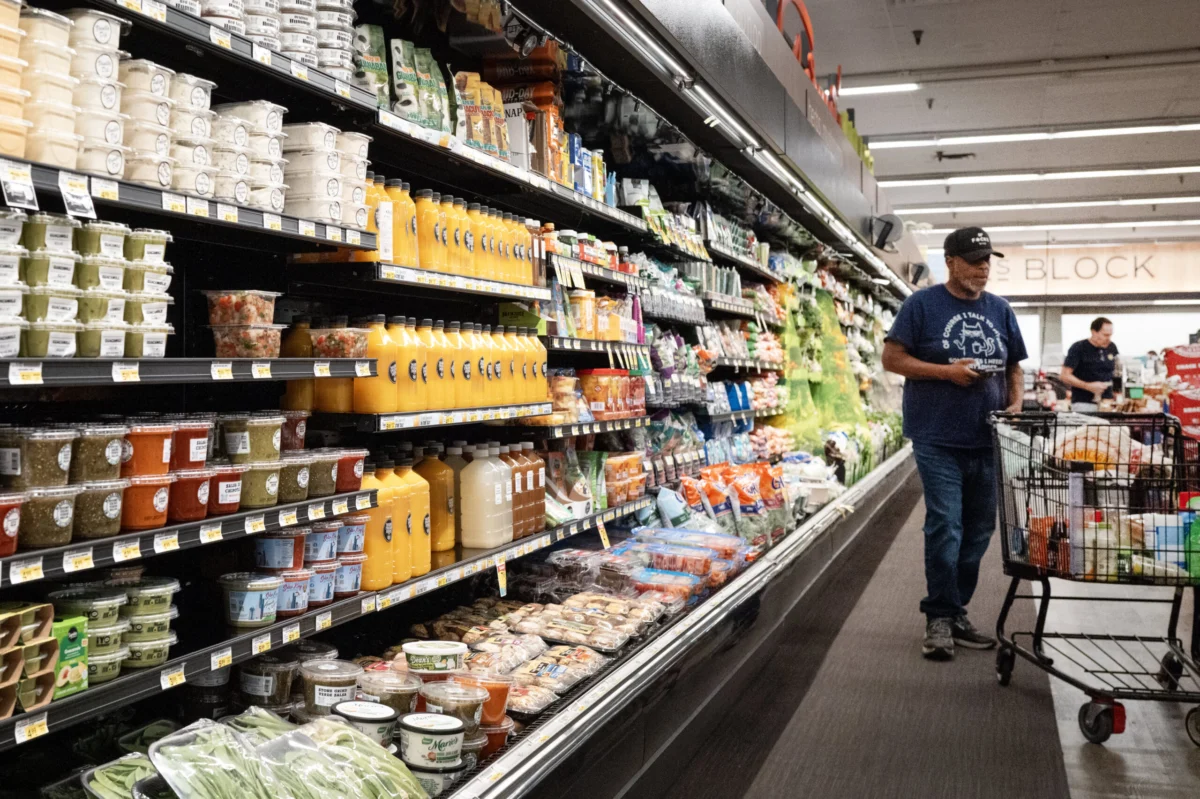
Washington D.C. – As the nation braces for Wednesday’s highly anticipated release of the September Consumer Price Index (CPI), economists and policymakers are closely monitoring signs of escalating inflationary pressures, primarily driven by persistently high energy costs exacerbated by ongoing geopolitical conflicts. The upcoming report is widely expected to reveal an acceleration in the rate of price growth, potentially pushing inflation further away from the Federal Reserve’s long-term target and complicating the central bank’s monetary policy trajectory.
Anticipating September’s Inflationary Surge
Market analysts and economists surveyed by Dow Jones project the headline consumer price index for September to register a month-over-month increase of 0.6%. More significantly, the year-over-year figure is anticipated to climb to 3.6%, a notable acceleration from previous months and a clear indication that the cost of living continues its upward trend. This projected 12-month increase would mark a substantial divergence from the Federal Reserve’s mandated 2% inflation target, signaling a challenging economic environment for households and businesses alike.
Core inflation, a critical metric that strips out the volatile components of food and energy prices, is also under scrutiny. Experts forecast a 0.2% rise from August to September, with the 12-month core CPI expected to reach 2.5%. While this monthly increase would represent a slight deceleration compared to some prior periods, the year-over-year core inflation rate would still reflect an uptick, underscoring the broadening nature of price pressures beyond just energy markets. This "stickiness" in core inflation is particularly concerning for the Federal Reserve, as it suggests that price increases are becoming more entrenched in the broader economy, rather than being confined to transient shocks.
The Dominant Role of Energy Costs: A Geopolitical Confluence
The primary catalyst for the anticipated surge in the headline CPI is the relentless upward trajectory of energy costs. Joe Brusuelas, chief economist at RSM, a prominent tax firm, emphasized the significant "upside risk" that oil-related prices pose to the September CPI data. "Typically, when we have these moves in inflation, everyone’s models undershoot the actual outcome," Brusuelas noted, highlighting the potential for the report to exceed even the elevated expectations.
This current spike in energy prices is inextricably linked to a series of complex geopolitical developments that have unfolded throughout 2026. The most significant factor has been the ongoing U.S. war with Iran, which commenced earlier this year. This conflict has severely disrupted global oil supply chains, particularly impacting shipments through the critical Strait of Hormuz, a narrow choke point through which a substantial portion of the world’s seaborne oil passes. Fears of supply disruptions, coupled with actual logistical challenges, have kept crude oil prices on an elevated path.
Further compounding the situation, President Donald Trump last week announced a controversial decision to loosen diesel restrictions on Russia. This move, intended to "juice" the global oil trade and alleviate price pressures, has been met with skepticism by analysts. Many experts do not believe that this measure will meaningfully bring down prices, citing persistent structural issues in the energy market and the broader impact of sanctions and geopolitical realignments following the Russia-Ukraine conflict. The effectiveness of such policy interventions in a market already under severe duress from multiple fronts remains highly questionable.
A Volatile Oil Market: Brent Crude’s Ascent
The impact of these factors is clearly reflected in crude oil benchmarks. Brent crude, the international standard for oil prices, witnessed a dramatic ascent in recent months. In September alone, Brent prices climbed more than 14%, culminating in a staggering 42% advance over the third quarter of 2026. By Tuesday, Brent crude was trading around $105 per barrel, a level not seen consistently in years and one that exerts immense pressure on downstream industries and consumer budgets.
The implications of such elevated oil prices extend far beyond gasoline pumps. Robert Sockin, chief U.S. economist at asset manager PGIM, pointed out that "sticky oil prices could also push up costs for items in other, non-energy categories." This phenomenon, known as "second-round effects" or "cost-push inflation," occurs as higher transportation, manufacturing, and input costs due to expensive fuel are passed on to consumers in the form of higher prices for a wide array of goods and services. This makes it increasingly difficult for the Federal Reserve to dismiss the energy price surge as a mere "short-term shock" that would not necessitate further monetary tightening.
The Federal Reserve’s Tightrope Walk: More Rate Hikes on the Horizon
The prospect of accelerating and broadening inflation places the Federal Reserve in an increasingly challenging position. After announcing its first interest rate increase in three years last month, the central bank signaled in the minutes from that meeting that further hikes are likely on the horizon. The Fed’s dual mandate – to achieve maximum employment and stable prices (defined as 2% inflation) – is currently heavily weighted towards combating inflation.
Financial markets are already pricing in the likelihood of additional tightening. According to CME’s FedWatch tool, Fed funds futures traders widely anticipate that the central bank will next lift rates at its December policy meeting. This expectation underscores the market’s conviction that the Fed will act decisively to rein in inflation, even if it risks dampening economic growth.
"The list of reasons to hike rates in our view is long," Sockin affirmed, highlighting the confluence of factors compelling the Fed to act. He added, "Ultimately, we have low confidence in the timing of the Fed’s next move, but more conviction on the direction of travel." This sentiment reflects the uncertainty surrounding the precise pace and magnitude of future rate increases, but a firm belief that the era of ultra-low interest rates is decisively over. The Fed’s challenge lies in engineering a "soft landing," where inflation is brought under control without triggering a severe economic recession. Historically, this has proven to be a delicate and often elusive balance.
Broader Economic Indicators: A Symphony of Rising Costs
The September CPI report is not an isolated data point; it forms part of a broader narrative of rising costs across the economy. The Producer Price Index (PPI), a gauge of inflation facing wholesalers and a leading indicator for consumer prices, is due on Thursday. Economists forecast that the PPI will rise 0.6% from August to September and 5.5% on a 12-month basis. Both figures would represent a modest acceleration in growth compared with August’s release, indicating that inflationary pressures are building at the wholesale level and are likely to continue flowing through to consumers.
Beyond prices, other economic indicators paint a picture of an economy grappling with persistent cost increases. Wage growth, while beneficial for workers, has also contributed to inflationary pressures, particularly in service sectors where labor costs are a significant component. While not necessarily a "wage-price spiral" in the classical sense, the tight labor market and demands for higher compensation are undoubtedly playing a role in the current inflationary environment. Global supply chain disruptions, though showing some signs of easing in certain sectors, continue to pose challenges, especially for manufactured goods and components. The confluence of these factors creates a complex web of inflationary forces that are difficult to untangle.
Political Ramifications: Midterms and Public Sentiment
The timing of Wednesday’s CPI release is particularly significant, as it marks the last major inflation reading before November’s crucial midterm elections. These elections could profoundly reshape the political landscape, determining whether the Republican party maintains its current total control in Washington or faces a significant shift in power dynamics. High inflation historically tends to be a potent political issue, often leading to voter discontent and shifts in electoral outcomes.
Public sentiment data reflects the growing economic anxiety across the nation. According to the University of Michigan’s consumer sentiment data, economic confidence across all political affiliations has fallen throughout 2026. Notably, Republican and independent voters have posted steeper declines in sentiment since the start of the year compared with Democrats, as the data from the Survey of Consumers (SCA) at the University of Michigan indicates. This divergence suggests that the perception of economic hardship may vary based on political leanings, but the overall trend is one of declining optimism.
For the incumbent administration, persistently high inflation presents a formidable challenge. Voters often attribute economic conditions directly to the party in power, making inflation a central battleground issue in electoral campaigns. The administration’s efforts to address rising costs, including President Trump’s controversial move on Russian diesel, are under intense scrutiny, and their perceived effectiveness will undoubtedly influence voters’ decisions at the polls.
A Global Economic Challenge
The inflationary pressures gripping the United States are not isolated; they are part of a broader global phenomenon. Many major economies around the world are battling their own struggles with elevated inflation, driven by similar factors such as high energy prices, supply chain bottlenecks, and robust post-pandemic demand. Central banks globally are coordinating, to varying degrees, in their efforts to tighten monetary policy, leading to a synchronized global deceleration in economic growth forecasts.
Organizations like the International Monetary Fund (IMF) and the World Bank have repeatedly warned about the risks of persistent inflation and the potential for a global economic slowdown or even recession. The interconnectedness of global markets means that inflation in one major economy can quickly ripple outwards, affecting trade balances, currency valuations, and investment flows worldwide. The U.S. Federal Reserve’s actions, therefore, have significant implications not just domestically, but for the stability of the global financial system.
Outlook and Conclusion: Navigating Uncertain Waters
As the September CPI report approaches, the immediate focus will be on the numbers themselves and whether they confirm the grim forecasts of accelerating inflation. Beyond the headlines, the subsequent reactions from financial markets, the Federal Reserve, and political leaders will be closely watched. The path ahead appears fraught with challenges, requiring careful navigation from policymakers to tame inflation without unduly stifling economic growth.
For consumers, the rising cost of living continues to be a primary concern, impacting household budgets and purchasing power. Businesses face the dual challenge of managing escalating input costs while trying to maintain competitive pricing and consumer demand. The interplay of geopolitical events, monetary policy decisions, and domestic economic conditions will shape the economic narrative for the foreseeable future, making the September CPI report a critical bellwether for the months to come. The era of low inflation and easy money appears to be firmly in the rearview mirror, replaced by an environment demanding vigilance and strategic adaptation from all stakeholders.