Reynand Wu
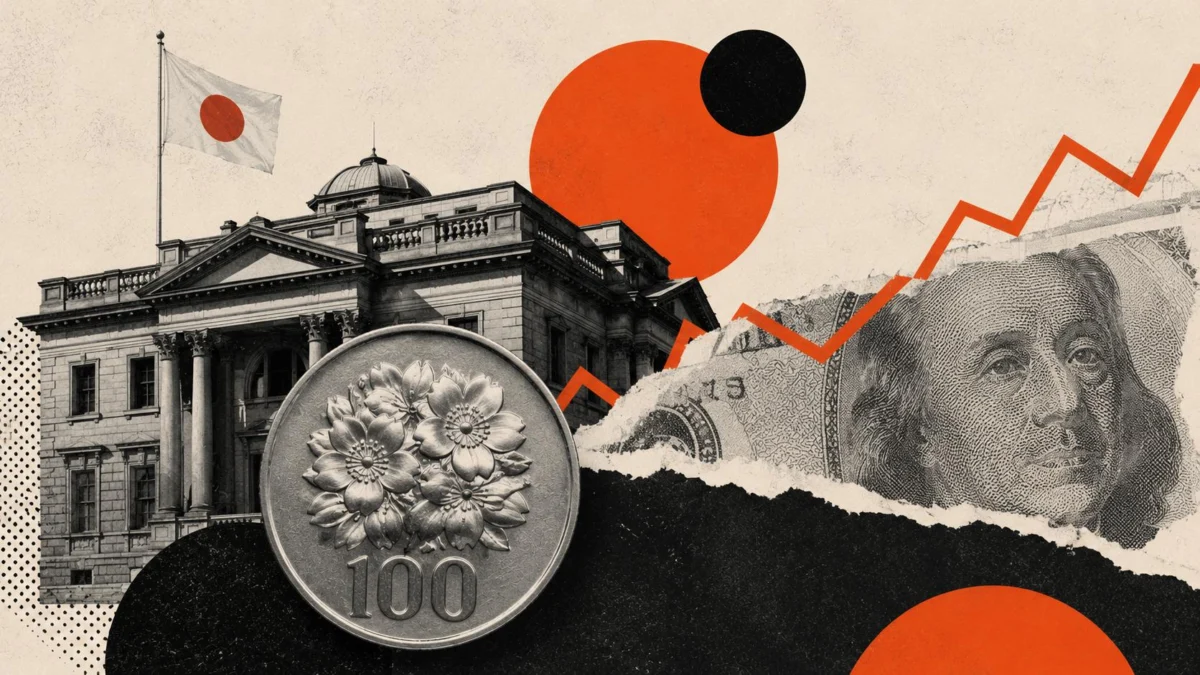
The Bank of Japan (BoJ) finds itself at a critical juncture, facing mounting pressure as the Japanese Yen (JPY) continues its significant depreciation against major currencies. This persistent weakening of the national currency is not only causing economic ripples domestically but is also drawing increased scrutiny from international partners and financial markets alike. Analysts, including Thu Lan Nguyen of Commerzbank, argue that the BoJ’s recent policy adjustments, notably its first rate hike in 17 years, have fallen short of reassuring markets about its commitment to a decisive tightening path, risking both the Yen’s stability and Japan’s broader economic growth trajectory. The consensus forming among many market participants is that mere verbal threats of foreign exchange (FX) intervention are proving insufficient to stem the tide, necessitating a more concrete and accelerated shift in monetary policy.
A Legacy of Looseness: Japan’s Deflationary Battle
To fully appreciate the BoJ’s current predicament, it is essential to understand the historical context of its monetary policy. For decades, Japan grappled with persistent deflation, a phenomenon that saw prices consistently fall, discouraging consumer spending and business investment. This prolonged period of economic stagnation led the BoJ to adopt increasingly unconventional and ultra-loose monetary policies. A cornerstone of this approach was the negative interest rate policy (NIRP), introduced in 2016, where commercial banks were charged for holding certain excess reserves with the central bank, intended to stimulate lending and economic activity.
Simultaneously, the BoJ implemented its ambitious Yield Curve Control (YCC) program, aiming to keep the yield on the 10-year Japanese government bond (JGB) around zero percent. This was achieved through massive bond purchases, effectively anchoring long-term interest rates to encourage borrowing and investment. While these policies successfully combated deflation for a time and prevented a stronger Yen from stifling exports, they also created a stark divergence with other major central banks, particularly as global inflation began to surge post-pandemic.
The Global Shift and Japan’s Gradual Pivot
The global economic landscape underwent a dramatic transformation in 2022 and 2023. Major central banks, led by the U.S. Federal Reserve and the European Central Bank, embarked on aggressive interest rate hiking cycles to combat soaring inflation. This synchronized global tightening created a widening interest rate differential between Japan and the rest of the world. As interest rates rose elsewhere, the attractiveness of holding Yen-denominated assets diminished, leading to significant capital outflows and a sustained depreciation of the JPY.
Recognizing the growing pressures, the BoJ began a cautious pivot. In December 2022, it surprised markets by widening the permissible fluctuation band for the 10-year JGB yield under YCC from ±0.25% to ±0.50%. This move was widely interpreted as a precursor to eventual policy normalization. Further adjustments followed, and finally, in March 2024, the BoJ took the monumental step of ending both its negative interest rate policy and the YCC framework. The policy rate was raised from -0.1% to a range of 0% to 0.1%, marking Japan’s first rate hike in 17 years. This decision was predicated on the assessment that a virtuous cycle of wage and price increases was finally in sight, driven by robust wage negotiations.
Yen’s Relentless Slide: Market Disappointment and Skepticism
Despite the historic rate hike, the market’s reaction was swift and counterintuitive: the Yen weakened further. This adverse reaction underscored a deep-seated skepticism among investors. Many analysts, including Nguyen, contend that the BoJ’s move was perceived as too little, too late. The modest increase to near-zero rates still leaves a substantial yield gap compared to the U.S. Federal Funds rate (currently 5.25-5.50%) or the ECB’s deposit facility rate (4.00%).
The market’s primary concern revolves around the BoJ’s perceived reluctance to commit to a clear and accelerated path of further tightening. While the BoJ has repeatedly emphasized a data-dependent approach, investors are looking for a more explicit signal that additional and potentially faster rate hikes are firmly on the table. The impression among some traders is that the BoJ is still prioritizing a delicate balance between currency stability and economic growth, potentially at the expense of decisive action. This creates uncertainty, which in turn fuels speculative selling of the Yen.
"The fundamental problem is the persistent uncertainty surrounding the BoJ’s priorities," Nguyen notes. "On the one hand, it clearly wants to prevent a further sharp depreciation of the yen. Achieving that would require a credible signal that additional and potentially faster rate hikes are on the table." However, the BoJ’s rhetoric has often leaned towards a "gradualist" approach, aiming for a "middle path" of further rate hikes at a pace that does not derail the economy. This cautious stance, while understandable from a domestic policy perspective, is struggling to resonate with a market demanding clarity and conviction.
Data Underpinning the Pressure
The economic data underpinning the BoJ’s dilemma is complex. While headline inflation in Japan, as measured by the Consumer Price Index (CPI), has consistently remained above the BoJ’s 2% target for an extended period, the central bank has long sought evidence of sustainable inflation, particularly driven by robust wage growth. Recent spring wage negotiations have indeed yielded significant pay increases, with some major companies agreeing to rises not seen in decades. This was a key factor in the BoJ’s decision to exit NIRP.
However, the Yen’s continued depreciation directly counteracts the central bank’s inflation management efforts. A weaker Yen makes imports, particularly energy and food, more expensive, contributing to "imported inflation." This can erode the purchasing power of Japanese households, potentially offsetting the gains from higher wages.
Key Data Points:
- JPY/USD Exchange Rate: The Yen has steadily weakened from around 130 per dollar in early 2023 to consistently breaching 155 per dollar, at times testing 160, levels not seen in decades. This reflects the widening interest rate differential and market skepticism.
- Inflation (CPI): Core CPI (excluding fresh food) has been above 2% since April 2022, reaching peaks above 4%. While moderating slightly, it remains a concern, especially with the added pressure from import costs.
- BoJ Policy Rate: Currently between 0% and 0.1%, starkly contrasting with rates in other major economies.
- Economic Growth: Japan’s economy has shown periods of modest growth, but has also faced technical recessions, highlighting its fragility. The BoJ is wary of tightening too aggressively and stifling this nascent recovery.
Official Rhetoric vs. Market Reality
Japanese government officials have frequently expressed concern over the Yen’s rapid depreciation, particularly its impact on import costs for businesses and households. Finance Minister Shunichi Suzuki has repeatedly warned against "excessive volatility" and stated that the government is "watching currency movements with a high sense of urgency" and is prepared to "take appropriate action against excessive moves." These statements are widely interpreted as verbal interventions, aimed at deterring speculative selling of the Yen.
However, as Thu Lan Nguyen points out, "Over the longer run, however, merely threatening intervention is unlikely to be enough. Sooner or later, the BoJ will have to back up its words with action." The market has grown accustomed to these warnings, and without concrete policy adjustments from the BoJ, their impact diminishes over time. The effectiveness of solo FX intervention by the Ministry of Finance, while possible, is often limited if not supported by underlying monetary policy adjustments. Large-scale intervention can be costly and may only offer temporary respite if the fundamental interest rate differentials remain wide.
The Credibility Conundrum
The core of the BoJ’s challenge, as articulated by Commerzbank’s analysis, is the risk of losing credibility. If the central bank creates the impression that it is unwilling to defend the Yen decisively through robust monetary policy, it risks a self-fulfilling prophecy. Once investors begin to lose confidence in a currency, a point can be reached where even aggressive rate hikes are no longer sufficient to reverse the trend.
Nguyen draws a stark parallel to the experience of Sweden’s Riksbank in the early 1990s. During a currency crisis, the Riksbank temporarily raised its policy rate to an astonishing 500% in an desperate attempt to defend the Krona’s exchange-rate peg. Despite this extreme measure, the Riksbank ultimately abandoned its peg shortly thereafter, illustrating the immense power of market sentiment once confidence is lost. While Japan’s situation is not directly comparable, the lesson is clear: delayed or insufficient action can force a central bank into a more difficult and painful position later. The longer the BoJ tries to balance currency stability against economic growth with a cautious approach, the greater the risk that it ultimately loses control of both.
Broader Economic and Social Implications
The weakening Yen has profound implications for Japan’s economy and society:
- Households: Higher import costs for essential goods like energy and food erode purchasing power, especially for those whose wages haven’t kept pace. This can lead to a decline in real living standards and dampen consumer confidence.
- Businesses: Importers, particularly those dealing in raw materials and energy, face significantly higher costs, squeezing profit margins or forcing them to raise prices further. While exporters initially benefit from a weaker Yen, making their products cheaper abroad, the overall uncertainty and volatility can complicate long-term investment and supply chain planning.
- Inflationary Pressure: Beyond imported goods, a persistently weak Yen can contribute to broader inflationary pressures, making it harder for the BoJ to achieve its sustainable 2% inflation target without resorting to more aggressive measures.
- Foreign Investment: While a weaker Yen makes Japanese assets cheaper for foreign investors, the lack of confidence in currency stability can deter long-term capital inflows, particularly into government bonds.
- Geopolitical Standing: A significantly weakened national currency can also subtly diminish a nation’s economic standing on the global stage, impacting its influence in international financial discussions.
The Path Forward: Tightrope Walk for the BoJ
The BoJ is currently walking a tightrope. On one side lies the risk of tightening too aggressively, potentially stifling a fragile economic recovery and wage growth. On the other side is the escalating danger of losing control over the Yen’s value and market credibility, which could necessitate even more drastic measures down the line.
The market is now closely watching for further signals from the BoJ. The timing and magnitude of future rate hikes will be crucial. Many analysts suggest that another rate hike, perhaps by summer or early autumn, might be necessary to stabilize the Yen and demonstrate the BoJ’s resolve. However, the BoJ’s commitment to a "gradual" approach suggests that any further moves will likely be incremental.
In essence, time is running out for the BoJ to definitively signal its commitment to a credible tightening path. The longer it delays, the greater the challenge it faces in managing both the Yen’s stability and the broader health of the Japanese economy. The global financial community awaits decisive action that can restore confidence and provide a clearer direction for the world’s third-largest economy.