
 Ena Muazin
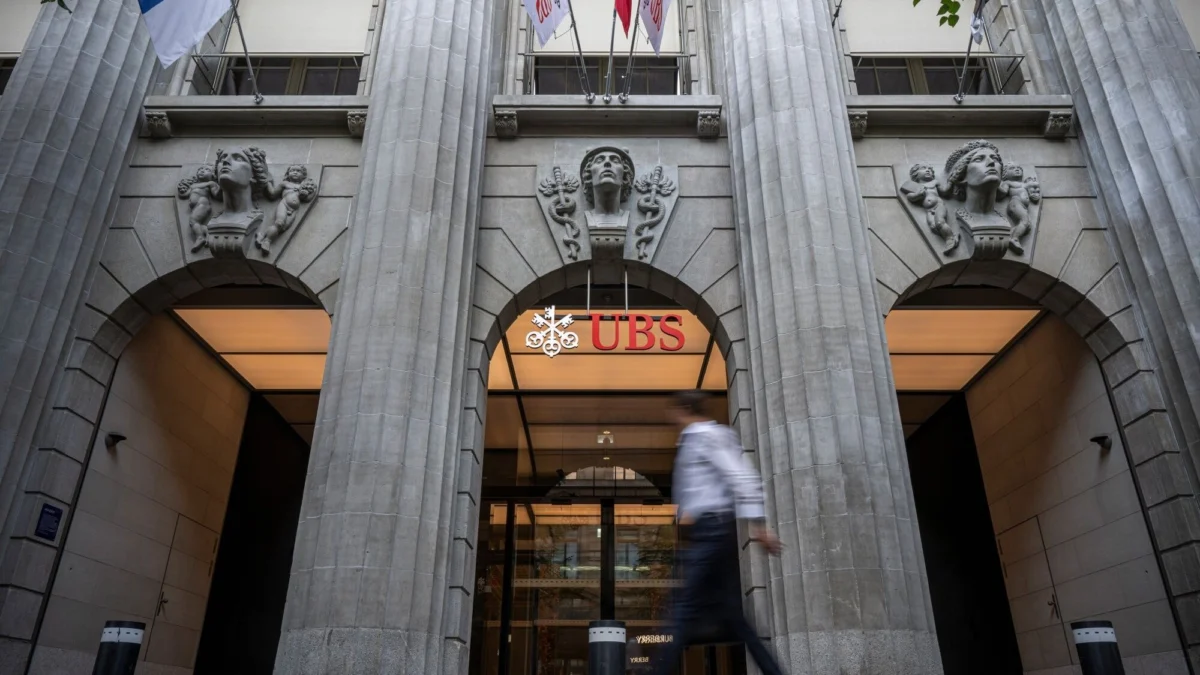
A new European Union directive, set to take effect on January 11, 2027, is poised to significantly alter how Swiss banks operate within the EU and impact German clients with accounts in Switzerland. The Capital Requirements Directive VI (CRD VI), a cornerstone of the EU’s efforts to bolster financial stability and harmonize regulatory frameworks across member states, mandates that financial institutions from non-EU countries, often referred to as "third countries," must establish a physical branch within an EU member state to continue offering core banking services like deposits, loans, and guarantees to EU citizens. This development is generating considerable discussion and concern among German individuals who have traditionally favored Swiss banking for its perceived stability and discretion, even as the era of strict bank secrecy has largely passed.
The Evolving Landscape of Swiss Banking and EU Regulation
For decades, Switzerland has been a premier global financial hub, attracting significant foreign capital due to its robust banking sector, political neutrality, and historically strong bank secrecy laws. While international pressure, including the Common Reporting Standard (CRS) implemented by the OECD, has led to increased transparency and automatic exchange of financial account information, Switzerland’s financial institutions continue to hold a substantial portion of global wealth. The EU’s move with CRD VI signals a new phase in this relationship, aiming to ensure a more integrated and secure financial market within the Union.
The directive, first proposed almost two years ago, represents a comprehensive effort to strengthen the EU’s financial architecture. CRD VI is designed to address regulatory fragmentation and enhance the resilience of the European financial system against potential shocks. For banks operating from outside the EU – including those in the United Kingdom, the United States, Japan, and Singapore, as well as Switzerland – the implications are far-reaching. The core requirement for a physical presence within the EU for conducting "core business" activities is a clear indication of the EU’s intent to bring financial services offered to its citizens under its direct regulatory purview.
Switzerland’s Significant Exposure to the EU Market

The European Union is a critically important market for Swiss banks. Nearly 40% of the assets managed cross-border by Swiss financial institutions originate from Western Europe, encompassing EU member states. This substantial financial interconnectedness means that the upcoming changes will not be a minor adjustment for Swiss banks but rather a strategic imperative. The potential loss of direct access to EU clients without a local presence could translate into significant business disruption and a reevaluation of their market strategies.
The Core Business Mandate: What It Means in Practice
The definition of "core business" within the CRD VI framework is crucial. It explicitly includes deposit-taking, the provision of loans, and the issuance of guarantees. These are fundamental banking activities that form the bedrock of client relationships. For a German national holding a savings account, a checking account, or a mortgage with a Swiss bank, this directive means that if the Swiss bank does not establish a branch in Germany or another EU country by January 2027, it may no longer be legally permitted to offer these services to them.
This requirement necessitates substantial investment and strategic planning from non-EU banks. Establishing a fully operational branch in an EU country involves navigating complex regulatory landscapes, setting up physical infrastructure, hiring local staff, and adhering to EU-specific banking laws and supervisory frameworks. For many institutions, particularly those with a smaller footprint in the EU or those whose business models rely heavily on cross-border operations from their home base, this could present a significant hurdle.
Potential Implications for German Clients
The most immediate concern for German clients is the potential loss of access to their Swiss bank accounts. This could manifest in several ways:
- Account Closure: Banks that are unwilling or unable to establish an EU branch may be forced to close accounts held by EU residents. This could lead to a scramble for affected individuals to find alternative banking solutions.
- Service Limitations: Even if a bank establishes a branch, the range of services offered to EU residents might be restricted compared to what was previously available from their home country operations.
- Increased Costs: Setting up and maintaining a physical presence in the EU will likely incur additional operational costs for the banks, which could eventually be passed on to customers through higher fees or less competitive interest rates.
- Administrative Burden: German clients may face increased administrative requirements, such as new account opening procedures, updated identification protocols, and compliance with evolving data protection regulations within the EU.
The directive’s impact is not limited to individual depositors. Businesses in Germany that utilize Swiss banking services for international transactions, trade finance, or treasury management could also face disruptions. The ability to conduct seamless cross-border financial operations might be curtailed, potentially affecting their efficiency and competitiveness.
The Swiss Banking Sector’s Response and Proactive Measures
While the full extent of the impact is still unfolding, major Swiss banks are reportedly assessing the implications of CRD VI and formulating strategies to comply. Given Switzerland’s long-standing financial ties with the EU, it is highly probable that the larger institutions, such as UBS and Credit Suisse (now part of UBS), will opt to establish branches or subsidiaries in key EU markets like Germany, France, or Luxembourg. These established players possess the financial resources and operational capacity to navigate such regulatory shifts.
However, smaller and more specialized Swiss banks might face a more challenging decision. For them, the cost and complexity of setting up an EU branch might outweigh the benefits of serving a limited EU client base. In such cases, these banks might choose to cease offering services to EU residents altogether, leading to a consolidation or a shift in their target markets.
A Broader Regulatory Context: CRD VI and Beyond
CRD VI is part of a larger ongoing effort by global regulatory bodies to enhance the stability and integrity of the financial system. Following the 2008 global financial crisis, there has been a concerted push for greater oversight and more stringent capital requirements for banks worldwide. The CRD framework in Europe, which has evolved through multiple iterations, is a key component of this global regulatory push.
The directive’s focus on third-country branches is not entirely novel. Similar principles have been applied in other jurisdictions to ensure that foreign financial entities operating within their borders are subject to local oversight and consumer protection standards. The EU’s approach under CRD VI aims to create a level playing field, preventing regulatory arbitrage where non-EU banks could potentially offer services within the EU with less stringent oversight than their EU-based counterparts.
Looking Ahead: Adaptation and Opportunity
The implementation of CRD VI by January 2027 provides a clear timeline for Swiss banks and their EU clients to adapt. This period will likely see a flurry of strategic decisions and operational adjustments. For German clients, it presents an opportunity to review their existing banking relationships and explore alternative options. This could include seeking out EU-based banks that offer competitive services or, for those with substantial assets, considering wealth management solutions that are fully compliant with EU regulations.
The move also highlights the ongoing trend towards greater financial integration and regulatory harmonization globally. While Switzerland has long prided itself on its distinct financial landscape, the reality of operating in an increasingly interconnected world necessitates adaptation to international standards. The future of Swiss banking with respect to the EU market will likely involve a more collaborative and transparent relationship, driven by regulatory compliance and a shared commitment to financial stability. The directive, while posing challenges, may ultimately lead to a more secure and predictable financial environment for all parties involved. The coming years will be critical in determining how Swiss banks navigate this new regulatory terrain and how German consumers and businesses will manage their financial relationships across the evolving borders of European finance.








