Ena Muazin
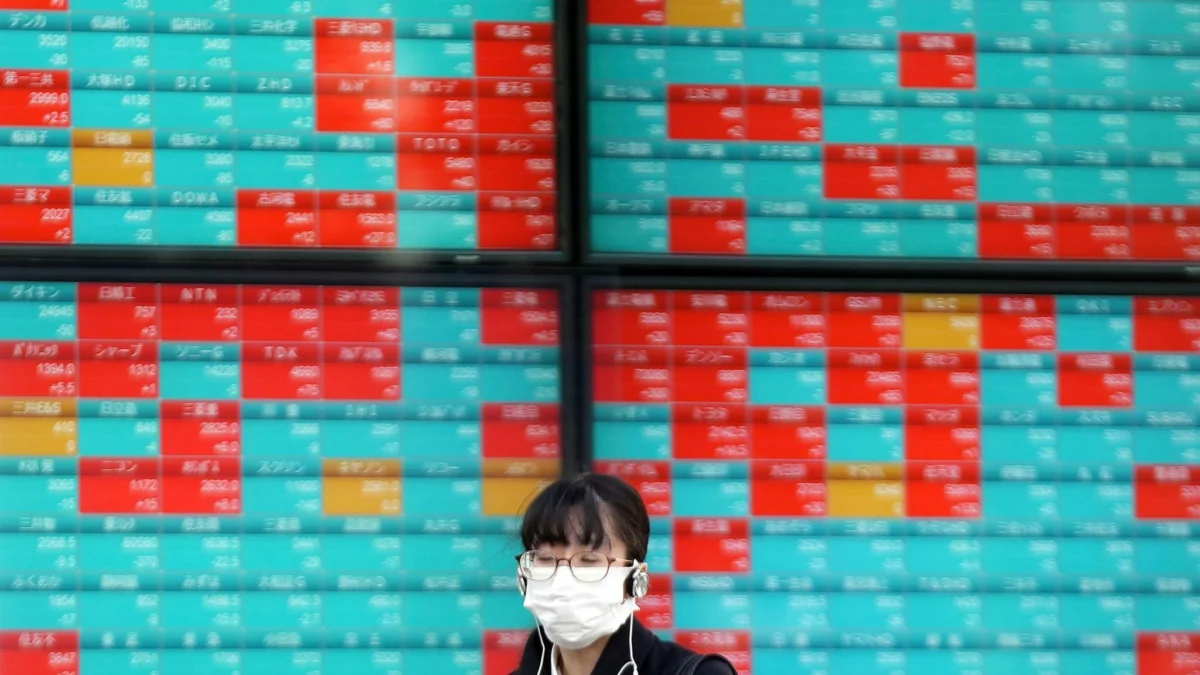
Asian stock markets experienced a mixed performance on Wednesday, with Japan’s indices buoyed by strong corporate earnings, particularly within the artificial intelligence (AI) sector, while China’s markets were weighed down by growing economic concerns. This divergence highlights the contrasting forces at play in the global economic landscape, with technological innovation offering a powerful tailwind for some regions, while broader macroeconomic challenges cast a shadow over others.
Japan’s Tech Rally Driven by AI and Space Exploration
The Nikkei 225 in Japan demonstrated notable strength, a testament to the robust performance of its leading companies. A significant driver of this positive sentiment was the anticipation of high demand within the artificial intelligence (AI) sector. This optimism was further amplified by encouraging financial disclosures from SpaceX, the American aerospace manufacturer founded by Elon Musk. SpaceX reported a more than doubling of its quarterly revenue, attributed to a booming AI and satellite business, and importantly, achieved profitability. This news not only injected confidence into the Japanese market but also underscored the global economic significance of AI-driven ventures.
The financial results from SpaceX, while not directly from a Japanese company, have a ripple effect across global technology markets. The company’s success in leveraging AI for its operations, from optimizing rocket launches to enhancing satellite communication services, signals a broader trend of AI integration across diverse industries. For Japan, a nation with a strong focus on technological advancement and a significant presence in the semiconductor and robotics industries, the success of companies like SpaceX serves as a powerful indicator of future growth potential. Investors are increasingly looking towards companies that can harness the power of AI to drive efficiency, innovation, and ultimately, profitability. This has led to increased investment in Japanese tech stocks, particularly those involved in AI research and development, advanced manufacturing, and related infrastructure.
The broader context for this AI-driven surge in Japan can be traced back to the country’s strategic initiatives aimed at fostering innovation and digital transformation. The Japanese government has been actively promoting research and development in AI, quantum computing, and other cutting-edge technologies. Furthermore, the global demand for advanced semiconductors, a critical component for AI development and deployment, has seen a significant uptick. Japanese companies, with their established expertise in semiconductor manufacturing and materials science, are well-positioned to benefit from this trend. The strong performance of these tech-oriented companies on the stock market reflects investor confidence in Japan’s ability to compete and lead in the global AI race.
China Faces Economic Headwinds and Sectoral Weakness
In stark contrast to Japan’s buoyant performance, Chinese stock markets experienced a downturn, primarily due to concerns surrounding the nation’s economic trajectory and disappointing corporate earnings. The performance of leading Chinese companies, particularly in sectors experiencing intense competition and softening consumer demand, has contributed to a general sentiment of risk aversion among investors.
A key factor weighing on the Chinese market was the disappointing quarterly performance of CATL (Contemporary Amperex Technology Co. Limited), the world’s largest battery manufacturer. CATL’s shares plunged by approximately ten percent after the company reported significantly slower profit growth in the third quarter. This deceleration in earnings growth is attributed to a confluence of factors, including intense competition within the electric vehicle (EV) battery market and a noticeable slowdown in auto sales within China. The Chinese automotive market, which has been a major engine of economic growth, is now facing headwinds from a combination of economic slowdown, shifting consumer preferences, and increased competition among domestic and international automakers.
The implications of CATL’s performance extend beyond the automotive sector. As a critical supplier of batteries for electric vehicles, its financial health is intrinsically linked to the future of sustainable transportation. The slowdown in China’s auto market, coupled with intense competition, suggests that the rapid expansion witnessed in previous years may be moderating. This could have knock-on effects for companies involved in battery production, raw material sourcing, and EV manufacturing. Investors are closely monitoring these developments, seeking clarity on the sustainability of growth in this vital sector.
Toymaker’s Slump Adds to Investor Caution
Adding to the prevailing risk aversion in China, the toy manufacturer Pop Mart also experienced a significant decline in its stock value, falling by four percent. Investors are expressing concerns that the company may report disappointing financial results for the third quarter. While seemingly a niche sector, the performance of consumer discretionary companies like Pop Mart can often serve as a barometer for broader consumer confidence and spending power. A weak performance from such a company can indicate underlying challenges in consumer sentiment, potentially stemming from economic uncertainties or shifts in purchasing behavior.
The context for Pop Mart’s potential struggles lies within the broader Chinese consumer market. While there are signs of recovery in certain segments, overall consumer spending has been impacted by a combination of factors, including the ongoing property market adjustments, global economic slowdown, and lingering effects of past COVID-19 restrictions. For companies reliant on discretionary spending, such as toy manufacturers, a cautious consumer base can translate into lower sales and reduced profitability. The market’s reaction to Pop Mart’s potential earnings miss underscores the sensitivity of investor sentiment to any indication of weakening consumer demand in the world’s second-largest economy.
Broader Economic Context and Market Outlook
The divergent performances in Asian markets reflect a complex global economic environment. While technological innovation, particularly in AI, offers compelling growth opportunities and drives investment in certain regions, persistent macroeconomic challenges continue to exert pressure on others.
In Japan, the strong performance of its tech sector can be seen as a positive signal for the country’s economic resilience and its ability to adapt to evolving global trends. The government’s continued focus on fostering innovation and attracting investment in high-growth sectors is likely to support sustained market performance. However, Japan is not immune to global economic uncertainties, and its export-oriented economy remains vulnerable to fluctuations in global demand and geopolitical events.
For China, the current economic headwinds present a significant challenge. The government is actively seeking to stimulate domestic demand, support key industries, and navigate the complexities of its property market. The success of these measures will be crucial in determining the future trajectory of its stock markets and its overall economic growth. The focus on quality growth over sheer expansion, coupled with efforts to diversify its economic base, are key themes that investors will be watching closely. The performance of its major industrial and consumer-facing companies will be a key indicator of the effectiveness of these policies.
Implications for Global Markets and Investors
The contrasting performances in Asia have broader implications for global markets and investors. The robust performance of AI-related stocks in Japan highlights the growing importance of technology as a driver of economic growth and market returns. Investors seeking exposure to this trend may continue to favor markets with strong technological capabilities and supportive government policies.
Conversely, the challenges faced by China underscore the importance of understanding and navigating macroeconomic risks. Investors in Chinese markets will need to closely monitor economic indicators, government policy announcements, and sector-specific developments to make informed investment decisions. The emphasis on domestic consumption and technological self-sufficiency will likely remain key themes for the Chinese economy in the coming years.
The global financial landscape is increasingly characterized by these dual forces of technological advancement and macroeconomic uncertainty. The ability of companies and economies to adapt to these evolving dynamics will be critical for their long-term success. As investors assess their portfolios, a nuanced understanding of these divergent trends across different regions and sectors will be paramount. The coming months will likely see continued volatility as markets grapple with inflation concerns, interest rate policies, and the ongoing geopolitical landscape, all of which will influence the trajectory of Asian equity markets and their global counterparts. The interplay between innovation and economic stability will remain a central theme in financial reporting and investment strategy.