Gilang Muhammad
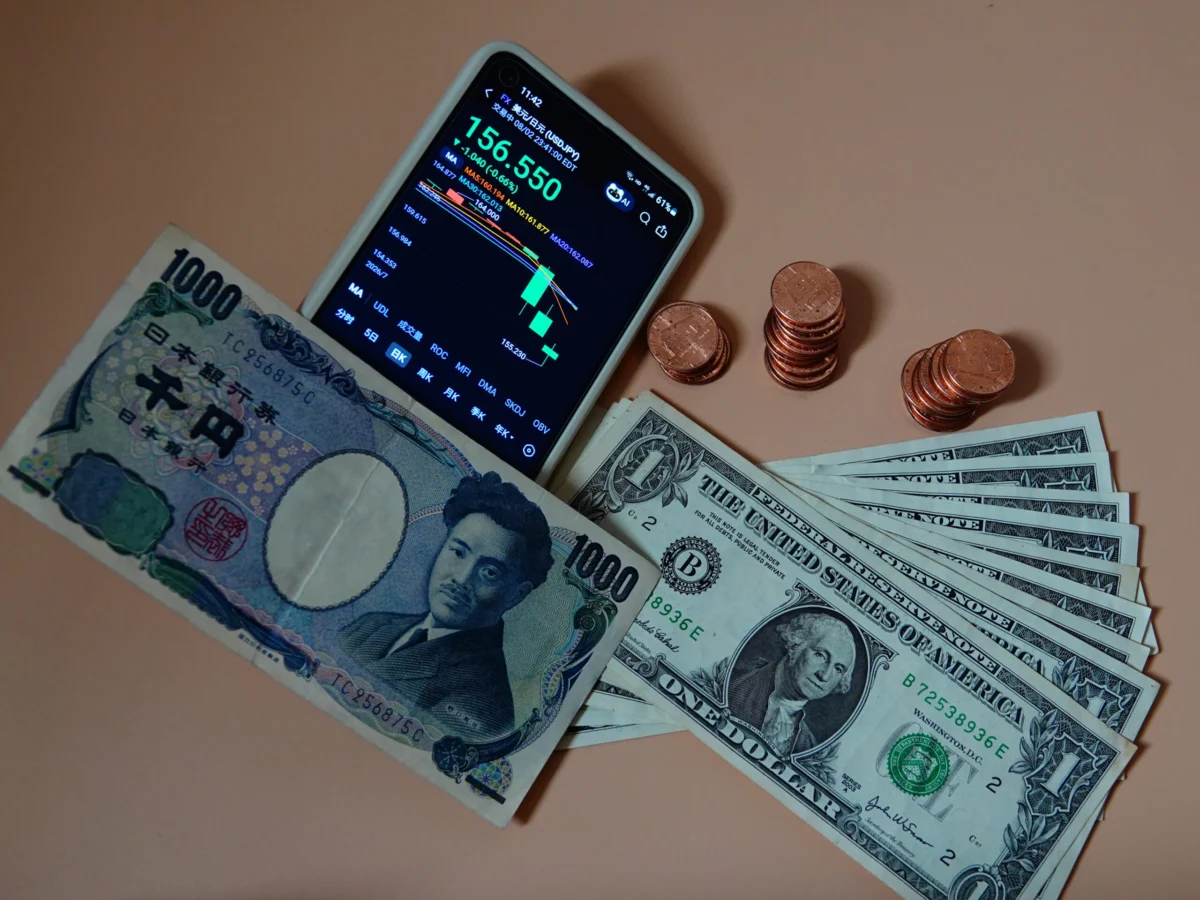
Japan’s foreign reserves experienced their steepest decline since the Ministry of Finance began compiling records in 2000, plummeting by a substantial 6.18% in August. This unprecedented contraction, representing a significant drawdown of the nation’s financial buffers, is primarily attributed to Tokyo’s vigorous efforts to stem the precipitous depreciation of the Japanese yen through large-scale currency market interventions, coupled with a simultaneous decline in the value of its holdings of foreign government bonds. The finance ministry’s latest data, released recently, revealed that foreign reserves stood at $1.207 trillion at the end of August, a sharp decrease from July’s figure of $1.287 trillion. This marks the fourth consecutive month of decline, surpassing the previous record drop of 5.58% recorded in May, underscoring the extraordinary pressures currently facing the Japanese currency and its policymakers.
Unprecedented Intervention Efforts to Stabilize the Yen
While the Ministry of Finance refrained from explicitly stating the reasons behind the dramatic fall, a common practice to maintain the effectiveness of currency operations, Japanese media outlet Kyodo News cited an unnamed finance ministry official who confirmed that the primary drivers were indeed interventions aimed at propping up the beleaguered yen. The official also pointed to a concurrent decline in the market value of government bonds held in the reserves, a consequence of rapidly climbing global yields. This dual impact has exerted significant pressure on Japan’s substantial foreign asset portfolio.
The yen’s prolonged weakness, which saw it touch a fresh 40-year low of 163.98 against the U.S. dollar on July 23, has been a persistent source of concern for Japanese authorities. A weaker yen inflates the cost of imports, exacerbating inflationary pressures in a nation heavily reliant on imported energy and raw materials, and can erode the purchasing power of Japanese consumers. In response, Tokyo has embarked on multiple rounds of foreign exchange interventions over the past several months, a strategy not seen on such a scale in decades.
These interventions involve the Ministry of Finance, acting through the Bank of Japan, selling foreign currencies (primarily U.S. dollars) and buying yen to increase demand for the domestic currency, thereby pushing its value higher. The scale of these operations has been immense. Data from the finance ministry indicates that approximately 11.73 trillion yen (equivalent to $75.26 billion at current exchange rates) was spent in April and May alone. This was followed by an even larger intervention of 15.4 trillion yen towards the end of July. Crucially, the late July intervention was notable for its coordinated nature, with the United States reportedly selling euros to supplement Japan’s efforts to support the yen, marking a significant, albeit rare, instance of international cooperation in currency markets.
The combined expenditure on currency intervention so far this year, totaling 27.1 trillion yen, has shattered previous records, surpassing the 2003 annual total of 20.4 trillion yen, which was the previous high-water mark for intervention spending. This historical comparison highlights the extraordinary nature of the current currency crisis and the determination of Japanese authorities to counter its effects.
A Rare Act of Bilateral Currency Coordination
The coordinated intervention with Washington in July was particularly significant, marking the first time the two economic powerhouses have jointly acted to support the yen since 1998. Such coordinated actions are rare and typically reserved for periods of extreme market volatility or when currency movements are deemed to pose a threat to global financial stability. The 1998 intervention occurred during the Asian Financial Crisis, underscoring the severity of the current situation from the perspective of both Tokyo and Washington. The decision to act together signals a shared concern over the yen’s rapid depreciation and its potential ramifications for global trade and financial markets. It also suggests that the U.S. recognized the potential for spillover effects from a destabilized yen, despite its general policy of non-intervention in currency markets. The immediate effect of these interventions, particularly the coordinated one, saw the yen rebound from its 40-year low of 163.98 on July 23 to its current trading level of 155.98 against the dollar, demonstrating the temporary effectiveness of such measures.
The Broader Economic Context: Global Bond Yields and Interest Rate Differentials
The yen’s persistent weakness is not solely a domestic issue but is deeply intertwined with global macroeconomic trends. A key factor has been the widening interest rate differential between Japan and other major economies, particularly the United States. While central banks in the U.S., Europe, and the UK have aggressively raised interest rates to combat inflation, the Bank of Japan (BoJ) has largely maintained its ultra-loose monetary policy, keeping its benchmark interest rate in negative territory and continuing its yield curve control program. This divergence in monetary policy makes yen-denominated assets less attractive to international investors compared to higher-yielding assets in other countries, leading to capital outflows and sustained selling pressure on the yen.
Adding to Japan’s challenges, global bond yields have been climbing to multi-year highs across developed markets. Yields on government bonds in Germany, the UK, and U.S. Treasuries have all hit sharp milestones recently, reflecting persistent inflation concerns and expectations of tighter monetary policy from their respective central banks. As global bond yields rise, the value of existing bonds with lower fixed interest rates, which form a significant portion of Japan’s foreign reserves, naturally declines. This phenomenon contributes directly to the reported drop in the value of Japan’s foreign reserves, as the holdings are marked to market. For instance, if Japan holds a substantial amount of U.S. Treasury bonds, and U.S. Treasury yields rise, the market value of those bonds decreases, leading to a reduction in the overall reported value of Japan’s foreign reserves, even if the quantity of bonds held remains the same.
Masahiko Loo, a senior fixed income strategist at State Street Investment Management, affirmed this analysis, telling CNBC that the "decline is primarily the result of Japan’s recent dollar-selling, yen-buying FX interventions." He elaborated that while the direct impact of selling dollars to buy yen reduces the dollar component of reserves, the concurrent depreciation in the value of other reserve assets, particularly U.S. Treasury bonds, due to rising yields globally, also plays a significant role. This dual pressure creates a formidable challenge for the Ministry of Finance as it seeks to manage both currency stability and the value of its sovereign wealth.

The Composition and Purpose of Japan’s Foreign Reserves
Japan’s foreign reserves are among the largest in the world, historically providing a robust buffer against external shocks and underpinning confidence in the nation’s financial stability. These reserves primarily consist of foreign currency-denominated assets, including U.S. Treasury bonds, corporate bonds, deposits with foreign central banks and commercial banks, gold, and special drawing rights (SDRs) from the International Monetary Fund (IMF). Their primary purposes include:
- Maintaining Currency Stability: As seen in recent months, reserves are used to intervene in foreign exchange markets to smooth out excessive currency fluctuations.
- Servicing Foreign Debt: Although Japan’s foreign debt is relatively small compared to its reserves, these assets can be used for debt obligations.
- Import Financing: Reserves can be drawn upon to pay for essential imports during times of crisis.
- Building Investor Confidence: A large reserve pool signals a nation’s financial strength and its ability to withstand economic shocks, attracting foreign investment.
The rapid depletion of these reserves, while a policy choice, raises questions about the sustainability of such interventions and the long-term impact on Japan’s financial firepower.
Implications for Japan’s Economy and Future Policy Direction
The record decline in foreign reserves, while a direct consequence of policy action, carries several implications for Japan’s economy and future policy considerations.
Inflationary Pressures: The weak yen has already fueled import-driven inflation, a phenomenon largely welcomed by the Bank of Japan in its long-standing fight against deflation. However, if the depreciation becomes too rapid or excessive, it can lead to "bad inflation," where rising import costs outpace wage growth, eroding household purchasing power and potentially stifling domestic demand. This delicate balance is a key concern for policymakers.
Trade Dynamics: A weak yen typically makes Japanese exports cheaper and more competitive in international markets, benefiting export-oriented industries. Conversely, it makes imports more expensive. While this might improve Japan’s trade balance in the short term, the reliance on imported energy and raw materials means the cost of inputs for manufacturers also rises, potentially offsetting some of the export gains.
Corporate Earnings: Japanese corporations with significant overseas operations or foreign currency revenues tend to benefit from a weak yen when repatriating profits. However, companies heavily reliant on imports or with substantial foreign currency-denominated debt can face increased costs.
Sustainability of Interventions: While Masahiko Loo of State Street dismissed immediate concerns about financial stress, emphasizing that the decline "reflects policy action rather than financial stress," the finite nature of foreign reserves means interventions cannot continue indefinitely at the current pace. The Ministry of Finance will need to carefully weigh the effectiveness of future interventions against the depletion of its reserves. Should the yen resume its sharp depreciation, the MoF’s capacity for sustained action could come under scrutiny, potentially requiring more fundamental policy adjustments.
Monetary Policy Crossroads: The BoJ faces a complex dilemma. While its ultra-loose monetary policy is a primary driver of yen weakness, a premature pivot to tightening could derail the nascent economic recovery and risk pushing the economy back into deflationary territory. However, the pressure from the yen’s depreciation and the Ministry of Finance’s costly interventions could eventually force the BoJ to re-evaluate its stance, potentially leading to adjustments in its yield curve control policy or even an eventual rate hike. The market is closely watching for any signals of a shift, which could have significant implications for global capital flows and asset prices.
Global Economic Stability: The coordinated intervention with the U.S. underscores that the yen’s stability is not merely a Japanese concern but a matter of broader international economic interest. Sustained volatility in a major currency like the yen can have ripple effects on global trade, investment, and financial markets, potentially impacting other economies and central bank policies. The decision by the U.S. to engage in joint action signals a recognition of these interconnected risks.
In conclusion, Japan’s record decline in foreign reserves in August is a stark illustration of the intense battle being waged by Tokyo against a rapidly weakening yen. Driven by massive currency interventions and the broader impact of rising global bond yields, this drawdown highlights the formidable challenges posed by divergent monetary policies and global economic shifts. While the interventions have provided temporary relief for the yen, the sustainability of such actions and the potential for deeper policy adjustments by the Bank of Japan remain critical questions that will continue to shape Japan’s economic trajectory and influence global financial markets in the months to come. The current trading level of 155.98 against the dollar, while an improvement from its recent lows, still represents a significantly weaker yen than historical norms, indicating that the pressures are far from abated.