Farhan Pambudi
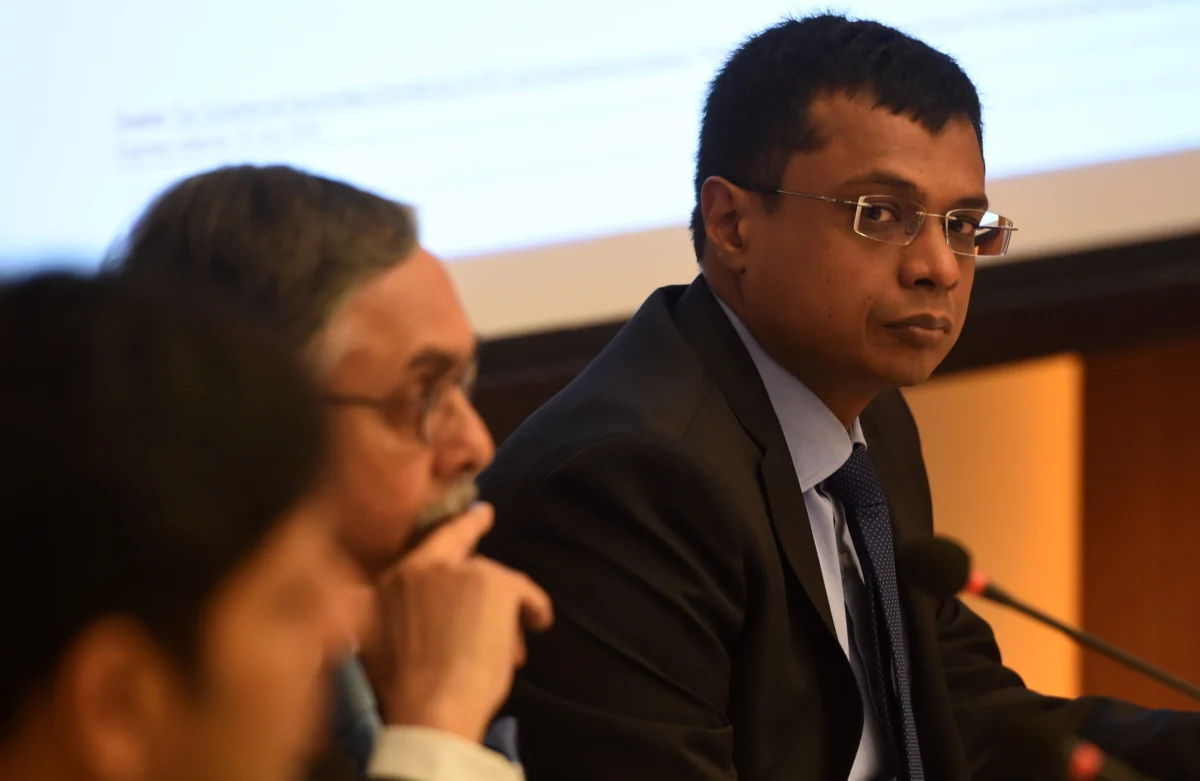
Indian fintech heavyweight Navi has secured $100 million in a fresh funding round led by global investment behemoth Prosus, marking a pivotal shift in the capital structure of the eight-year-old startup. This transaction represents the first time the company has accepted external institutional capital since its inception in 2018. Founded by Sachin Bansal, the billionaire co-founder of e-commerce giant Flipkart, Navi has historically been fueled primarily by Bansal’s personal wealth and internal accruals. The investment from Prosus values the Bengaluru-headquartered firm at approximately $1.3 billion, a figure that reflects both the company’s significant scale and the current recalibration of valuations within the global technology sector.
The capital infusion arrives at a critical juncture for Navi as it navigates a complex path toward a planned initial public offering (IPO). Earlier in 2024, the startup had reportedly sought a valuation closer to $2 billion while engaging with potential institutional backers. While the final $1.3 billion valuation represents a more conservative market assessment, the entry of Prosus—a seasoned investor in the Indian digital economy with stakes in firms like Swiggy and PayU—provides Navi with a significant "blue-chip" endorsement as it prepares to face public market investors.
The Genesis of Navi and the Bansal Legacy
To understand the significance of this funding round, one must look back at the trajectory of its founder, Sachin Bansal. After co-founding Flipkart in 2007 and steering it to become India’s premier e-commerce platform, Bansal exited the company in 2018 following its landmark $16 billion acquisition by Walmart. Leveraging the capital from his stake sale, Bansal immediately turned his attention to the financial services sector, identifying a massive gap in how credit, insurance, and investment products were delivered to India’s burgeoning middle class.
Navi was born out of this vision to build a "full-stack" financial services provider. Unlike many fintech startups that focus on a single niche—such as payments or wealth management—Navi was designed from the ground up to be a multi-product ecosystem. Bansal personally committed hundreds of millions of dollars into the venture, a move that allowed the company to bypass the traditional early-stage venture capital cycles and focus on rapid infrastructure building and regulatory compliance.
From its early days, Navi’s ultimate ambition has been to transform into a commercial bank. While the Reserve Bank of India (RBI) has historically maintained a cautious stance on granting banking licenses to corporate-backed entities, Navi has systematically built the necessary components of a bank, including a robust lending arm (Navi Finserv), a mutual fund business, and a general insurance vertical.
A Chronology of Growth and Strategic Pivots
Since 2018, Navi has undergone several phases of evolution, marked by aggressive expansion and occasional regulatory hurdles.
2018–2019: The Foundation
Following his exit from Flipkart, Bansal acquired Chaitanya India Fin Credit, a microfinance institution, to gain a foothold in the lending space. This acquisition provided the initial regulatory framework for what would become Navi’s lending operations.
2020–2021: Product Diversification
Navi launched its flagship app, offering personal loans with a completely digital, paperless process. During this period, the company expanded into the mutual fund space by acquiring Essel Mutual Fund and launched its home loan and health insurance products.
2022: The First IPO Attempt
In March 2022, Navi filed preliminary papers with the Securities and Exchange Board of India (SEBI) for a ₹4,000 crore (approximately $440 million) IPO. However, the plan was eventually shelved in 2023. The withdrawal was attributed to a broader slump in the global IPO market and a tightening of liquidity, which saw several Indian startups delay their public debuts.
2023–2024: Scaling UPI and Credit
Navi shifted its focus toward the Unified Payments Interface (UPI) ecosystem. By offering a seamless payment experience integrated with its lending products, the app saw a meteoric rise in transaction volumes, eventually securing its position as one of the top UPI service providers in the country.
2025–2026: The Road to Institutional Funding
Recognizing the need for a diversified cap table ahead of a public listing, Navi began active negotiations with institutional investors. The culmination of these efforts is the $100 million investment from Prosus, setting the stage for the company’s 2026 fiscal objectives.
Financial Performance and Operational Metrics
Navi’s financial trajectory illustrates the high-growth, high-burn nature of the Indian fintech landscape. For the financial year ending March 2026, the company reported consolidated revenue of ₹30.91 billion (approximately $323.33 million). While this represents a significant increase in top-line growth, the company’s net loss also expanded to ₹4.66 billion (around $48.74 million), driven by aggressive customer acquisition costs and investments in technology infrastructure.
Despite the annual loss, there are signs of an operational turnaround. Navi management stated that the company reached consolidated profitability in the fourth quarter of fiscal 2026. This milestone is crucial for its IPO aspirations, as public market investors in India have recently shown a strong preference for companies with a clear and demonstrated path to sustained profitability.
The lending arm, Navi Finserv, remains the primary engine of the company’s revenue. It currently manages assets under management (AUM) exceeding ₹130 billion (approximately $1.4 billion). The firm’s ability to maintain low delinquency rates while scaling its loan book will be a key metric for investors in the coming years.
Dominance in the UPI Ecosystem
One of Navi’s most notable achievements in recent years is its rapid ascent in the UPI payments space. In a market dominated by incumbents like Walmart-owned PhonePe and Google Pay, Navi has managed to carve out a significant share, currently ranking as the fourth-largest UPI app in India.
According to data from the National Payments Corporation of India (NPCI), Navi’s app processed over 947 million transactions in July 2024 alone, with a total transaction value of ₹483.18 billion ($5.05 billion). This scale is not merely a vanity metric; it serves as a massive top-of-the-funnel engine for Navi’s high-margin products. By capturing users through daily payment transactions, Navi can more effectively cross-sell insurance, mutual funds, and personal loans, significantly reducing its blended customer acquisition cost.
Strategic Implications of the Prosus Investment
The entry of Prosus is more than just a financial transaction; it is a strategic alignment. Prosus brings a global perspective on fintech, having invested in various markets across Latin America, Southeast Asia, and Europe. For Navi, this partnership provides access to a wealth of data and best practices regarding risk management, cybersecurity, and scaling consumer tech platforms.
In a statement following the investment, Sachin Bansal characterized the deal as a “strong endorsement” of the institution Navi is building. He emphasized that the company values Prosus’s experience in scaling technology businesses globally. For Prosus, the investment allows it to double down on the Indian financial services sector, which remains one of the most attractive growth markets globally due to the ongoing digitalization of the economy and a massive under-penetrated population.
Analysis: The Path to the 2026 IPO
Navi is reportedly preparing to go public with a target of raising ₹30 billion (about $314 million). This second attempt at an IPO will be scrutinized closely by the market. Several factors will determine its success:
- Regulatory Landscape: The RBI’s evolving regulations on digital lending and "first-loss default guarantees" (FLDG) will impact Navi’s margins. Furthermore, the company’s long-term goal of obtaining a universal banking license remains a "wildcard" that could drastically re-rate its valuation.
- Credit Quality: As Navi scales its AUM to $1.4 billion and beyond, its proprietary AI-driven underwriting models will be put to the test. Maintaining asset quality in a fluctuating interest rate environment is paramount.
- The "Bansal Premium": Sachin Bansal’s reputation as a builder of world-class Indian technology companies remains a significant draw for investors. However, the transition from a founder-led, privately funded entity to an institutionally backed, publicly traded company requires a shift in governance and transparency.
- Competitive Pressure: While Navi is currently the fourth-largest UPI app, the gap between it and the top two players (PhonePe and Google Pay) remains vast. Additionally, the resurgence of Paytm and the entry of Jio Financial Services into the lending and insurance space present formidable challenges.
Broader Impact on the Indian Fintech Ecosystem
The Navi-Prosus deal sends a positive signal to the broader Indian startup ecosystem, which has faced a "funding winter" over the past two years. It demonstrates that high-quality assets with significant scale and a path to profitability can still attract major international capital, even if at more grounded valuations than the "peak" of 2021.
As Navi moves toward its IPO, it serves as a bellwether for the "Flipkart Mafia"—the group of former Flipkart employees and founders who have gone on to start their own ventures. A successful public listing for Navi would validate the thesis that India can produce homegrown, full-stack financial institutions capable of competing with traditional legacy banks.
For now, the $100 million from Prosus provides Navi with the necessary runway to refine its unit economics and fortify its balance sheet. With hundreds of millions of users already on its platform and a diversified suite of financial products, Navi is no longer just a startup; it is a burgeoning financial powerhouse poised to redefine how 1.4 billion people spend, save, and borrow.