Gilang Muhammad
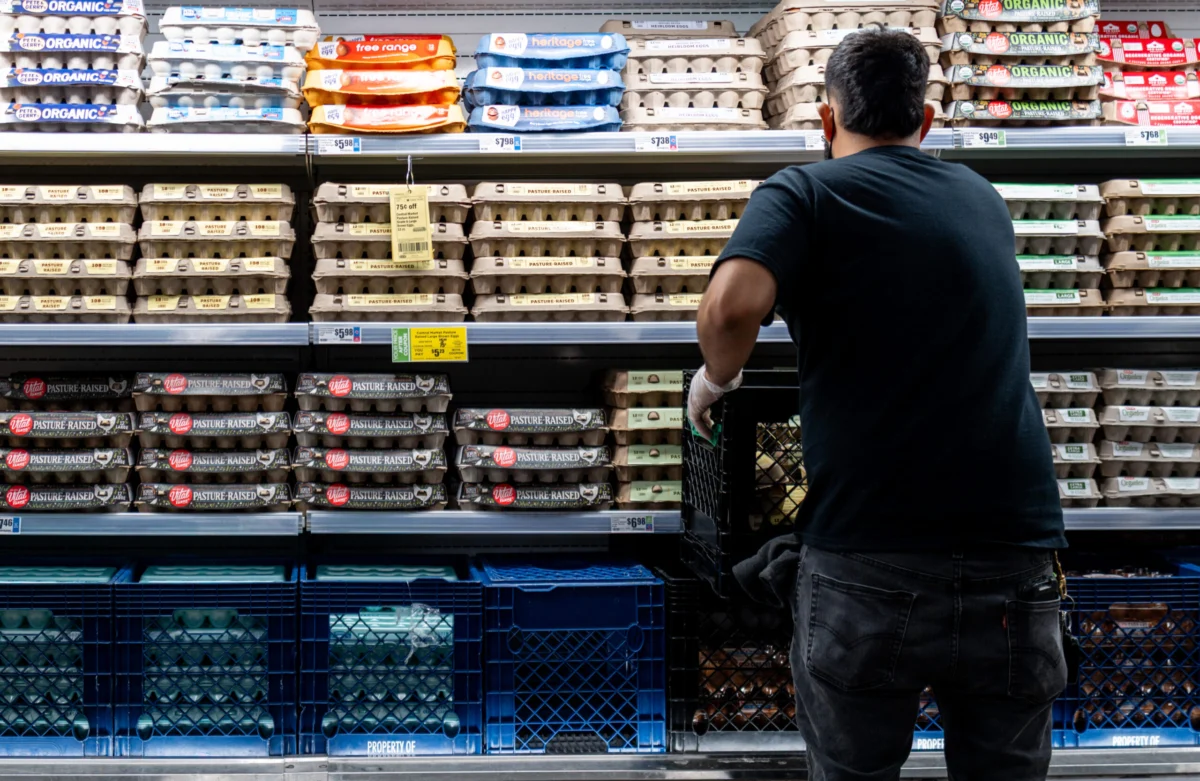
Costs for a broad array of goods and services across the U.S. economy surged more than anticipated in October, delivering a stark warning to the Federal Reserve in its protracted battle to curb inflation. The latest Consumer Price Index (CPI) data, released Tuesday by the Bureau of Labor Statistics (BLS), revealed a seasonally adjusted increase of 0.4% for the month, exceeding the 0.3% rise forecasted by economists surveyed by Dow Jones. This acceleration in price growth, particularly in core inflation, immediately reshaped market expectations for the central bank’s next monetary policy decision and cast a long shadow over the economic outlook.
A Deeper Dive into October’s Inflation Figures
The headline CPI’s 0.4% monthly increase in October represented a notable acceleration from economists’ predictions and signaled a stubborn persistence in inflationary pressures. Even more concerning for policymakers was the core CPI, which strips out the volatile food and energy components, rising by 0.3%. This figure also surpassed the consensus forecast of a 0.2% gain and matched the core increase recorded in September. The September report had seen the headline CPI jump by a more significant 0.6%, while core CPI held steady at 0.3%. The consistent upward trajectory, especially in core metrics, indicates that underlying price pressures remain robust, making the Fed’s task increasingly complex.
A critical nuance in this month’s report was the absence of an estimated yearly inflation rate. The BLS clarified that a government shutdown in October 2025 had prevented the collection of sufficient comparable data, thus precluding a standard year-over-year comparison for the overall index. This data gap, while not uncommon during such disruptions, complicates the long-term assessment of inflation trends for analysts and policymakers, forcing a greater reliance on monthly changes and available annual figures for specific components.
The Federal Reserve’s Critical Juncture and Waller’s Prophetic Warning
The October inflation report landed at an exceptionally sensitive moment for the Federal Reserve. For over five and a half years, inflation has consistently run above the central bank’s mandated 2% target, prompting an aggressive series of interest rate hikes aimed at cooling the economy and restoring price stability. The Fed’s dual mandate—to achieve maximum employment and stable prices—has been heavily skewed towards the latter in recent times, with officials repeatedly emphasizing their commitment to bringing inflation under control, even if it entails some economic slowdown.
Just hours before the BLS released its data, Federal Reserve Governor Christopher Waller, speaking in London on Tuesday morning, offered a prescient assessment of the central bank’s potential next steps. Waller explicitly stated that a "hot" inflation report could compel him to advocate for a half-point interest rate increase at the Fed’s upcoming December meeting. Crucially, he singled out a core CPI reading "around 0.3%" as a trigger for such a move. The subsequent release of the 0.3% core CPI figure transformed Waller’s speculative remark into an immediate and tangible policy consideration, underscoring the report’s gravity.
At their October 28, 2026, meeting, Federal Open Market Committee (FOMC) officials had voted 10-2 to maintain their benchmark interest rate within a range of 3.75%-4%. This decision reflected a cautious approach, allowing the Fed to assess incoming economic data before committing to further tightening. However, the unexpectedly strong October CPI data has now all but solidified market expectations for a rate hike in December, with the magnitude of that hike becoming the central point of contention.
Market Repercussions and Investor Sentiment Shift
The immediate aftermath of the CPI report saw a palpable shift in financial markets. Stocks across major indices experienced declines, reflecting investor apprehension about higher interest rates and their potential impact on corporate earnings and economic growth. Concurrently, Treasury yields, which move inversely to bond prices, jumped significantly as bond traders priced in a more aggressive Fed stance. This reaction underscored the market’s sensitivity to inflation data and its direct implications for borrowing costs.
Prior to the inflation release, the likelihood of a half-point rate hike in December, as gauged by the CME Group’s FedWatch tool, was negligible, hovering around zero. However, in the wake of the CPI figures, these odds surged to 13.6%, demonstrating a rapid recalibration of expectations. While a quarter percentage-point increase remains fully priced in for the Fed’s December 8-9 meeting, the increased probability of a more substantial move signals a growing concern that the Fed might need to act more forcefully to rein in prices.
Fixed income investment strategist Karen Manna of Federated Hermes encapsulated the market’s dismay, stating, "This was the report the market could least afford to see." Manna emphasized that a "hotter inflation print raises fresh questions about whether the Fed has done enough to contain price pressures and reinforces the risk that interest rates need to move higher and stay there for longer." This "higher for longer" narrative, suggesting that rates will not only rise further but also remain elevated for an extended period, has become a dominant theme in economic discourse, posing challenges for businesses, consumers, and government borrowing.
Dissecting the Inflationary Pressures: Sectoral Contributions
A detailed examination of the October CPI report reveals the multifaceted nature of the ongoing price pressures, with various sectors contributing to the overall increase:
- Energy: Despite recent declines in global crude oil prices and a general moderation in gasoline prices in the weeks leading up to the report, the energy index still rose by 0.7% for the month. The gasoline index specifically increased by 1%. This upward movement was partially offset by a 0.8% decrease in the natural gas index, likely reflecting seasonal demand shifts or increased supply. The underlying volatility in energy markets, often influenced by geopolitical events, remains a significant factor in headline inflation.
- Food Costs: Food prices continued their upward march, accelerating by 0.5% in October. This increase was broadly distributed across various categories, with notable jumps including 1% for snacks, 0.9% for beef, and 0.5% for the broader category of meats, poultry, fish, and eggs. These persistent increases directly impact household budgets and contribute to a sense of financial strain for consumers.
- Shelter: Housing costs remained a primary driver of inflation, with the shelter index rising by 0.3%. The BLS highlighted that shelter costs alone accounted for more than 30% of the overall headline CPI increase, underscoring its outsized influence on consumer expenses. This component, which includes rents and owners’ equivalent rent, tends to be sticky and lags broader economic trends, meaning its moderation often takes longer to materialize.
- Transportation Services: This category saw a significant jump of 0.8%. While new vehicle prices increased by a more modest 0.2%, the used cars and trucks index, which had been a major contributor to inflation earlier in the cycle, actually fell by 1.2%. The divergence suggests a normalization in certain vehicle markets but continued pressure in other transportation-related services. Airline fares also accelerated, rising by 0.4% in October, indicating strong demand in the travel sector.
- Other Categories: Apparel, a sector often sensitive to tariffs and global supply chain dynamics, showed a modest increase of 0.1%. Medical care commodities prices rose by 0.5%, reflecting ongoing cost pressures within the healthcare industry. The broad nature of these increases across various goods and services reinforces the notion that inflation is not confined to a few isolated sectors.
Broader Economic Drivers of Persistent Inflation
Beyond the immediate monthly fluctuations, several broader factors have been identified by Fed officials and economists as key contributors to the sustained inflationary environment. The original article highlights three critical elements:
- Geopolitical Instability (Iran War): The "Iran war" is cited as a significant contributor, likely referring to its impact on global energy markets and supply chains. Any conflict involving major oil-producing regions or critical shipping routes can disrupt the flow of commodities, drive up energy prices, and increase transportation costs for goods worldwide. This external shock can complicate domestic monetary policy efforts, as it is largely outside the Fed’s direct control.
- Trade Policy (Trump’s Tariffs): The lingering effects of President Donald Trump’s tariffs are also noted. Imposed primarily on goods from China, these tariffs increase the cost of imported raw materials and finished products for U.S. businesses and consumers. While some research, as mentioned by Philadelphia Fed President Anna Paulson, suggests these effects might be "beginning to fade," their cumulative impact over several years has undoubtedly contributed to higher input costs and consumer prices. The debate continues on how quickly these effects dissipate and whether they have become embedded in the broader economy.
- Technological Boom (AI Buildout): A newer, yet increasingly potent, inflationary pressure stems from "hyperscaler spending in the artificial intelligence buildout." The massive investment in AI infrastructure, including data centers and computing power, is driving up demand for electricity. This link was underscored by a 0.9% rise in electricity prices in October. The energy-intensive nature of AI development and deployment could create structural demand pressures on utility grids, potentially leading to sustained higher electricity costs for businesses and households alike.
These factors, combined with robust consumer demand and tight labor markets, have collectively kept inflation stubbornly elevated above the Fed’s 2% target for an extended period, now spanning approximately five and a half years.
Federal Reserve Officials Weigh In: Post-Report Perspectives
The October CPI report quickly prompted reactions from other influential Federal Reserve officials, further illuminating the central bank’s evolving strategy:
- Dallas Fed President Lorie Logan: Speaking shortly after the CPI data was released, Logan expressed her concern that the report was "higher than expected." She stated her view that the economy would likely need "two additional quarter-point increases" in the benchmark interest rate. Logan also voiced apprehension that the Personal Consumption Expenditures (PCE) price index—the Fed’s preferred inflation metric, which is typically released later in November—could also move higher, mirroring the CPI’s trend. Her remarks signaled a readiness to act more aggressively, suggesting that "it may be possible to move more rapidly this winter than the [Federal Open Market Committee] has moved so far this fall." Logan further articulated a strategy of implementing these two hikes, then pausing to "examine economic and financial developments to determine what further action may be appropriate."
- Philadelphia Fed President Anna Paulson: In her remarks later on Tuesday, Paulson echoed the sentiment that "inflation pressures are still very much with us." She identified tariffs, energy prices, and the AI buildout as the "main factors… keeping inflation elevated." While acknowledging research indicating that the effects from tariffs were "beginning to fade," she underscored the persistence of overall inflationary forces. Paulson concluded that "for now, further gradual tightening seems appropriate," but emphasized that "the exact path will depend on how conditions evolve, and I’ll be watching the data closely."
The statements from Logan and Paulson, while differing slightly in their proposed pace, collectively reinforce the Fed’s unwavering commitment to combating inflation. Both officials acknowledge the multifaceted nature of current price pressures, ranging from geopolitical and trade policies to technological advancements. Their comments suggest a Fed that remains data-dependent but is increasingly inclined towards continued tightening, with the December meeting now a focal point for assessing the exact trajectory of future rate hikes.
Consumer Behavior and Business Outlook: A Mixed Signal
Amidst the persistent inflation, consumer spending has demonstrated remarkable resilience. Retail sales, as reported by the Commerce Department, rose by 0.8% in September, indicating that consumers continue to open their wallets despite higher prices and rising interest rates. This sustained demand provides businesses with the ability to pass on increased costs, perpetuating the inflationary cycle.
Indeed, a survey conducted by the National Federation of Independent Business (NFIB) in October painted a clear picture of businesses’ intentions. A net 37% of responding businesses reported plans to raise prices in the next three months. This figure represents the highest level since July 2022, signaling that a significant portion of the business community anticipates continued cost pressures and intends to transfer these to consumers. Such forward-looking indicators suggest that the battle against inflation is far from over and that consumers may face further price hikes in the coming months.
The Road Ahead: Implications for Policy and Economy
The October CPI report has undeniably strengthened the case for a Federal Reserve interest rate hike in December. The debate has now shifted from whether the Fed will raise rates to by how much—a quarter-point or a half-point. The market’s quick adjustment to price in a higher probability of a more aggressive move underscores the report’s impact.
The implications of continued monetary tightening are profound. For consumers, higher interest rates translate to increased borrowing costs for mortgages, car loans, and credit card debt, potentially dampening future spending. For businesses, higher rates can curtail investment and expansion plans, leading to slower economic growth and, in some scenarios, job losses. The Fed faces a delicate balancing act: cooling the economy enough to tame inflation without triggering a severe recession.
The "higher for longer" narrative for interest rates is likely to gain further traction, suggesting that even after the current tightening cycle, rates may not return to the ultra-low levels seen in the past decade. This new interest rate environment will have lasting consequences for financial markets, corporate strategies, and household financial planning.
Looking forward, the Federal Reserve will closely monitor a range of incoming data, including the PCE price index, labor market statistics (such as unemployment rates and wage growth), and consumer sentiment surveys. The precise path of monetary policy will continue to be data-dependent, but the October CPI report has clearly tilted the scales towards a more hawkish stance, reinforcing the central bank’s resolve to achieve its elusive 2% inflation target. The fight against inflation remains the paramount economic challenge, and the coming months will be crucial in determining its trajectory and the broader economic consequences.