Gilang Muhammad
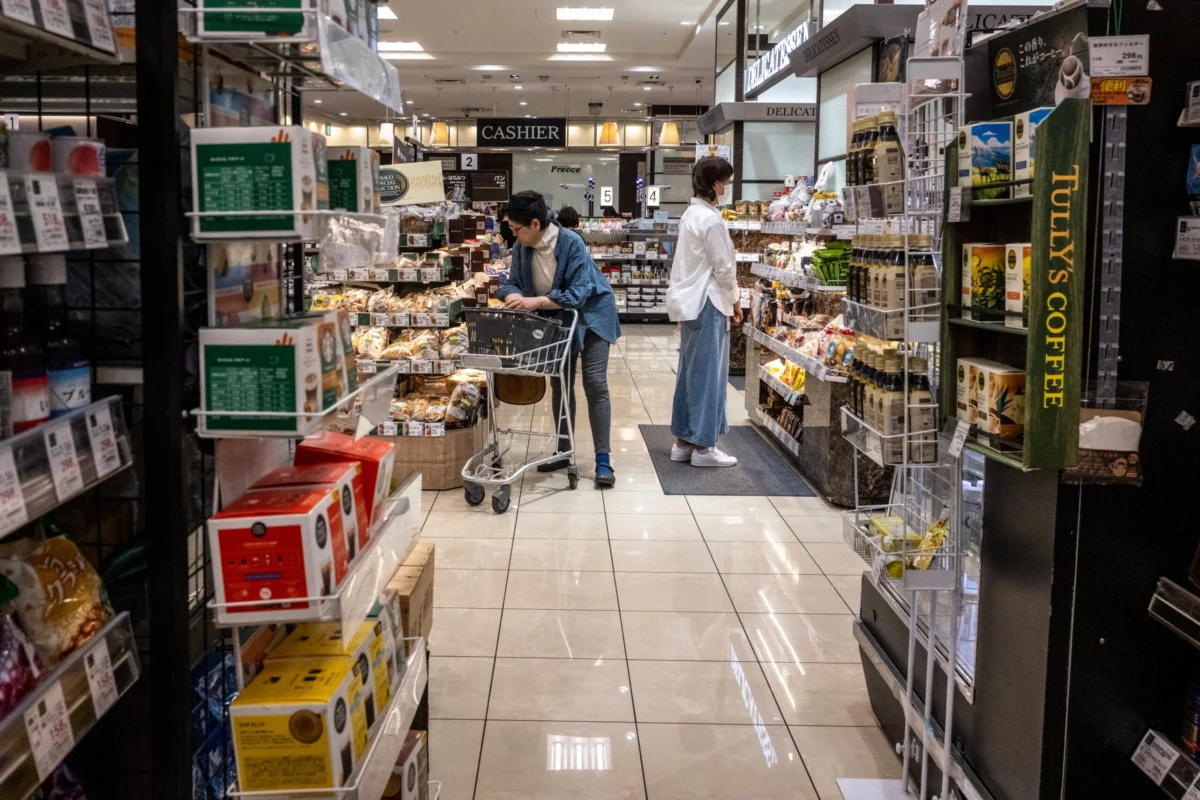
Tokyo, Japan – Japan’s core consumer inflation soared to a fresh high of 2.2% in October 2026, marking a significant escalation in price pressures driven primarily by surging energy costs and their widespread knock-on effects across the economy. This persistent inflationary trend is now widely expected to compel the Bank of Japan (BOJ) to implement another interest rate hike in December, despite an unexpected contraction in the nation’s economic growth during the third quarter. The latest government data, released on Friday, paints a complex picture for policymakers grappling with the dual challenge of taming inflation while nurturing a fragile recovery.
Unpacking the October Inflation Data
The October figures revealed a robust upward trajectory in prices. The core consumer price index (CPI), which excludes volatile fresh food prices, registered 2.2% year-on-year. While this figure came in slightly below the 2.3% anticipated by economists polled by Reuters, it represented an acceleration from the 2.1% recorded in September. This upward movement signifies that inflationary pressures are not only continuing but gaining momentum, penetrating deeper into the economic fabric.
Headline inflation, encompassing all items, also climbed, reaching 2.3% in October, up from 2.1% in the preceding month. This broad-based increase underscores the pervasive nature of rising costs. Interestingly, the so-called "core-core" inflation, which strips out both fresh food and energy prices, showed a slight dip to 2.2% from 2.4% in September. This divergence suggests that while underlying demand-side inflation might be moderating slightly, the primary impetus for the overall price surge remains firmly rooted in external factors, particularly energy. The sharp rebound in energy costs after a period of government intervention has proven to be the most significant driver of the current inflationary wave.
The Energy Cost Conundrum: Global Conflicts and Domestic Policy Shifts
At the heart of Japan’s escalating inflation lies a pronounced surge in energy prices, exacerbated by geopolitical tensions and the expiration of domestic relief measures. The primary catalyst for this acceleration has been identified as the "Iran war," a conflict that has significantly disrupted global energy markets and sent crude oil and natural gas prices climbing. As a nation heavily reliant on imported energy, Japan is particularly vulnerable to such international shocks, which directly translate into higher domestic costs for households and businesses alike.
The impact of these global dynamics was acutely felt in October following the expiration of government energy subsidies in September. These subsidies, initially introduced to cushion consumers from the brunt of rising import costs, had temporarily masked the true extent of inflationary pressures. With their removal, consumers were directly exposed to the elevated prices dictated by the international market.
The data unequivocally illustrates this dramatic shift:
- Overall Energy Prices: Climbed by a sharp 2.2% in October, a stark reversal from the 0.6% decline observed in September when subsidies were still active.
- Gas Prices: Experienced a significant jump of 5.8% year-on-year in October, accelerating from a 2.4% rise in the previous month.
- Fuel, Light, and Water Charges: Saw a considerable acceleration, increasing by 3.4% compared to September’s more modest 0.8% rise.
These figures highlight the direct transmission of higher international energy costs into everyday household expenses, squeezing disposable incomes and prompting widespread concern among consumers and policymakers. The government, acknowledging the severe impact on household budgets and economic activity, has reportedly approved the reintroduction of energy subsidies in December. This decision reflects a recognition that persistent high energy prices risk crimping economic growth by dampening consumption and negatively impacting net exports, thereby undermining broader recovery efforts. The Ministry of Economy, Trade and Industry (METI) has been central to these policy discussions, aiming to mitigate the impact of imported inflation on the domestic economy.
A Timeline of Policy Responses and Economic Shifts
Japan’s journey to its current inflationary environment is marked by a complex interplay of global events, domestic economic policies, and a decades-long struggle against deflation. For over two decades, Japan battled persistent deflation, a period characterized by falling prices, stagnant wages, and cautious consumer spending. The Bank of Japan’s long-standing 2% inflation target, a cornerstone of "Abenomics," remained elusive for years, often requiring aggressive monetary easing, including negative interest rates and massive asset purchases.
- Early 2020s: Global supply chain disruptions and the initial commodity price surges following various international events began to push Japan’s inflation rates upwards, albeit slowly.
- 2025: As global energy prices continued their ascent, the Japanese government introduced temporary energy subsidies to alleviate the burden on households and businesses. These measures were crucial in managing public sentiment and preventing a sharper downturn in consumption.
- September 2026: The government’s energy subsidies expired. This decision, likely influenced by fiscal considerations and a belief that inflationary pressures might be transient, coincided with a period of intensified geopolitical instability, specifically the "Iran war."
- October 2026: The full effect of subsidy expiration and global energy price hikes became evident in the inflation data, pushing core CPI to 2.2%. This marked a critical turning point, indicating that inflationary pressures were becoming more entrenched than initially anticipated.
- November 2026: Government data confirms the persistent inflationary trend. Reports emerge of the government approving the reintroduction of energy subsidies for December, signaling a pragmatic response to the unexpected severity of the energy crisis. This rapid policy reversal underscores the government’s heightened concern about the impact on economic growth and consumer welfare.
- December 2026 (Projected): The Bank of Japan is widely expected to react to these persistent inflationary pressures with another interest rate hike, a significant step in its ongoing process of monetary policy normalization.
This chronology highlights the reactive nature of policy in the face of rapidly evolving global economic conditions and the challenge of balancing fiscal sustainability with economic stability.
The Bank of Japan’s Tightrope Walk: Inflation vs. Growth
The October inflation reading places the Bank of Japan in an increasingly challenging position. For years, the BOJ maintained an ultra-loose monetary policy, including negative interest rates and yield curve control, to combat deflation and stimulate economic growth. Its 2% inflation target was often seen as an aspirational goal rather than an immediate threat. However, the current environment marks a distinct departure, forcing the central bank to pivot towards monetary policy normalization.
The latest inflation data, particularly the sustained rise in core CPI driven by energy, strengthens the case for a December rate hike. Data from LSEG indicates a substantial 75% chance of a 25 basis point hike from the Bank of Japan, reflecting market expectations of the central bank’s commitment to price stability.
However, this decision is complicated by an unexpected contraction in Japan’s economic growth during the third quarter. While specific figures for the Q3 GDP contraction were not provided in the original data, its occurrence presents a dilemma for the BOJ. Typically, a central bank might hesitate to tighten monetary policy when the economy is shrinking, fearing it could stifle growth further and potentially push the country into recession.
Despite this growth slowdown, analysts believe the BOJ will prioritize addressing inflation. Ma Tieying, a senior economist at DBS Group Research, articulated this sentiment in a recent note: "The BOJ is likely to look through the temporary weakness in 3Q GDP and focus instead on underlying inflation and wage dynamics." This perspective suggests that the central bank views the current inflationary impulse as a more pressing and potentially entrenched issue than the temporary dip in economic output. The BOJ’s long-term credibility hinges on achieving its inflation target sustainably, and allowing inflation to run unchecked could risk de-anchoring inflation expectations, leading to a more challenging fight down the road. The central bank will be closely monitoring wage growth, as sustained wage increases are crucial for transitioning from cost-push inflation to a more desirable demand-driven inflation that can support long-term economic health.
Broader Economic Implications: Households, Businesses, and the Yen
The persistent inflationary environment carries significant implications for various sectors of the Japanese economy:
- Households: Rising energy, fuel, light, and water charges directly impact household budgets, reducing disposable income and eroding purchasing power. Consumers, already cautious, may cut back on discretionary spending, which could further dampen overall consumption. The reintroduction of subsidies offers some relief but also signals the severity of the challenge. The psychological impact of rising prices, particularly after decades of stable or falling costs, can also lead to decreased consumer confidence.
- Businesses: Companies face higher input costs, particularly those reliant on energy for manufacturing, transportation, and operations. While some businesses may be able to pass these costs onto consumers through higher retail prices, others, especially in competitive sectors, might struggle to do so without losing market share. This can squeeze profit margins, potentially leading to reduced investment, hiring freezes, or even job losses in some vulnerable industries. Small and medium-sized enterprises (SMEs), which often have less pricing power and thinner margins, are particularly susceptible.
- The Yen: While not explicitly mentioned in the original text, the yen’s exchange rate often plays a crucial role in Japan’s import-driven inflation. A weaker yen makes imported goods, including energy and raw materials, more expensive in local currency terms, exacerbating inflationary pressures. The BOJ’s monetary policy decisions, especially relative to other major central banks, significantly influence the yen’s value. A rate hike could potentially strengthen the yen, offering some relief from imported inflation, but this effect is often counterbalanced by global market dynamics.
- Net Exports: Higher imported energy prices increase the cost of goods produced in Japan that rely on these inputs, potentially making them less competitive internationally. This, combined with any slowdown in global demand, could negatively impact Japan’s net exports, a key component of its GDP. The government’s concern that "higher prices crimp growth, hitting consumption and net exports" highlights this risk.
Historical Context: Japan’s Long Battle with Deflation
To fully appreciate the current situation, it is crucial to understand Japan’s unique economic history. For much of the late 20th and early 21st centuries, Japan grappled with a deflationary spiral. This period, often referred to as the "Lost Decades," saw prices stagnate or fall, leading to delayed purchases by consumers, reduced corporate investment, and ultimately, sluggish economic growth. The Bank of Japan implemented unconventional monetary policies, including quantitative easing and negative interest rates, in an unprecedented effort to reignite inflation and stimulate economic activity. The 2% inflation target, set in 2013 under former Prime Minister Shinzo Abe’s "Abenomics" policies, aimed to break this deflationary mindset.
The current inflationary environment, while challenging, represents a significant departure from this long-standing battle. It signifies that the economy is finally experiencing price increases, albeit primarily from external cost-push factors rather than robust domestic demand. This shift presents both opportunities—such as the potential for sustained wage growth if companies can pass on costs and improve profitability—and risks, particularly if inflation outpaces wage increases and erodes living standards. The BOJ’s task is to manage this transition carefully, ensuring that inflation becomes healthy and sustainable rather than a destructive force.
Looking Ahead: Uncertainties and Policy Outlook
The path forward for the Japanese economy remains fraught with uncertainties. The global geopolitical landscape, particularly the "Iran war," will continue to dictate international energy prices, which in turn will have a direct bearing on Japan’s inflation trajectory. The effectiveness and fiscal burden of the reintroduction of energy subsidies will also be closely watched, as these measures provide temporary relief but do not address the root causes of imported inflation.
For the Bank of Japan, the December rate hike is likely to be a crucial step in its gradual process of monetary policy normalization. However, the pace and extent of future hikes will depend on a careful assessment of inflation persistence, wage growth, and the overall health of the domestic economy. The central bank will need to balance its commitment to price stability with the imperative to support economic growth, especially in the face of potential headwinds such as the Q3 GDP contraction.
The ability of Japanese companies to achieve sustained wage increases will be paramount. If wage growth can keep pace with or even slightly exceed inflation, it could foster a virtuous cycle of increased consumer spending and demand-driven inflation, moving away from the current cost-push scenario. Conversely, if wages lag significantly, real incomes will decline, further suppressing consumption and risking a prolonged period of stagflation—a combination of stagnant growth and high inflation.
In conclusion, Japan’s October 2026 inflation figures underscore a complex and evolving economic landscape. While the shift from decades of deflation to a period of sustained inflation marks a significant turning point, the current pressures are largely external and cost-driven. The government’s rapid reintroduction of energy subsidies and the Bank of Japan’s likely December rate hike highlight the urgency with which policymakers are responding to these challenges, navigating a narrow path between controlling prices and fostering sustainable economic growth. The coming months will be critical in determining whether Japan can successfully anchor inflation expectations and transition to a more balanced and resilient economic future.