Ena Muazin
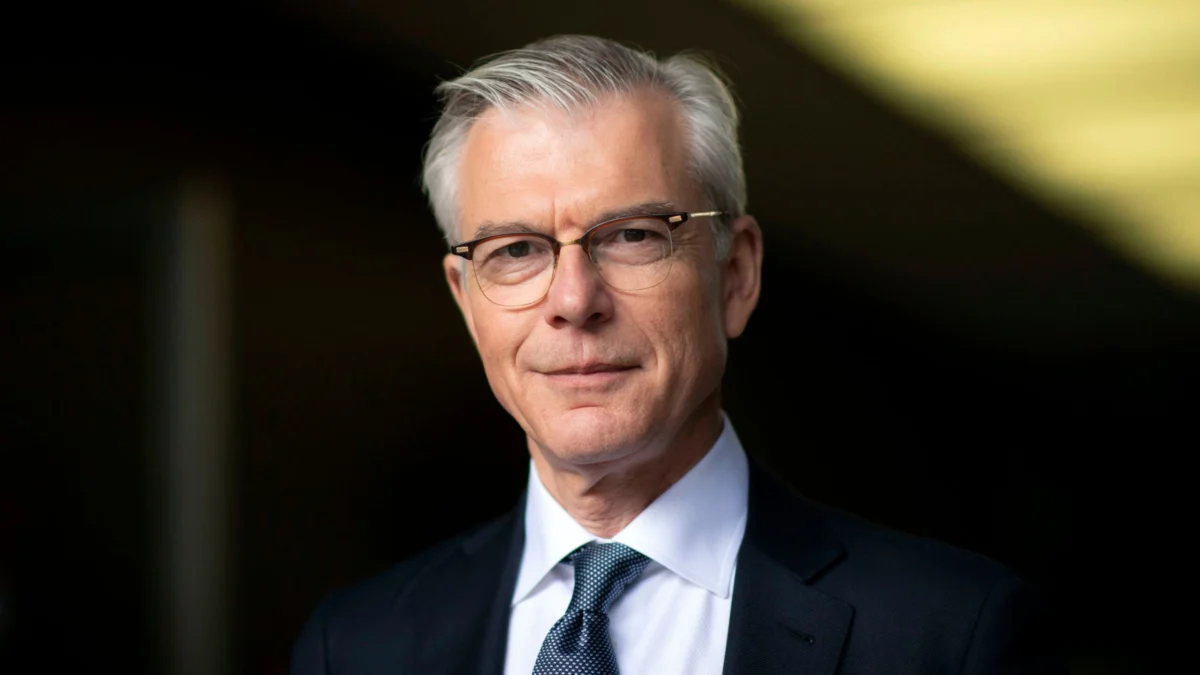
Professor Martin Werding, a prominent member of the German Council of Economic Experts (Sachverständigenrat) and a key figure behind the proposed Altersvorsorgedepot (retirement savings depot), has hailed the initiative as a significant advancement in making private retirement planning more accessible, profitable, and cost-effective. In an exclusive interview, Werding elaborated on the motivations behind the proposal, addressed potential concerns, and outlined his vision for a more robust and engaging private pension system for German citizens.
The Altersvorsorgedepot, a concept championed by economic advisors, aims to simplify the complex landscape of private retirement savings by offering a streamlined, investment-focused product. The core idea is to consolidate various existing private pension schemes into a more transparent and potentially higher-yielding option, primarily through investment in capital markets. This initiative comes at a time when Germany faces demographic challenges, with an aging population and increasing pressure on the public pension system.
Background and Rationale for the Altersvorsorgedepot
The impetus for the Altersvorsorgedepot stems from a growing consensus among economic policymakers that Germany’s current private pension system is overly complicated, suffers from high administrative costs, and often fails to deliver competitive returns for savers. The Sachverständigenrat, in its advisory capacity, has repeatedly highlighted the need for reforms that encourage greater participation in capital-backed retirement provisions.
Historically, Germany has relied heavily on its statutory pension insurance (gesetzliche Rentenversicherung) as the primary pillar of old-age security. However, projections indicate that this system alone will be insufficient to maintain living standards for future generations of retirees. Consequently, the government has sought to bolster private and occupational pension schemes. Despite these efforts, uptake and satisfaction with existing products have remained moderate, often due to perceived complexity, opaque fee structures, and a lack of clear investment strategies.
The Altersvorsorgedepot is designed to address these shortcomings. By creating a standardized product with a focus on long-term investment, it seeks to:
- Enhance Simplicity: Reduce the number of choices and product variations available to consumers, making it easier to understand and select a suitable savings plan.
- Improve Profitability: Channel savings into investment vehicles, such as equity funds, with the potential for higher long-term returns compared to traditional savings products.
- Lower Costs: Streamline administrative processes and reduce management fees, ensuring that a larger portion of contributions goes towards actual savings and investments.
- Promote Engagement: Encourage more individuals, particularly those who are hesitant or undecided about private savings, to participate by offering a more appealing and understandable option.
Werding’s Perspective: A "Giant Leap" Forward

Professor Werding expressed strong satisfaction with the progress made towards realizing the Altersvorsorgedepot, describing it as a "giant leap in the right direction." He emphasized that the proposal aligns directly with the Sachverständigenrat’s long-standing recommendations for reforming private old-age provision.
"In many respects, yes," Werding stated when asked about his satisfaction with the current developments. "The Council of Economic Experts had called for private retirement provision to become simpler, more return-oriented, and more cost-effective before the reform. Now, we have taken giant steps in this direction."
This optimistic outlook underscores the belief that the Altersvorsorgedepot has the potential to fundamentally improve the retirement savings landscape in Germany. By addressing the key barriers that have historically hindered participation in private pensions, the initiative aims to empower more individuals to secure their financial future.
The Voluntary Nature and the Opt-Out Debate
While the Altersvorsorgedepot is envisioned as a voluntary option, Professor Werding also touched upon a related discussion concerning the broader need for more binding capital-backed savings. He noted that the Council had also advocated for capital-backed provisions to become more binding, ideally with an opt-out mechanism, to include those who are undecided.
"The retirement savings depot is voluntary," Werding clarified. "However, the Council also said that capital-backed provision should become more binding, preferably with an opt-out, to include the undecided. There are many among them who will urgently need an additional pension."
This point highlights a nuanced perspective. While the depot itself is optional, Werding suggests that a more automated or default approach could be beneficial for a significant segment of the population. The "opt-out" model, as opposed to an "opt-in" system, would mean that individuals are automatically enrolled in a retirement savings plan unless they actively choose to opt out. This approach is rooted in behavioral economics, recognizing that inertia can be a powerful force in decision-making.
Lessons from International Models: The Swedish Example
Professor Werding drew a parallel to the Swedish pension system, which has been cited as a successful model for integrating capital-backed savings into retirement planning. In Sweden, a portion of mandatory contributions is automatically invested in a state-managed fund or can be directed to privately managed funds, offering a clear, albeit limited, choice.
"If you pay in automatically, the hurdle to cancel is high," Werding explained, referencing the behavioral insights gained from the Swedish experience. "We know this from behavioral research and from practice. In Sweden, participation is mandatory; such a model has now been recommended by the Commission on Aging Security."
The Swedish system’s success in increasing participation and ensuring that a substantial portion of the population benefits from capital market returns serves as a compelling case study for Germany. The key takeaway is that automatic enrollment, coupled with clear and cost-effective investment options, can significantly boost engagement and improve retirement outcomes.
Navigating the Challenges: Where Savers Must Be Vigilant

While optimistic about the Altersvorsorgedepot, Professor Werding also cautioned that savers must remain vigilant and informed. He emphasized that even with a simplified product, understanding investment risks and costs remains crucial.
"When saving, savers must be careful," Werding advised, suggesting that transparency regarding fees and investment performance will be paramount. The Altersvorsorgedepot aims to simplify this by offering standardized fee structures, but individual investment choices within the depot will still carry inherent risks.
Key areas where savers should exercise caution include:
- Investment Horizon: Understanding that capital market investments are best suited for long-term savings goals, typically spanning decades, to smooth out market volatility.
- Risk Tolerance: Assessing personal comfort levels with investment risk. While the depot aims for higher returns, this often comes with greater potential for short-term fluctuations.
- Fee Structures: Even with reduced costs, it is essential to understand the specific fees associated with any chosen investment strategy within the depot.
- Market Performance: Recognizing that investment returns are not guaranteed and can fluctuate based on economic conditions.
Implications for the German Economy and Society
The successful implementation of the Altersvorsorgedepot could have far-reaching implications for the German economy and society.
- Strengthened Retirement Security: A more robust private pension system could help alleviate future burdens on the state pension and social welfare systems. This is particularly crucial as Germany’s population continues to age, with the dependency ratio (the ratio of non-working to working-age individuals) expected to rise. Data from Destatis (the German Federal Statistical Office) consistently highlights the demographic shift, with projections indicating a shrinking workforce and an increasing number of retirees in the coming decades.
- Increased Capital Market Depth: A greater flow of savings into capital markets could enhance the depth and liquidity of these markets, potentially fostering economic growth and investment opportunities. This could also reduce Germany’s reliance on external financing for its businesses.
- Financial Literacy and Empowerment: The initiative, if accompanied by effective public education campaigns, could contribute to improved financial literacy among the population, empowering individuals to make more informed decisions about their long-term financial well-being.
- Reduced Inequality: By providing a more accessible and potentially profitable savings vehicle, the Altersvorsorgedepot could help reduce intergenerational inequality and ensure that more people can enjoy a comfortable retirement, regardless of their initial income level.
The Road Ahead: From Concept to Implementation
The development of the Altersvorsorgedepot is not a singular event but rather a process that involves legislative action, regulatory frameworks, and market adaptation. The concept, having been put forth by influential economic bodies like the Sachverständigenrat, now requires concrete political decisions and the establishment of the necessary legal and operational structures.
The timeline for full implementation will likely involve several stages:
- Legislative Proposals: The government will need to introduce and pass legislation to formalize the Altersvorsorgedepot and its operational guidelines.
- Regulatory Framework: Financial regulators will establish the specific rules and oversight mechanisms for providers offering the Altersvorsorgedepot.
- Product Development: Financial institutions will develop and offer the actual savings products that meet the criteria for the Altersvorsorgedepot.
- Public Awareness and Education: Comprehensive campaigns will be necessary to inform the public about the new option, its benefits, and how to engage with it.
The "tank rebate" mentioned in the original article context likely refers to a past economic stimulus or policy measure. If Professor Werding were to suggest how funds from such a rebate could be utilized in the context of the Altersvorsorgedepot, he might advocate for using any surplus funds or savings from such a measure to directly contribute to a personal Altersvorsorgedepot. This would serve a dual purpose: immediate economic stimulus through increased savings and investment, and long-term financial security for individuals.
Conclusion
Professor Martin Werding’s endorsement of the Altersvorsorgedepot signifies a crucial step in Germany’s ongoing efforts to modernize its retirement savings system. By emphasizing simplicity, profitability, and cost-effectiveness, the initiative aims to address long-standing challenges and encourage greater participation in private old-age provision. While the voluntary nature of the depot is acknowledged, the discussion around opt-out mechanisms and lessons from international models like Sweden underscore a broader ambition to ensure that more Germans are adequately prepared for their retirement years. As the concept moves closer to implementation, continued vigilance from savers regarding investment risks and costs, alongside robust public education, will be essential to realizing the full potential of this promising reform. The success of the Altersvorsorgedepot could mark a pivotal moment in securing the financial future of generations to come in Germany.