Gilang Muhammad
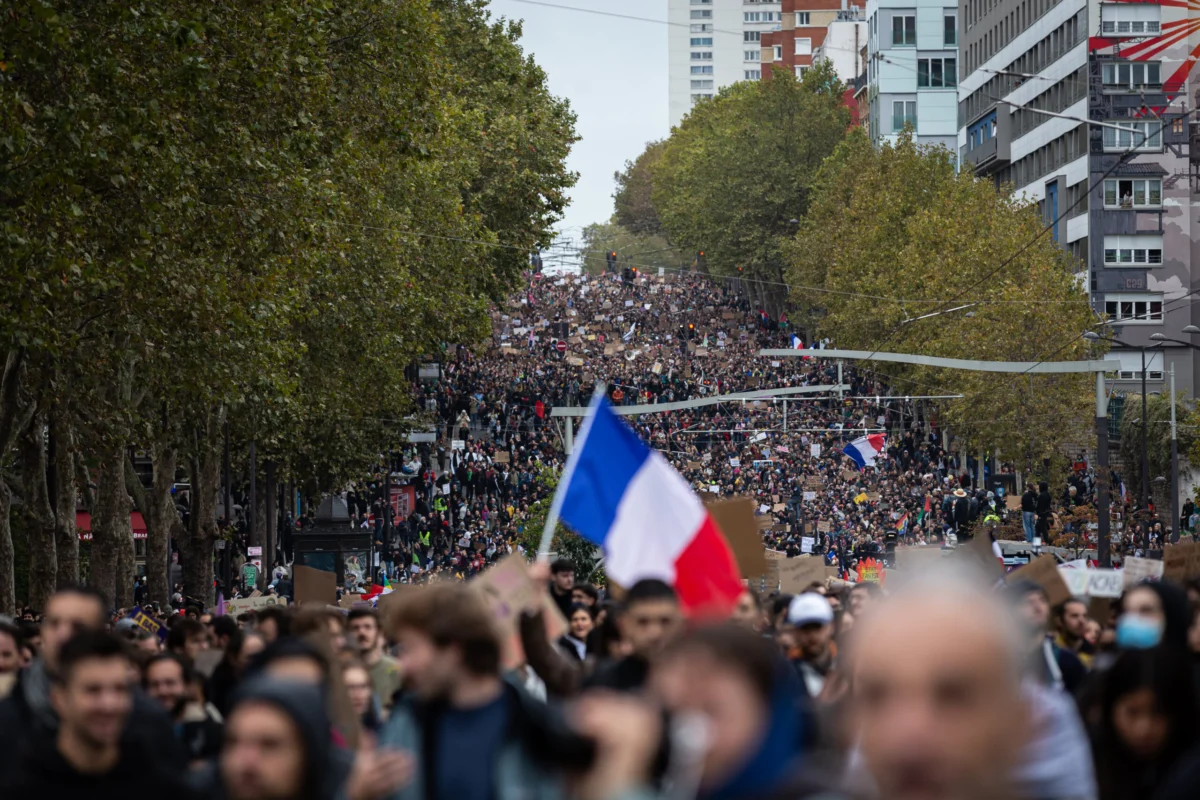
The Eurozone’s economic expansion decelerated to a modest 0.4% in the third quarter of 2026, a slowdown confirmed by Eurostat on Friday, October 29. This comes as France, the bloc’s second-largest economy, unexpectedly contracted by 0.1% over the July to September period, fueling widespread national protests that drew an estimated 800,000 people across the country, including 250,000 in Paris, according to the CGT union. These demonstrations, escalating at times into violent and costly rioting, underscore deep-seated public discontent over the cost of living, government policies, and the nation’s mounting debt crisis, which has simultaneously led to soaring borrowing costs. The European Central Bank (ECB), meeting earlier this week, opted to hold interest rates steady, acknowledging increased downside risks to growth while maintaining vigilance against persistent inflationary pressures.
France Gripped by Social Unrest and Economic Contraction
France finds itself at a critical juncture, grappling with both a contracting economy and intensifying social unrest. The nationwide protests on October 24, 2026, were a potent display of public frustration, with hundreds of thousands taking to the streets. In Paris, the march, which began at 2 pm from the Porte d’Italie and was directed towards the Porte de Vincennes, faced a last-minute route alteration by the Police Headquarters, a move that often heightens tensions between demonstrators and authorities. Organized primarily by major trade unions like the CGT, these protests represent a broad coalition of concerns ranging from stagnant wages and the erosion of purchasing power due to high inflation to contentious government reforms and perceived inequalities.
The economic backdrop to this social upheaval is stark. France’s unexpected 0.1% contraction in the third quarter stands in sharp contrast to the broader Eurozone’s albeit slower growth. This downturn is attributed to a confluence of factors, including weak consumer spending, cautious business investment, and the disruptive impact of ongoing strikes and protests on various sectors, from transportation to public services. For instance, preliminary estimates suggest that industrial output saw a marginal decline, and retail sales volumes struggled to gain traction as household budgets tightened. Annual inflation in France, while showing signs of moderating from its peak earlier in the year, remains stubbornly high at around 4.8% in October, far outpacing wage increases for many workers.
Adding to France’s economic precariousness are soaring borrowing costs. Investors have grown increasingly wary of the nation’s fiscal health, reflected in a widening spread between French government bonds (OATs) and their German counterparts (Bunds). The yield on France’s benchmark 10-year government bond, for example, climbed to 3.85% this week, its highest level in over a decade. This investor apprehension stems from a protracted political struggle to rein in France’s elevated budget deficit, projected to be around 5.2% of GDP this year, significantly above the Eurozone’s 3% stability pact limit, and its mounting national debt, which stands at an alarming 112% of GDP. The government’s attempts to implement austerity measures and structural reforms have met with fierce public and parliamentary resistance, creating a deadlock that undermines confidence.
"The situation in France is a complex interplay of economic reality and social sentiment," stated Dr. Alistair Finch, a senior economist at the European Institute for Economic Research. "The government faces an unenviable task: implementing fiscal discipline without further alienating a population already struggling with the cost of living. The political will to push through necessary, albeit unpopular, reforms is being severely tested by the strength of public opposition."
Eurozone’s Mixed Economic Picture
Across the 21-nation Euro area, the economic narrative is one of moderate resilience despite persistent headwinds. The 0.4% growth in the third quarter, while a deceleration from the 0.6% recorded in the second quarter, was nonetheless higher than the 0.2% growth anticipated in a Reuters poll of economists. This suggests a degree of robustness in the face of ongoing geopolitical uncertainties, elevated energy prices, and tighter monetary policy.
However, a closer look reveals a patchwork of performances among member states:
- Germany, the Eurozone’s economic engine, registered a modest 0.2% growth. The industrial powerhouse continues to navigate challenges posed by high energy costs, supply chain disruptions, and a slowdown in global demand for its exports. Sectors like manufacturing and chemicals, traditionally strong, have shown signs of strain, though robust domestic demand in services has provided some counterbalance.
- Italy, the bloc’s third-largest economy, experienced flat growth, indicating stagnation. Structural issues such as high public debt, low productivity growth, and an aging population continue to impede its economic dynamism, making sustained expansion challenging even in periods of broader Eurozone recovery.
- Spain emerged as a relative outperformer, growing by 0.6%. Its economy continues to outpace the Euro area average, bolstered by a strong rebound in its vital tourism industry, robust domestic demand, and a relatively healthy labor market, with unemployment rates steadily declining to around 11.5%. However, Spain is not immune to social pressures; the country was recently rocked by its own mass protests over cost pressures and a severe housing crisis, culminating in a snap election being called for next month. These protests, particularly focused on unaffordable rents and a shortage of social housing, highlight that economic growth alone does not alleviate deep-seated societal grievances.
- Ireland reported an impressive 5.5% growth, though this figure, as often noted, is highly volatile and subject to significant revision. Ireland’s headline GDP figures are heavily influenced by the presence of a large number of multinational corporations that book profits in the country but conduct most of their business elsewhere. Economists often prefer alternative metrics, such as Modified Gross National Income (GNI*), which provides a more accurate reflection of the domestic economy, and which typically shows more moderate, albeit still healthy, growth.
ECB’s Deliberate Stance Amid Inflationary Concerns
The European Central Bank, at its Governing Council meeting on Thursday, October 29, voted to hold its benchmark interest rates steady, maintaining the deposit facility rate at 4.0%. This decision marks a pause after a series of aggressive rate hikes aimed at taming persistent inflation. The ECB’s statement indicated that while the shock from higher energy prices had not yet fully fed into "second-round effects" – a dangerous wage-price spiral where rising prices lead to higher wage demands, which in turn push prices up further – it remained vigilant.
ECB President Christine Lagarde, in her post-meeting press conference, reiterated the bank’s data-dependent approach, emphasizing that while inflation had receded from its peaks, it was still above the 2% target. "We are committed to achieving our price stability mandate," Lagarde stated. "While we see encouraging signs of disinflation, particularly in goods, services inflation remains elevated, and the overall outlook is subject to considerable uncertainty. We must remain attentive to all incoming data, including wage developments and underlying inflationary pressures."
Analysts widely interpreted the ECB’s decision as a tactical pause rather than an end to the tightening cycle. Many anticipate that the central bank may still opt for one more rate hike in December, especially if energy costs remain elevated or core inflation proves more stubborn than expected. "The ECB is walking a tightrope," commented Dr. Lena Schmidt, chief economist at Capital Markets Europe. "They want to avoid over-tightening and pushing the economy into a deeper recession, but they also cannot afford to be seen as complacent about inflation. The downside risks to growth have indeed increased, but the battle against inflation is not yet fully won." The ECB itself acknowledged these increased downside risks to growth, citing geopolitical tensions, particularly the ongoing crisis in the Middle East, and the impact of tighter financing conditions.
Broader Implications and Future Outlook
The Eurozone’s economic landscape, characterized by "unexpected resilience" in some areas but masking significant structural challenges, presents a complex picture for the coming year. Joe Nellis, head of economic research at accountancy MHA, highlighted this duality. "The Euro area is showing unexpected resilience against a backdrop of considerable economic and geopolitical uncertainty, particularly given the energy crisis of the past year," Nellis observed. "However, this aggregate resilience may be masking longstanding structural challenges that continue to plague the bloc."
These challenges include persistently weak productivity growth, inadequate investment expenditure in critical areas like digital transformation and green technologies, demographic pressures from an aging population, and a decline in industrial competitiveness compared to other global powers. The French situation, with its unique blend of economic contraction and intense social unrest, serves as a stark reminder of these underlying fragilities. The political instability evident in both France and Spain underscores how economic grievances can quickly translate into significant political challenges, potentially hindering effective policy responses.
The outlook for 2027 is further complicated by the prospect of renewed inflationary pressures. The ongoing crisis in the Middle East, if unresolved, is highly likely to keep energy and transportation costs elevated. This, in turn, will continue to exert pressure on the cost of living and household finances across Europe, at a time when consumer confidence remains weak. Businesses, too, face increased input costs and uncertainty, which could dampen investment and hiring plans.
"Unless the Middle East crisis is resolved in the very near future, energy and transportation costs will continue to rise, putting even more pressure on the cost of living and household finances at a time when consumer confidence is weak," Nellis cautioned. The interplay between fiscal policy (governments needing to support households and businesses), monetary policy (the ECB’s inflation fight), and geopolitical events will define the Eurozone’s trajectory in the months ahead. The ability of member states, particularly France, to address their domestic economic and social challenges will be crucial not only for their own stability but for the overall health and cohesion of the European Union.