Gilang Muhammad
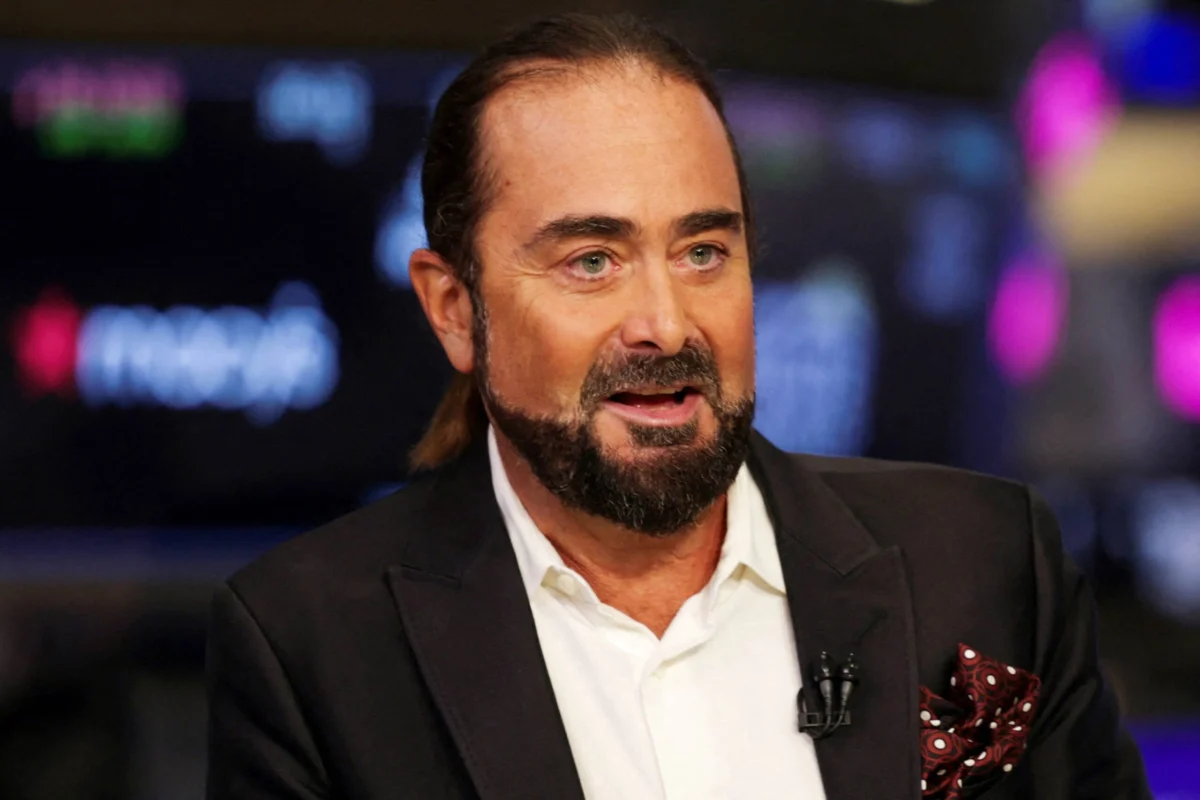
David Zervos, the newly appointed counselor to the U.S. Treasury Secretary, issued a sharp retort to the International Monetary Fund (IMF) on Thursday, suggesting the global financial institution scrutinize its own historical forecasting accuracy before casting judgment on U.S. fiscal policy. His comments, conveyed via email to CNBC, underscore a growing divergence in perspective between Washington and the IMF regarding the sustainability of America’s burgeoning national debt, which recently surpassed the $40 trillion mark. This public exchange highlights a critical debate that resonates through global financial markets and policy circles, scrutinizing the future economic health of the world’s largest economy.
The Heart of the Fiscal Dispute: Growth vs. Debt Trajectory
The contentious dialogue unfolded against the backdrop of the IMF-World Bank annual meetings held in Bangkok, where Managing Director Kristalina Georgieva voiced significant apprehension. On Wednesday, Georgieva cautioned that while robust U.S. economic growth was commendable, it would likely prove insufficient to steer the nation’s escalating federal debt onto a sustainable trajectory. Her remarks were a direct response to an earlier assertion by U.S. Treasury Secretary Scott Bessent, who, in an August interview with CNBC, expressed confidence that the U.S. could "grow our way out" of a rising debt-to-GDP ratio. This fundamental disagreement — whether economic expansion alone can outpace and mitigate the debt burden — lies at the core of the current fiscal policy debate.
David Zervos: A Strategic Voice in the Treasury
David Zervos, previously the Chief Market Strategist for Jefferies LLC, brings a deep understanding of financial markets and economic trends to his pivotal new role as counselor to the Treasury Secretary. His appointment, announced on September 28, 2026, positions him as a key strategist in shaping the Treasury’s messaging and economic outlook. Zervos’s critique of the IMF’s forecasting record is not without precedent. He argued, "When we see pieces on the IMF, it’s good to remember how messy their forecasts have been in the past." This statement echoes a sentiment occasionally found among policymakers who believe the IMF’s sometimes conservative or overly pessimistic outlooks on certain economies have not always materialized, or have even contributed to self-fulfilling prophecies.
Historically, the IMF, while lauded for its analytical rigor, has faced scrutiny over its forecasting precision, particularly during periods of significant economic upheaval such as the 1997 Asian financial crisis or the 2008 global financial crisis. Critics have pointed to instances where the Fund either underestimated the severity of downturns or overestimated the speed of recoveries in various member states, sometimes leading to policy recommendations that were later questioned. Zervos’s pointed reminder aims to temper the impact of the IMF’s current warnings, suggesting that while their concerns warrant attention, their predictive power is not infallible.
IMF’s Global Watchdog Role and Georgieva’s Concerns
Kristalina Georgieva, as the head of the International Monetary Fund, is tasked with overseeing global financial stability and providing surveillance on member countries’ economic policies. The IMF’s perspective is inherently global, considering the potential spillover effects of any major economy’s fiscal decisions. During the Bangkok meetings, Georgieva articulated a view widely held by international economic bodies: that while U.S. growth has been a significant driver of global activity, the persistent accumulation of debt poses long-term risks.

The IMF’s concern stems from several factors. Firstly, a high and rising debt-to-GDP ratio can limit a government’s fiscal space, reducing its ability to respond to future economic shocks, invest in critical infrastructure, or fund essential public services. Secondly, persistent large deficits can put upward pressure on interest rates, potentially crowding out private investment and slowing long-term economic growth. Thirdly, the U.S. dollar’s role as the world’s primary reserve currency means that U.S. fiscal health has disproportionate implications for global financial markets, currency stability, and international capital flows. Georgieva’s warning that growth alone would not suffice implicitly suggests that structural fiscal reforms, potentially involving a combination of spending cuts and revenue enhancements, are necessary to ensure sustainability.
Treasury Secretary Bessent’s "Grow Our Way Out" Thesis
Treasury Secretary Scott Bessent’s assertion that the U.S. can "grow our way out" of its debt challenges is rooted in a historical and theoretical economic argument. The premise suggests that if nominal GDP growth consistently exceeds the growth rate of national debt, the debt-to-GDP ratio can naturally decline over time, even if the absolute debt level continues to rise. This strategy gained prominence in the post-World War II era, when the U.S. significantly reduced its massive wartime debt burden through a combination of robust economic expansion, relatively low interest rates, and modest inflation.
However, the current economic landscape presents a different set of challenges. While the U.S. economy has demonstrated remarkable resilience, achieving sustained, high-level nominal GDP growth that consistently outpaces debt accumulation is a formidable task. Factors such as an aging population, slowing productivity growth (despite hopes for AI-driven boosts), and persistent structural deficits make this path more arduous than in previous eras. Secretary Bessent’s argument likely hinges on projections of strong technological innovation, particularly from artificial intelligence (AI), driving a new era of productivity gains and economic expansion, thereby generating sufficient tax revenues to manage debt obligations without necessitating politically difficult fiscal austerity measures.
The Mounting U.S. National Debt: A Chronology of Accumulation
The U.S. national debt surpassing $40 trillion in August 2026 marked a significant and sobering milestone. To put this into context, the debt reached $10 trillion in 2008, $20 trillion in 2017, and $30 trillion in early 2022. This acceleration in debt accumulation reflects a confluence of factors over the past two decades:
- Financial Crisis Response: Large fiscal stimuli and bailouts following the 2008 financial crisis.
- Tax Cuts: Significant tax reductions enacted in 2017, which, while intended to stimulate growth, also reduced government revenue.
- Pandemic Spending: Unprecedented levels of spending to combat the economic fallout from the COVID-19 pandemic in 2020-2021, including stimulus checks, enhanced unemployment benefits, and business support programs.
- Entitlement Programs: The rising costs of mandatory spending programs like Social Security, Medicare, and Medicaid due to an aging population and increasing healthcare costs.
- Defense Spending: Continued high levels of defense expenditure.
- Rising Interest Rates: As the Federal Reserve responded to inflationary pressures by raising interest rates in the mid-2020s, the cost of servicing the national debt has dramatically increased. Every percentage point increase in interest rates on a $40 trillion debt adds hundreds of billions of dollars to annual interest payments, diverting funds from other critical investments.
The debt-to-GDP ratio, a crucial indicator of a nation’s ability to manage its debt, has consequently risen to historically high levels, projected by some analysts to exceed 120% by the late 2020s, far surpassing levels seen outside of major wartime periods. This metric is what alarms institutions like the IMF, as it suggests that the debt burden is growing faster than the underlying economic capacity to support it.
Global Debt Landscape: A Broader Context
The U.S. fiscal debate does not occur in isolation. Globally, debt levels have reached unprecedented heights. Reports in 2026 indicated that global debt had hit a record $365 trillion. This colossal figure encompasses government, corporate, and household debt across the world. The implications of such widespread indebtedness are profound, raising concerns about:

- Financial Stability: High debt levels can make economies more vulnerable to financial shocks, as witnessed in various emerging markets and even developed economies.
- Monetary Policy Limitations: Central banks in many countries might find their options limited in future crises if interest rates are already low or if high debt makes further quantitative easing ineffective or counterproductive.
- Intergenerational Equity: The current generation’s debt burden is passed on to future generations, potentially limiting their economic opportunities and choices.
- Sovereign Risk: For some nations, particularly those with weaker economic fundamentals, the debt burden could lead to sovereign defaults, triggering wider financial contagion.
The U.S., as the world’s largest economy and holder of the primary reserve currency, shoulders a unique responsibility. Its fiscal health is intricately linked to global economic stability, and its debt trajectory is therefore a matter of international concern, not just domestic policy.
Implications and Future Outlook
The public spat between a key U.S. Treasury official and the head of the IMF carries several significant implications:
- Credibility and Trust: Such disagreements, while common, can occasionally erode public and market confidence in the consistency of economic policy and the objectivity of international assessments.
- Policy Debate Intensification: The exchange will likely intensify the domestic debate within the U.S. about fiscal responsibility. It forces policymakers to confront difficult choices regarding spending priorities, tax reforms, and the long-term sustainability of entitlement programs.
- Market Reactions: Financial markets closely watch these debates. A perception of unsustainable U.S. debt could lead to higher bond yields, as investors demand greater compensation for perceived risk, further exacerbating debt servicing costs. It could also influence the dollar’s value and global capital flows.
- International Cooperation: While unlikely to severely damage fundamental relations, ongoing public disagreements can strain the collaborative spirit necessary for addressing shared global economic challenges.
Independent economic analysts and rating agencies generally lean towards the IMF’s cautionary stance, emphasizing that while growth is vital, it must be accompanied by credible fiscal frameworks to manage debt. They often highlight the political difficulties in implementing spending cuts or tax increases, which are necessary complements to a "grow our way out" strategy. The challenge for the U.S. Treasury will be to articulate a comprehensive strategy that not only projects strong economic growth but also demonstrates a clear path toward fiscal consolidation, or at least stabilization of the debt-to-GDP ratio, in the medium to long term.
The debate between David Zervos and Kristalina Georgieva is more than just a war of words; it reflects a fundamental tension between optimistic national economic projections and the cautious, often conservative, assessments of international financial institutions. As the U.S. navigates its economic future, the resolution of this fiscal dilemma will have profound consequences for its domestic prosperity and its standing in the global economy.