 Gilang Muhammad
The financial world is keenly awaiting Friday’s release of the Bureau of Labor Statistics’ (BLS) nonfarm payrolls count for September, a pivotal report poised to offer significant insights into the current health and trajectory of the U.S. labor market. Following a period of fluctuating economic signals and evolving monetary policy discussions, this data is expected to either confirm a stabilizing job picture or highlight emerging vulnerabilities as the year progresses. Wall Street consensus, as tracked by Dow Jones, anticipates a gain of 84,000 jobs, alongside an unemployment rate holding steady at 4.1%.
This projected job growth marks a notable downshift from the robust expansion seen in the pre-2025 period, yet the unemployment rate, which Federal Reserve officials monitor with particular intensity, remains near a level broadly indicative of full employment. The September figures arrive on the heels of a surprisingly strong August report, which recorded a gain of 162,000 jobs and included encouraging upward revisions to prior months’ data. This consistent, albeit sometimes volatile, job creation has become a central element in the Federal Reserve’s ongoing assessment of economic conditions, particularly as the central bank navigates its dual mandate of achieving maximum employment and price stability.
The Federal Reserve’s Deliberate Stance
A key aspect of the September jobs report’s significance lies in its implications for future monetary policy. Fed officials are expected to scrutinize the numbers to affirm the underlying strength of the labor market, even as they increasingly pivot their primary attention towards the more persistent challenge of inflation. Recent commentary from within the Fed suggests a growing confidence in the labor market’s resilience, tempering the urgency for further aggressive rate hikes.
Federal Reserve Vice Chairman Philip Jefferson, speaking on Thursday, articulated this nuanced perspective. "In the labor market, a broad range of data indicates that conditions have stabilized," Jefferson remarked, underscoring the Fed’s analytical framework. He further elaborated, "While job creation has been somewhat volatile, payroll gains have broadened to many sectors in recent months, which is encouraging. Layoffs have remained low, and job openings have moved a bit higher on net." This assessment suggests a labor market that, while perhaps not booming with the fervor of previous recovery phases, is nonetheless robust and exhibiting positive underlying trends.
This measured optimism from Fed leadership has already begun to reshape market expectations for future interest rate adjustments. New York Fed President John Williams, earlier in the week, conveyed a message of caution regarding immediate policy shifts, stating that "there is no need for urgency" when policymakers consider whether to implement another rate hike following September’s quarter-percentage-point increase. Williams reiterated the strength of the employment picture, noting, "On the employment side of [the Fed’s twin goals of full employment and stable prices], the data show that the labor market continues to be solid — and has even strengthened a bit on the margin."
These carefully worded statements from influential Fed figures have had a tangible impact on financial markets. Subsequent to Williams’ remarks, traders significantly reduced the perceived probability of an interest rate hike at the upcoming October 27-28 Federal Open Market Committee (FOMC) meeting, pushing expectations for the next monetary policy adjustment further out, with a move in December now seen as considerably more likely. This shift highlights the market’s sensitivity to central bank communication and the pivotal role of labor market data in guiding those communications.
Chronology of Key Economic Events Leading to the September Report:

The lead-up to Friday’s September nonfarm payrolls release has been marked by several significant economic developments and policy decisions that frame its importance:
- August 2026 Jobs Report (September 4, 2026): The BLS reported a stronger-than-expected gain of 162,000 nonfarm payrolls, accompanied by upward revisions to July and earlier months. This report initially fueled expectations of continued labor market tightness.
- Federal Reserve Rate Decision (September 16, 2026): The FOMC voted to raise the federal funds rate by a quarter-percentage point, continuing its campaign to tame inflation. However, the accompanying statement and press conference began to hint at a more data-dependent approach moving forward.
- Federal Reserve Officials’ Speeches (Week of September 22-26, 2026): A series of speeches by regional Fed presidents and board members, including John Williams and Philip Jefferson, progressively signaled a less urgent stance on further immediate rate hikes, emphasizing the stability of the labor market and a heightened focus on inflation metrics.
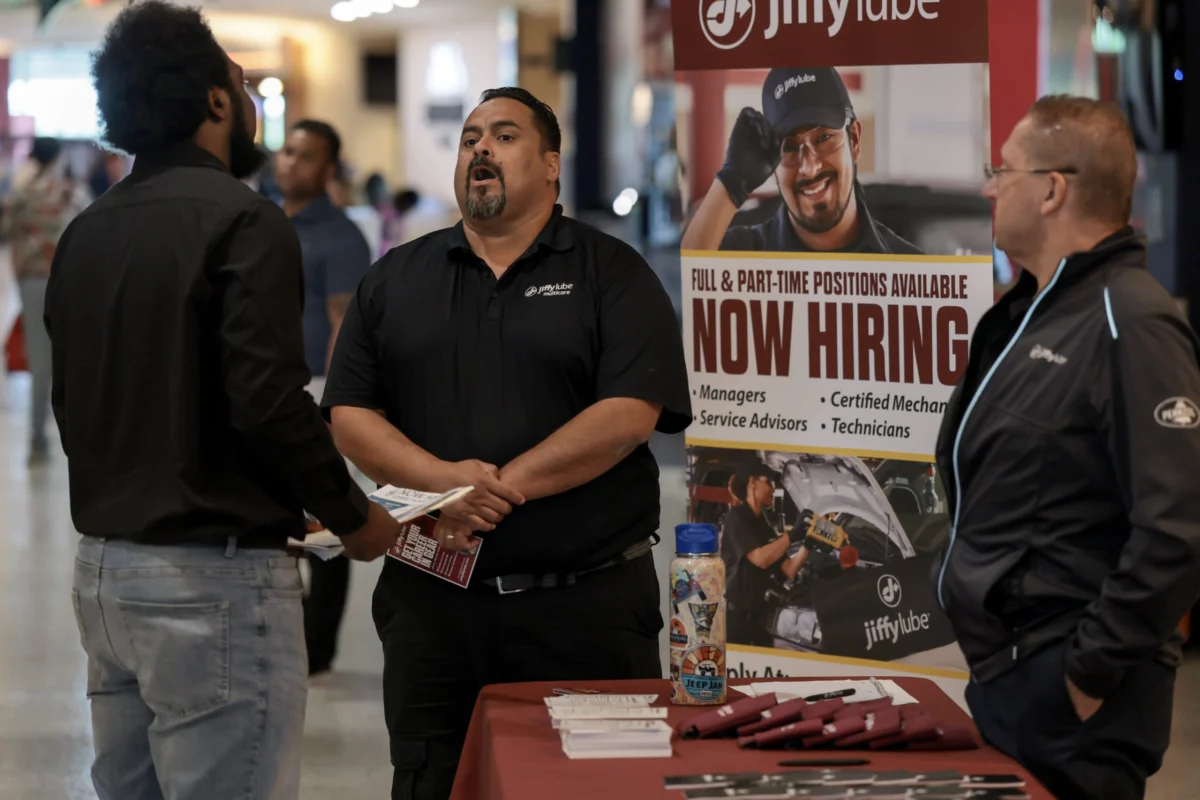
- Mega JobNewsUSA South Florida Job Fair (September 25, 2026): An event at the Amerant Bank Arena in Sunrise, Florida, where companies like Jiffy Lube, represented by Victor Moreno, actively engaged with job seekers. This real-world snapshot underscores ongoing hiring efforts and opportunities, even amidst broader economic discussions.
- Glassdoor Employee Confidence Index (September 2026 Release): The survey indicated a record low in employee confidence for September, reflecting anxieties over job security, economic uncertainty, inflation, and the impact of artificial intelligence.
- Challenger, Gray & Christmas Layoff Report (September 2026 Data Released Thursday, October 1, 2026): This report indicated a significant decrease in planned layoffs for September, falling 18% from August and 20% from the same period a year ago, providing a counterpoint to some of the confidence concerns.
- Initial Unemployment Claims (Latest Data Released Thursday, October 1, 2026): Weekly claims edged down to 197,000, further reinforcing the narrative of low layoff activity.
This sequence of events underscores a period of careful observation and recalibration for policymakers, businesses, and workers alike, with the September jobs report serving as a crucial update.
Dissecting the Labor Market’s "Slow But Steady" Pace
The overarching narrative emerging from recent economic analyses is that of a labor market that is stable, if not spectacularly growing. This "slow but steady" picture is central to the argument that while the Fed must remain vigilant against inflation, it does not necessarily need to rush into another rate hike.
Nonfarm Payrolls: While the projected 84,000 job gain for September represents a moderation, it aligns with the average monthly payroll growth of approximately 80,000 seen throughout 2026. This average, however, masks considerable volatility. For instance, the economy experienced a loss of 156,000 jobs in February, only to rebound sharply with a gain of 214,000 in March, illustrating a pattern of hits and misses that has characterized the year. Such fluctuations necessitate a broader view of trends rather than overemphasizing any single month’s data.
Unemployment Rate: The expectation for the unemployment rate to hold at 4.1% is particularly noteworthy. This figure is historically low and firmly within the range that many economists and Fed officials consider to be consistent with full employment. A low unemployment rate typically signals a tight labor market where most individuals seeking work can find it, a condition that the Fed strives to maintain.
Wage Growth: A significant development supporting the Fed’s cautious approach is the moderation in wage growth. Average hourly earnings are anticipated to show a 3.1% year-over-year increase in September, a noticeable decrease from the approximately 4% rate observed at the beginning of the year. This deceleration is crucial because Fed officials have repeatedly emphasized that wages are not currently viewed as a significant source of inflationary pressure. The absence of clear evidence for a "wage-price spiral" – where rising wages fuel higher prices, which in turn demand higher wages – is an important distinction that grants the central bank more flexibility in calibrating its policy response. This moderation suggests that businesses are not facing overwhelming pressure to raise wages to attract and retain talent, which could otherwise translate into higher consumer prices.
Job Openings and Layoffs: Further reinforcing the "stable" assessment is the data on job openings and layoffs. While job openings, as measured by the Job Openings and Labor Turnover Survey (JOLTS), have shown some fluctuation, they have generally remained elevated, signaling persistent demand for labor. Critically, layoff activity has remained remarkably low. The latest data indicates that first-time claims for unemployment insurance edged down to 197,000 last week, a level consistent with a healthy labor market. Moreover, the outplacement firm Challenger, Gray & Christmas reported on Thursday that planned layoffs in September were down 18% from August and a significant 20% from the same period a year ago. This consistent lack of widespread job cuts provides a strong counter-argument to fears of an imminent downturn.
Underlying Concerns and Market Resilience

Despite the generally stable macroeconomic indicators, underlying anxieties persist within the workforce. The most recent Glassdoor survey highlighted a concerning trend: employee confidence fell to a record low in September, marking the third such occurrence this year. Daniel Zhao, Glassdoor’s chief economist, attributed these concerns to "anxiety around job security, economic uncertainty and inflation mount." A new element contributing to worker apprehension is the growing fear of artificial intelligence (AI) and its potential impact on future job prospects, signaling a longer-term structural concern that may not be immediately visible in traditional labor market metrics.
However, these pockets of anxiety are juxtaposed against a backdrop of undeniable resilience. The consistently low layoff numbers, as evidenced by initial jobless claims and corporate layoff reports, paint a picture of employers largely holding onto their existing workforces. This suggests that while hiring may have slowed from its post-pandemic frenzy, companies are not yet resorting to widespread job cuts. As Dan North, senior economist at Allianz Trade, aptly summarized, "Job openings are going down, hiring’s kind of creeping down, and you find out that anecdotally, anyway, and also in the data, that it’s very hard for people to get a new job. You have that unemployment rate which doesn’t move much, and it’s really important to see that historically it’s pretty low. So, I think you’re seeing a job market that is — ‘stable’ is a really good word for it." This stability, characterized by low layoffs and a still-tight labor market, helps to explain the Fed’s current comfort with its policy stance.
The image from the Mega JobNewsUSA South Florida Job Fair on September 25, 2026, featuring Victor Moreno from Jiffy Lube engaging with job seekers, provides a tangible illustration of this dynamic. Despite broader economic uncertainties and worker anxieties, hiring activity continues across various sectors, indicating that opportunities are still available for those actively seeking employment. This on-the-ground reality offers a crucial counterpoint to purely statistical analyses.
Broader Economic Implications and The Road Ahead
The September jobs report, therefore, will be more than just a number; it will be a crucial data point influencing a complex interplay of economic forces. A report that aligns with or slightly exceeds expectations (84,000 jobs, 4.1% unemployment) would likely reinforce the Fed’s current wait-and-see approach, allowing policymakers more time to assess the impact of past rate hikes on inflation without feeling pressured to tighten further. This could contribute to market stability, potentially preventing significant volatility in bond yields and equity markets.
Conversely, a surprisingly strong report could reignite concerns about persistent inflation and compel the Fed to reconsider its "no urgency" stance, potentially leading to a repricing of rate hike expectations. On the other hand, a significantly weaker-than-expected report could signal a more rapid deceleration in economic activity, raising concerns about a potential recession and potentially leading the Fed to pause or even consider future easing measures, though this scenario appears less likely given recent data.
For businesses, a stable labor market, even with slower growth, offers predictability. Companies can plan staffing levels without the immediate threat of widespread labor shortages or the need for aggressive wage increases. For consumers, a low unemployment rate provides job security, which is foundational for sustained spending, even if concerns about inflation continue to weigh on confidence.
Looking ahead, the Fed will continue to monitor a broad array of economic indicators beyond just nonfarm payrolls, including the Consumer Price Index (CPI), Personal Consumption Expenditures (PCE) price index, and Gross Domestic Product (GDP) reports. The December FOMC meeting is now shaping up to be a critical juncture, where policymakers will likely make their next significant decision regarding the trajectory of interest rates, heavily informed by the cumulative data from the fall months. The September jobs report is merely the latest, but undoubtedly one of the most important, pieces of that evolving economic puzzle.