 Gilang Muhammad
The U.S. economy demonstrated a surprising soft spot in its labor market during September, creating significantly fewer jobs than anticipated and prompting a recalibration of expectations regarding the Federal Reserve’s future monetary policy decisions. This unexpected slowdown has introduced a new layer of complexity to the ongoing economic narrative, challenging previous assumptions of sustained labor market resilience amidst a backdrop of persistent inflation.
A Detailed Look at September’s Disappointing Figures
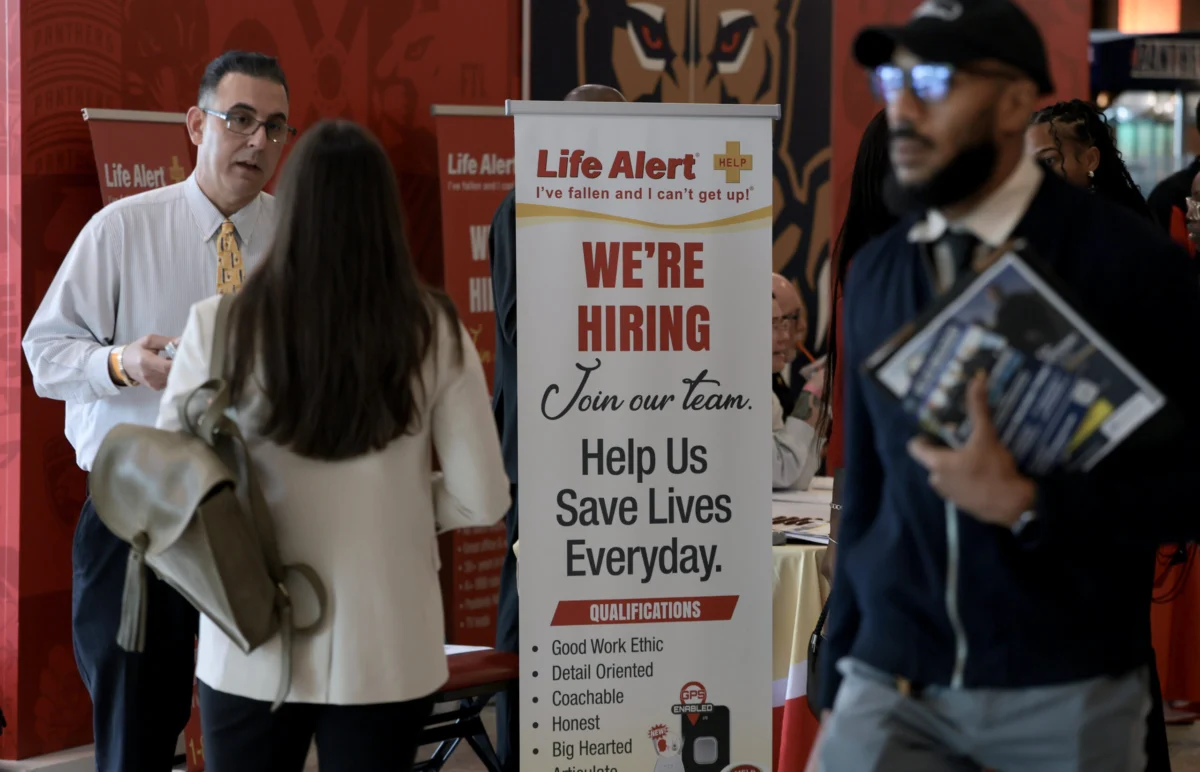
According to the Bureau of Labor Statistics (BLS) report released on Friday, nonfarm payrolls rose by a seasonally adjusted 29,000 for the month. This figure dramatically missed economists’ projections, as a Dow Jones survey had forecast job growth of 84,000. Compounding this weak performance, the national unemployment rate experienced an uptick, increasing to 4.2% from the previous month’s 4.1%, defying expectations for it to hold steady or even slightly decrease.
The disappointment wasn’t confined to September alone. The BLS also announced substantial downward revisions to previous months’ job counts, signaling a broader, more protracted deceleration in hiring momentum. The August jobs count was revised lower to reflect a gain of 133,000, a notable reduction from the initially reported figures. Even more strikingly, July’s payroll data was revised from a modest gain to a net loss of 10,000 jobs. In total, these revisions indicated that 60,000 fewer jobs were created in the preceding months than previously understood, painting a picture of an economy cooling more rapidly than policymakers or market analysts had perceived. This downward trend in revisions often serves as an early warning sign of underlying weakness, as initial estimates tend to be more optimistic and are later adjusted as more comprehensive data becomes available.
Immediate Market Reaction: A Dovish Interpretation
Financial markets reacted swiftly and decisively to the release of the jobs report, interpreting the soft numbers as a strong signal that the Federal Reserve would likely pause its aggressive rate-hiking campaign. Traders widely viewed the data as "good news" for asset prices, predicated on the belief that a weaker labor market would diminish inflationary pressures and, consequently, the central bank’s impetus to tighten monetary policy further.
Following the report’s release, stock futures surged across major indices, indicating a positive opening for the trading day. Concurrently, Treasury yields experienced a significant slump. Yields on benchmark 10-year Treasury notes, which had recently climbed to levels not witnessed since the early 2000s, retreated sharply, reflecting increased demand for safer assets and a revised outlook on future interest rates. The market-implied odds for the Fed to hold rates steady at its upcoming October 27-28 meeting jumped dramatically to 82.8%, according to the CME Group’s FedWatch tool. This represented a stark shift from prior expectations, which had leaned towards another rate hike or at least a strong possibility of one.
Thomas Simons, chief U.S. economist at Jefferies, encapsulated the prevailing sentiment among many analysts, stating in a client note, "For the Fed, this number should be the nail in the coffin for an October hike." Simons further elaborated on the unexpected nature of the slowdown, remarking, "The payroll data surged in August, and we had expected the momentum to continue this month, given the historically low prints on jobless claims in recent weeks. However, it now appears that the August number was nothing more than a rebound from very weak hiring in June and July." This assessment underscored the fragility of recent job gains and the potential for a more sustained deceleration.
The Federal Reserve’s Dual Mandate: A Shifting Balance
The Federal Reserve operates under a dual mandate: to achieve maximum employment and maintain price stability (typically defined as 2% annual inflation). For much of the past two years, the focus has been heavily tilted towards combating stubbornly high inflation through a series of aggressive interest rate hikes. This approach was largely justified by a historically tight labor market, characterized by low unemployment, abundant job openings, and robust wage growth, which policymakers viewed as contributing to inflationary pressures.
The September jobs report, however, significantly alters this delicate balance. While Fed officials often pay closer attention to the unemployment rate derived from the household survey than the headline payroll numbers from the establishment survey, the overall picture presented a challenge to the narrative of an overheating labor market.
A Deeper Dive into Labor Market Metrics
While the establishment survey, which generates the widely cited nonfarm payrolls figure, showed considerable weakness, the household survey presented a slightly more nuanced, albeit still concerning, picture. The household survey, which forms the basis for the unemployment rate calculation, indicated that household employment rose by 406,000 for the month. The labor force itself expanded by 485,000, and the labor force participation rate, which measures the proportion of the working-age population either employed or actively seeking employment, increased by 0.2 percentage points to 61.8%. This marked its highest level since May, suggesting that more individuals were re-entering or seeking to re-enter the workforce, potentially alleviating some of the tightness in the labor supply.
Furthermore, an alternative measure of unemployment, known as the U-6 rate, which includes discouraged workers and those holding part-time jobs for economic reasons (i.e., who would prefer full-time employment but cannot find it), edged down to 7.6%. This was its lowest level in nearly two years, indicating some underlying strength in broader labor utilization despite the headline weakness. The U-6 rate is often considered a more comprehensive measure of labor market health as it captures underemployment that the official U-3 unemployment rate might miss.
However, the silver lining from the household survey was overshadowed by the crucial factor of wage growth, which continued to show signs of disinflation. Average hourly earnings increased by a mere 0.1% in September, falling short of Wall Street’s expectation of 0.3%. This modest monthly gain brought the 12-month increase in average hourly earnings to 3%, the lowest annual rate since May 2021. Economists had anticipated a 3.1% year-over-year increase. The average work week remained unchanged at 34.6 hours, indicating no significant increase in labor demand from existing workers.
The Inflation Conundrum and Wage Pressures

For the Federal Reserve, the slowing wage growth is a critical development. Wage inflation has been a significant component of the overall inflation picture, and a moderation here could be interpreted as a sign that broader price pressures are beginning to ease. Policymakers have largely viewed inflation as a more pressing threat to the economy than the labor market, which had shown remarkable resilience in recent months. Despite the weak September job growth, other indicators had painted a picture of a "low-hire, low-fire" economy, with weekly jobless claims consistently remaining low and one indicator showing layoffs at their lowest rate in four years.
Yet, inflation has persistently held well above the Fed’s 2% target. The most recent indicator of the central bank’s preferred gauge, the core Personal Consumption Expenditures (PCE) price index, showed an annual rate of 3%, still considerably elevated. This juxtaposition—slowing job growth and decelerating wages against persistent, albeit moderating, inflation—presents a genuine policy dilemma for the Fed. Heather Long, chief economist at Navy Federal Credit Union, highlighted the impact on consumers: "Americans are frustrated by the lack of opportunities right now. Wage growth fell to a new 5-year low and is being wiped out entirely by inflation. That stings heading into the holidays."
Despite the immediate concerns, Long also described the labor market as "stable" and expressed her belief that the Fed would not be entirely dissuaded from hiking rates in December. This perspective underscores the ongoing debate among economists regarding the true underlying health of the labor market and its implications for future monetary policy. Some argue that a gradual cooling is necessary to bring inflation under control without triggering a severe recession, while others fear that the recent data signals a more abrupt and potentially damaging downturn.
Sectoral Performance: A Mixed Bag
A closer examination of job gains and losses across various sectors reveals a mixed and somewhat uneven performance in September. The healthcare sector emerged as a primary driver of job creation, adding 17,000 workers. This consistent growth in healthcare reflects ongoing demographic trends, including an aging population and increased demand for medical services, making it a resilient sector even amidst broader economic shifts.
Construction also demonstrated strength, adding 11,000 jobs, possibly boosted by continued infrastructure spending or residential building projects in certain regions. Manufacturing, a sector often seen as a bellwether for the broader industrial economy, contributed 9,000 new positions, indicating some pockets of resilience despite global supply chain complexities and fluctuating demand.
However, several key sectors experienced notable declines, highlighting areas of weakness. Government employment saw a reduction of 17,000 jobs, which could be attributed to a range of factors from budget constraints at state and local levels to a winding down of temporary federal projects. Temporary help services, often considered an early indicator of hiring trends as businesses adjust staffing levels, saw a decline of 11,000, suggesting that companies may be hesitant to commit to permanent hires.
The information services sector experienced a loss of 10,000 jobs, a development that raises concerns, particularly in the context of ongoing discussions about the potential impact of artificial intelligence (AI) on the future of work. While direct causation is hard to prove, anxieties surrounding AI’s disruptive capabilities and efficiency gains could be leading to cautious hiring or even layoffs in certain tech-related roles. Financial activities also recorded a drop of 7,000 jobs, potentially reflecting the broader slowdown in economic activity, rising interest rates impacting lending and investment, or consolidation within the industry.
Broader Economic Context: Conflicting Signals
The weak September job growth stands in contrast to other signs of strength in the broader macro economy. Earlier in the week of the jobs report release, the Commerce Department revised its estimates for both first- and second-quarter gross domestic product (GDP) growth upwards, to 2.5% and 2.2% respectively. This indicated a more robust economic expansion in the first half of the year than initially understood. Furthermore, the Atlanta Fed’s GDPNow tracker, a closely watched real-time forecast, was tracking third-quarter GDP growth at an impressive 3.7%.
These conflicting signals—a cooling labor market alongside strong GDP growth—present a complex picture for economic forecasters and policymakers. One interpretation is that the economy is achieving a "soft landing," where inflation is tamed without triggering a deep recession, and the labor market is cooling sustainably from an unsustainably hot pace. Another view suggests that the jobs report might be a lagging indicator, or perhaps an early warning, that the cumulative effect of the Fed’s aggressive rate hikes is finally starting to bite, and stronger GDP figures might be unsustainable if job creation continues to falter. Consumer spending, a major component of GDP, is heavily reliant on a healthy labor market and steady wage growth.
Implications for Future Monetary Policy and the Economy
The September jobs report will undoubtedly be a central point of discussion at upcoming Federal Open Market Committee (FOMC) meetings. Following recent statements from central bank policymakers, markets had already begun to recalibrate expectations, largely anticipating that the FOMC would hold off on another rate hike until December, after having raised benchmark rates by a quarter percentage point in September. This latest jobs data further solidifies that expectation for an October pause.
However, the question remains whether this slowdown is a temporary blip or the beginning of a more entrenched trend. If the labor market continues to weaken in subsequent months, the Fed might face increasing pressure to not only pause but potentially even consider the timing of future rate cuts, especially if inflation shows clearer signs of decelerating towards the target. Conversely, if inflation remains stubbornly high despite a cooling labor market, the Fed’s dilemma will intensify, forcing it to weigh the risks of job losses against the imperative of price stability.
For businesses, a slowing labor market could translate into reduced hiring costs and potentially ease labor shortages that have plagued many industries. However, it could also signal weakening consumer demand, impacting sales and revenue. For American households, the report offers a mixed message: while decelerating wage growth might be a concern, particularly when inflation remains elevated, a more balanced labor market could also lead to greater job security for some, as businesses might become less prone to rapid hiring and firing cycles if they anticipate a more stable economic environment.
In conclusion, the September jobs report serves as a pivotal moment in the current economic cycle. It challenges previous assumptions about the labor market’s resilience, strengthens the case for a Federal Reserve pause, and injects a renewed sense of uncertainty into the economic outlook. The coming months will be crucial in determining whether this slowdown represents a healthy rebalancing or a precursor to a more significant downturn.