Gilang Muhammad
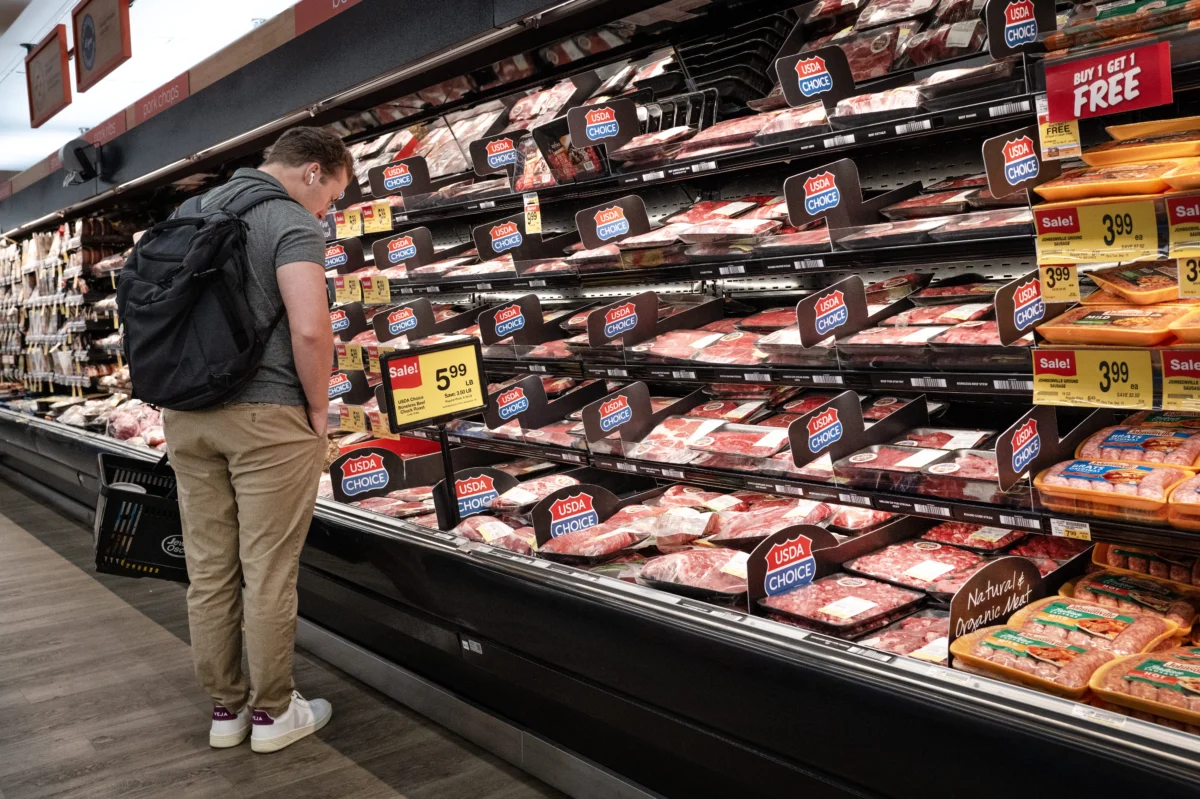
Consumer sentiment plummeted in September, registering its second-lowest level on record in the University of Michigan’s closely watched monthly survey, a stark reflection of deepening anxiety among households grappling with persistent inflationary pressures. The headline index, a critical barometer of household economic outlook, fell to a concerning 47.8, marking a significant 7.5% decline from its August reading and a more pronounced 13.2% drop compared to the same period a year ago. This figure stands as the second-lowest recorded since the survey’s inception in 1952, eclipsed only by the nadir reached in May of the previous year, when surging prices similarly jolted the national economic outlook.
Plunging Confidence Amidst Inflationary Headwinds
The pronounced deterioration in consumer confidence is directly attributed to a resurgence in inflation fears, particularly stemming from a sharp uptick in fuel prices and lingering concerns over global trade tensions. Joanne Hsu, the survey director, articulated the gravity of the situation, stating, "Year-ahead expectations for both personal finances and business conditions plunged. With a resurgence in fuel prices and trade tensions, consumers anticipate greater pressures on their pocketbooks to come." This sentiment is underscored by a significant surge in the one-year inflation outlook, which climbed to 4.6%. This marks a substantial 0.6 percentage point increase from the prior month’s projection and matches the highest level recorded since June of the previous year, signaling a widespread belief that price increases will remain elevated in the near term. The internal components of the University of Michigan’s survey further illustrate the depth of this pessimism: the current conditions index, which assesses consumers’ perceptions of their present financial situation, saw a 1.9% decline from the previous month. More alarmingly, the expectations measure, which gauges consumers’ outlook for the economy and their personal finances over the next year, tumbled by a substantial 11.1%. This steep fall in future expectations is particularly concerning for economists, as it often foreshadows a potential slowdown in consumer spending, a primary engine of economic growth.
The Anatomy of Consumer Pessimism: UMich Survey Deconstructed
The University of Michigan’s Surveys of Consumers, conducted monthly since 1946, are designed to track consumer attitudes and expectations regarding business conditions, personal finances, and buying conditions. These surveys are considered leading indicators because changes in consumer sentiment often precede shifts in consumer spending behavior, which accounts for approximately two-thirds of U.S. economic activity. The methodology involves telephone interviews with a nationally representative sample of approximately 500 households, querying them on a range of topics including their financial situation, employment prospects, and intentions to make major purchases. The recent data points to a pervasive sense of unease. The sub-index for buying conditions for large household durables, vehicles, and homes all registered significant declines, reflecting both higher interest rates and elevated prices making big-ticket purchases less affordable or desirable for many households. The May reading, which now stands as the absolute record low, occurred during a period when the annual inflation rate was near its peak, soaring past 9%. While the current 3.4% annual inflation rate (as per the latest CPI data) is lower, the recent acceleration in specific categories, especially energy, has reignited fears and dashed hopes for a more rapid deceleration of prices. The sustained erosion of purchasing power, coupled with uncertainty about future economic stability, is clearly taking a toll on household morale.
Inflation’s Persistent Grip: A Deep Dive into BLS Data
Further validating consumers’ inflation fears, data released concurrently by the Bureau of Labor Statistics (BLS) provided concrete evidence of mounting price pressures. The Consumer Price Index (CPI) report for August revealed that overall inflation stood at 3.4% on an annual basis, a figure significantly above the Federal Reserve’s long-term target of 2%. A key driver of this acceleration was the energy sector. Gasoline prices, a highly visible and frequently purchased commodity, rose by 3.9% in August alone and were up a staggering 27.4% from a year ago. Fuel oil prices saw an even more dramatic increase, soaring 10.1% month-over-month and an alarming 52% annually. These increases directly impact household budgets, as higher transportation costs eat into disposable income, leaving less for other goods and services. Beyond energy, other categories continue to contribute to inflationary pressures. Food prices, while not experiencing the same volatility as energy, have seen sustained increases over the past year, placing an additional burden on families. Housing costs, encompassing rent and owners’ equivalent rent, have also remained elevated, reflecting strong demand and tight supply in many markets. The persistence of these broad-based price increases, despite the Federal Reserve’s aggressive monetary tightening, underscores the complexity of the current economic environment. While supply chain disruptions have eased somewhat from their pandemic-era peaks, geopolitical events, such as ongoing conflicts and their impact on global energy markets, continue to exert upward pressure on commodity prices. Furthermore, a relatively robust labor market, characterized by low unemployment and rising wages, contributes to demand-side inflation, as consumers have more money to spend, albeit with less purchasing power. The core CPI, which strips out volatile food and energy components to provide a clearer picture of underlying inflation trends, also remains a concern for policymakers, suggesting that inflation is not solely concentrated in a few sectors but has become more entrenched across the economy.
The Federal Reserve’s Unwavering Resolve: A Path to Price Stability
The confluence of plunging consumer sentiment and stubbornly high inflation data has solidified expectations for aggressive action from the Federal Reserve. Following the release of both the University of Michigan’s sentiment survey and the BLS’s CPI report, traders in financial markets now see a Federal Reserve rate hike next week as a near certainty, with odds rising past 85% on Friday. This anticipated move would mark another step in the central bank’s ongoing battle against inflation, which has proven more persistent than initially anticipated. The Federal Reserve operates under a dual mandate from Congress: to achieve maximum employment and maintain price stability. With inflation consistently running far above its 2% target, the focus has squarely shifted to price stability. Over the past year and a half, the Fed has embarked on one of the most aggressive monetary tightening cycles in decades, raising the federal funds rate from near-zero levels to its current target range. Each hike increases the cost of borrowing for consumers and businesses, aiming to cool demand across the economy and thereby reduce inflationary pressures. Higher rates impact everything from mortgage rates and auto loans to credit card interest, designed to slow down spending and investment. Fed officials, including Chairman Jerome Powell, have repeatedly emphasized their unwavering commitment to bringing inflation back down to target, even if it entails some economic slowdown or "pain" for households and businesses. The current economic data, particularly the re-acceleration of inflation expectations and the broad-based nature of price increases, provides a compelling argument for continued hawkish policy. The challenge for the Fed lies in engineering a "soft landing" – reducing inflation without triggering a severe recession. The recent consumer sentiment data, however, suggests that public confidence in such an outcome is waning, potentially complicating the Fed’s task.
A Chronology of Economic Shifts and Policy Responses
The current economic landscape is the culmination of several years of unprecedented events and policy responses. Following the initial shock of the COVID-19 pandemic in early 2020, governments worldwide implemented massive fiscal stimulus measures, and central banks adopted ultra-loose monetary policies, including near-zero interest rates and quantitative easing. These measures, while effective in preventing a deeper economic collapse, also injected significant liquidity into the system. As economies reopened in late 2020 and throughout 2021, a surge in consumer demand, coupled with persistent supply chain disruptions (exacerbated by labor shortages and geopolitical tensions), began to push prices upward. Initially, the Federal Reserve characterized this inflation as "transitory," expecting it to abate as supply chains normalized. However, by late 2021 and early 2022, it became clear that inflationary pressures were more entrenched. This prompted a significant pivot by the Fed, which began its aggressive rate-hiking cycle in March 2022. Consumer sentiment, initially buoyed by stimulus and a recovering job market, began to sour as inflation took hold. The University of Michigan’s index saw a steady decline through 2022, reaching its then-record low in May 2022. Throughout 2023, there were periods of cautious optimism as inflation showed signs of moderating and the labor market remained robust. However, the recent resurgence in fuel prices, driven by factors such as OPEC+ production cuts and renewed geopolitical uncertainties, has reignited inflationary fears and reversed some of the progress made in consumer confidence. This chronological progression highlights the dynamic and often unpredictable nature of economic forces and the continuous balancing act faced by policymakers.
Broader Economic Ripple Effects: From Households to Global Markets
The plunge in consumer sentiment and the Federal Reserve’s anticipated rate hike carry significant implications that extend far beyond individual household budgets. For the broader economy, a sustained decline in consumer confidence often translates into reduced consumer spending, particularly on discretionary items. This could impact sectors like retail, hospitality, and entertainment, potentially leading to slower economic growth, reduced corporate earnings, and even job losses if businesses respond to weakened demand. Economists are increasingly discussing the heightened risk of a recession, as the cumulative effect of higher interest rates and persistent inflation could eventually tip the economy into a downturn. The housing market, already sensitive to interest rate fluctuations, is expected to face further headwinds. Higher mortgage rates, driven by Fed policy, will continue to reduce affordability and likely dampen housing demand and sales activity. This could lead to a cooling of home price appreciation or even declines in some overvalued markets. For businesses, higher borrowing costs mean less investment in expansion and innovation. Companies also face the dual challenge of rising input costs due to inflation and potentially weaker consumer demand, which can squeeze profit margins. The labor market, while currently strong with low unemployment rates, could also see a slowdown. As economic activity cools, hiring may decelerate, and wage growth, which has been robust, might moderate, further impacting consumer purchasing power. Globally, the Federal Reserve’s aggressive stance has ripple effects. A stronger U.S. dollar, often a consequence of higher interest rates, can make U.S. exports more expensive and make imports cheaper. It also puts pressure on countries with dollar-denominated debt, increasing their repayment burdens and potentially triggering capital outflows from emerging markets. The interconnectedness of global financial systems means that U.S. monetary policy decisions resonate far beyond its borders, influencing currency markets, commodity prices, and investment flows worldwide.
Expert Perspectives and the Road Ahead
Economists and financial analysts widely view the latest consumer sentiment data as a clear signal of ongoing consumer distress and a formidable challenge for economic policymakers. Many underscore the difficult position of the Federal Reserve, which must continue to fight inflation while simultaneously trying to avoid a severe economic contraction. "The consumer is the backbone of the American economy, and when their confidence wavers this significantly due to inflation, it sends a strong warning signal," commented Dr. Sarah Jenkins, chief economist at Global Financial Strategies. "The Fed’s path forward remains fraught with challenges, balancing the imperative of price stability with the risk of triggering a deeper downturn." Consumer advocacy groups have expressed growing concern over the strain on household budgets, particularly for lower-income families disproportionately affected by rising food and energy costs. "Every increase in gas and grocery prices is a direct hit to families already struggling to make ends meet," stated Maria Rodriguez, director of the National Consumer Alliance. "Policymakers must consider the real-world impact of these economic pressures on everyday Americans." Looking ahead, the trajectory of inflation, particularly energy prices, will be a critical determinant of future consumer sentiment and economic policy. While the Federal Reserve remains committed to its inflation target, the market and consumers alike will be closely watching for any signs that price pressures are truly abating or if further aggressive action will be required. The interplay between monetary policy, geopolitical developments, and domestic economic conditions will continue to shape the outlook for consumers and the broader economy in the coming months. The journey back to sustained price stability and robust consumer confidence appears to be a long and arduous one.