Gilang Muhammad
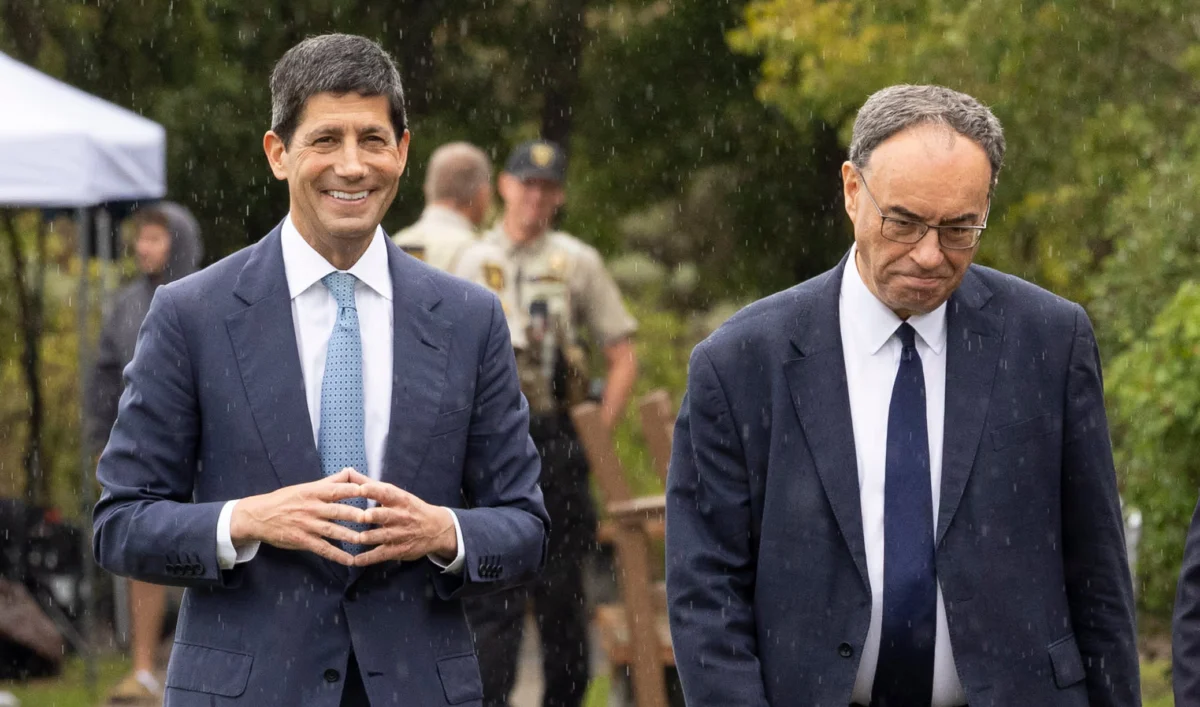
The Bank of England’s Monetary Policy Committee (MPC) on Thursday opted to maintain its benchmark Bank Rate at 3.75%, defying growing inflationary pressures and diverging from a wave of interest rate hikes initiated by other major global central banks. The decision, though widely anticipated by financial markets, was met with a strong dissenting vote within the committee, highlighting the intensifying debate over the optimal strategy to combat persistent inflation fueled by geopolitical tensions and supply-side shocks. While holding steady for now, the central bank issued a stark warning that a rate hike was becoming "increasingly likely" in the near future, setting the stage for a potentially pivotal meeting in November.
The MPC’s vote saw a split of 6-3, with the majority advocating for stability amidst a complex economic landscape. The three dissenters, however, pushed for an immediate 25-basis-point increase, arguing for pre-emptive action to curb inflation that has now risen significantly above the Bank’s 2% target. This internal division underscores the delicate balancing act faced by policymakers: managing the risks of runaway inflation against the potential for stifling an already fragile economic recovery.
A Divergence in Global Monetary Policy
The Bank of England’s decision stands in contrast to recent aggressive tightening moves by its international counterparts. Just the day before, the U.S. Federal Reserve announced a quarter-point hike, marking its first increase since 2023, signaling a renewed commitment to taming inflation across the Atlantic. Last week, the European Central Bank (ECB) delivered its second rate hike of the year, following an initial increase in June that ended a three-year period of stable rates. Adding to this global trend, the Bank of Japan (BoJ) is widely expected to raise its key interest rate at the conclusion of its two-day meeting on Friday, which would represent a significant shift for a central bank long committed to ultra-loose monetary policy.
This divergence places the Bank of England in a unique position. While other central banks move to decisively cool their economies, the BoE appears to be biding its time, assessing the true extent and persistence of inflationary drivers before committing to further tightening. Markets had largely priced in this cautious approach, with LSEG data indicating a 76% probability of a rate hold on Thursday. However, the same data, alongside analyst consensus, now points to a near certainty of a hike of at least 25 basis points at the MPC’s next meeting in November, suggesting that the current pause may be merely a temporary reprieve.
The Shadow of Inflation: UK’s August Figures
The backdrop to the MPC’s decision was the latest inflation data, which painted a concerning picture for the UK economy. Figures released on Wednesday by the Office for National Statistics (ONS) revealed that the country’s inflation rate surged to 3.1% in August, marking its first breach above the 3% threshold since March. This increase pushed inflation further away from the Bank of England’s mandated 2% target, intensifying the pressure on policymakers.
The primary driver of this inflationary spike was a sharp rise in motor fuel costs, which soared by an alarming 23% year-on-year. As a net energy importer, the United Kingdom remains particularly susceptible to external energy shocks, a vulnerability exacerbated by global geopolitical events. The country continues to grapple with the lingering effects of a persistent cost-of-living crisis, a phenomenon rooted in post-COVID inflationary pressures and the profound impact of the Russia-Ukraine war on global natural gas supplies. This confluence of factors has kept household budgets under severe strain and posed significant challenges for businesses.
Governor Andrew Bailey, in a statement accompanying the decision, acknowledged these pressures but indicated that their broader impact on the UK economy had been contained so far. "So far, higher global energy costs have had a limited effect on price and wage setting in the U.K.," Bailey stated. However, he quickly added a crucial caveat: "But the longer this volatility persists, the bigger the impact it will have on inflation, and the more likely it is we will need to raise Bank Rate to ensure that inflation falls back to our 2% target." This statement signals a clear intent to act if inflationary pressures prove more enduring than currently assessed, reinforcing market expectations for a November hike.
The Dissenting Voices: Pre-emptive Action Advocated
The three MPC members who voted for an immediate rate increase—Catherine L. Mann, Megan Greene, and Huw Pill—articulated strong arguments for pre-emptive action, emphasizing the heightened risks to price stability stemming from a volatile global environment. Their collective concerns highlighted the need to anchor inflation expectations and prevent second-round effects from becoming entrenched in the economy.
Catherine L. Mann, a former global chief economist at Citibank, reiterated her consistent stance, having also voted for a hike in July. She argued that "the ‘sporadic continuance’ of conflict has ratcheted up energy prices well above the baseline from the July Report." Mann expressed particular concern over the Bank of England’s short-term inflation forecast, which projected the Consumer Price Index (CPI) rising above 4% in early 2027. For Mann, raising the Bank Rate immediately represented a superior risk-management strategy when confronted with such uncertainty about inflation dynamics and potential second-round effects. "Doing so avoids a worse outcome whereby inflation becomes embedded, which requires even tighter policy later," she asserted, advocating for decisive action now to avert more painful measures in the future.
Megan Greene echoed these sentiments, pointing to a broader range of uncertainties contributing to inflationary pressures. Beyond the geopolitical fallout of the Iran war, Greene cited "AI-related supply constraints" and the "El Niño climate event" as significant sources of potential price instability. Her analysis underscores the multi-faceted nature of current global inflationary forces, extending beyond traditional energy shocks to encompass technological shifts and climate phenomena.
Huw Pill, the third dissenter, emphasized the signaling power of an immediate rate hike. He contended that raising rates would have sent a "clear signal of the MPC’s commitment to achieving its price stability mandate amidst the fog of geopolitical conflict and data noise." Pill stressed the importance of bolstering the clarity and effectiveness of policy choices, arguing that "acting decisively now cuts through in a way that bolsters the clarity and effectiveness of policy choices, thereby heading off inflationary pressures rather having to reverse them once they become ingrained." This perspective highlights the psychological aspect of monetary policy, where credible communication and decisive action can help shape public and business expectations, thereby influencing future inflationary trends.
The UK’s Unique Economic Vulnerabilities
The UK’s current economic predicament is particularly challenging, marked by a confluence of domestic and international factors. Beyond being a net energy importer, the nation has been grappling with the legacy of Brexit, which has introduced new trade frictions and labor market dynamics. The persistent cost-of-living crisis, fueled by high energy prices and rising food costs, has significantly eroded household purchasing power, impacting consumer confidence and spending.
Moreover, global inflation concerns, coupled with ongoing political instability and apprehension regarding UK fiscal policy, have placed considerable pressure on British government bonds, known as gilts, throughout the year. The UK currently faces the highest borrowing costs in the G7, with yields on its long-dated 20- and 30-year gilts persistently approaching the 6% mark. This elevated cost of government borrowing has significant implications for public finances, potentially constraining the government’s ability to fund public services and investment, and raising concerns about the sustainability of national debt.
Market Response and Expert Analysis
Following the Bank of England’s decision, the gilt market reacted immediately. Benchmark 10-year UK government bond yields saw a decline of 4 basis points, settling at 5.2473%. Similarly, 30-year gilt yields shed approximately 7 basis points, trading at 5.7932%. While a modest dip, this reaction reflects the market’s initial interpretation of the hold as a signal of less immediate tightening pressure, even if a hike is expected soon.
Investment strategists offered their perspectives on the BoE’s strategy. Scott Gardner, an investment strategist at J.P. Morgan Personal Investing, characterized the Bank’s approach as "biding its time." Gardner noted that "Despite headline inflation creeping up over the summer, the labour market continues to soften while closely-watched core and services inflation have both been relatively resilient since the Middle East conflict started." He further cautioned, "So far, the UK economy has largely been insulated from the conflict, aside from higher energy bills. However, the longer the war continues, the harder it is to see that resilience holding." This analysis suggests that while the UK has shown some initial resilience to global shocks, its ability to maintain this could diminish over time, making future rate hikes inevitable.
Neil Birrell, chief investment officer at Premier Miton, offered a slightly different take, suggesting that "The Bank seems to be more relaxed on inflation risks than their international counterparts, although the markets are setting borrowing costs at present anyway." Birrell highlighted the proactive role of the market in influencing borrowing costs, irrespective of the central bank’s immediate actions. He concluded with a forward-looking assessment of the gilt market: "With the expectation being for a number of hikes through the end of this year in to middle of next, the gilt market may be more susceptible to a move the other way," implying that any deviation from anticipated tightening could trigger significant market volatility.
Looking Ahead: The Path to Price Stability
The Bank of England’s decision to hold rates marks a moment of pause in a rapidly evolving global economic landscape. While the central bank emphasizes its commitment to bringing inflation back to its 2% target, the path forward remains fraught with uncertainty. The "fog of geopolitical conflict," as MPC member Huw Pill described it, continues to cast a long shadow over energy markets and supply chains, making inflation forecasting exceptionally challenging. The interplay between these external shocks and domestic economic conditions will dictate the pace and magnitude of future monetary policy adjustments.
The anticipated November meeting will be critical, as the MPC re-evaluates the persistence of inflationary pressures, the resilience of the UK labor market, and the impact of global events. For UK households and businesses, the prospect of higher interest rates looms large, potentially translating into increased borrowing costs for mortgages and loans, and a further dampening of economic activity. The Bank of England is walking a tightrope, balancing the imperative of price stability with the need to avoid tipping the economy into a deeper downturn. Its future actions will not only shape the UK’s economic trajectory but also send a powerful signal about its resolve in confronting a complex and volatile inflationary environment.