Farhan Pambudi
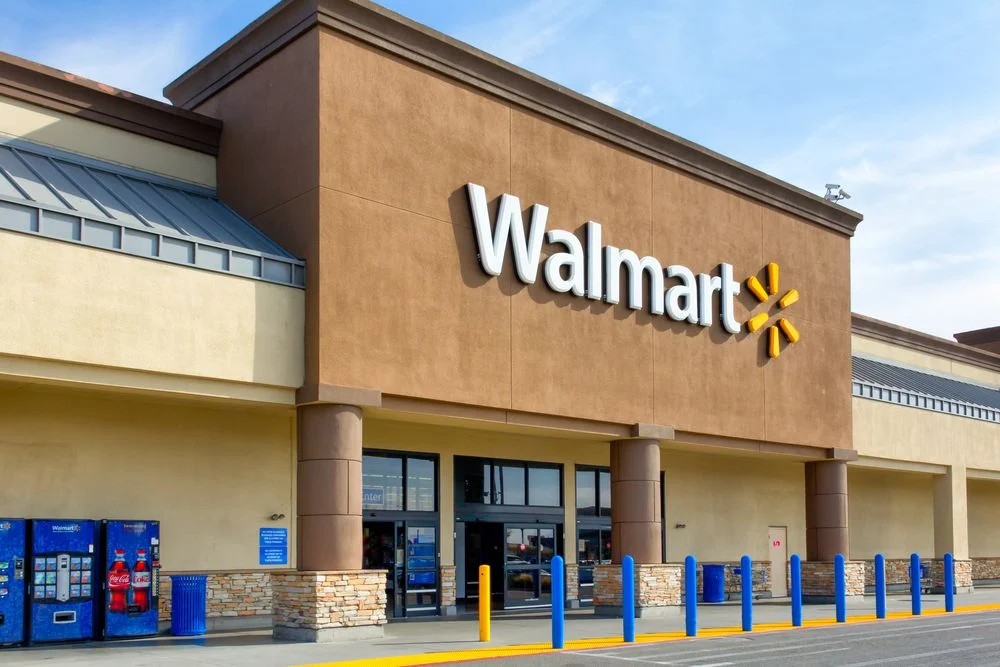
Walmart Inc., the world’s largest retailer by revenue, announced on Friday, August 21, 2024, that it will officially begin accepting Apple Pay and Google Pay at its retail locations across the United States. This move signals the end of a nearly decade-long standoff in which the Arkansas-based retail giant resisted the industry-standard Near Field Communication (NFC) technology in favor of its proprietary payment solutions. The transition will encompass both Walmart stores and Sam’s Club locations, marking a significant shift in the company’s digital strategy and a victory for consumer convenience advocates who have long petitioned the retailer to modernize its point-of-sale systems.
According to the official announcement, the rollout is scheduled to begin on August 24, 2024, at select Walmart and Sam’s Club locations. The company expects the "Tap to Pay" functionality to be operational at all store and club locations by the conclusion of the 2024 calendar year. Furthermore, Walmart confirmed that the technology will be extended to its extensive network of fuel stations, with a projected completion date for the fueling infrastructure by the middle of 2027. This phased approach allows the company to update its hardware and software systems while ensuring staff are trained on the new payment workflows.
A Historical Context of Resistance: The CurrentC Era and Walmart Pay
To understand the gravity of this announcement, one must look back at the early 2010s when mobile payments were in their infancy. In 2012, Walmart led a consortium of major retailers—including Target, Best Buy, and 7-Eleven—to form the Merchant Customer Exchange (MCX). The goal of MCX was to develop a mobile payment system called CurrentC, which was designed specifically to bypass the traditional credit card networks and their associated interchange fees.
Unlike Apple Pay, which utilizes NFC technology to transmit encrypted tokens, CurrentC relied on QR codes and was linked directly to a customer’s bank account. This structure was intended to save retailers billions in processing fees and allow them to retain direct access to customer purchasing data—data that Apple Pay purposefully masks to protect user privacy. However, CurrentC was widely criticized for being cumbersome and less secure than its hardware-based counterparts. Following a series of security breaches and a lack of consumer interest, MCX postponed the nationwide rollout of CurrentC in 2016, and the project was eventually shuttered.
While other members of the MCX consortium, such as Best Buy and Target, eventually relented and adopted Apple Pay (in 2015 and 2019, respectively), Walmart remained the sole major holdout. Instead, it doubled down on "Walmart Pay," a QR-code-based system integrated into the Walmart mobile app. By forcing customers to use Walmart Pay, the company could track individual shopping habits more effectively and integrate its "Scan & Go" technology and loyalty programs directly into the transaction process.
The Technological Divide: NFC vs. QR Codes
The primary friction point between Walmart and its customer base has been the technological medium of the transaction. Apple Pay and Google Pay utilize NFC, a short-range wireless technology that allows a smartphone or smartwatch to communicate with a payment terminal simply by being held near it. This "Tap to Pay" method is generally considered the gold standard for speed and security in the modern retail environment.
In contrast, Walmart’s reliance on QR codes required customers to unlock their phones, open the Walmart app, navigate to the payment section, and scan a code displayed on the register screen. While Walmart argued that this method was more inclusive because it worked on smartphones without NFC chips, the broader market moved in the opposite direction. As of 2024, industry data indicates that approximately 85% of U.S. retailers accept Apple Pay, and contactless payments have become the preferred method for the majority of Gen Z and Millennial consumers.
The COVID-19 pandemic acted as a massive catalyst for this trend. During 2020 and 2021, the demand for "touchless" transactions surged. While Walmart Pay provided a touchless option, it still required more steps than the seamless NFC tap, leading to increased "checkout friction"—a term used by retail analysts to describe anything that slows down the final step of a purchase.
Supporting Data and Market Trends
The decision to adopt Apple Pay and Google Pay is backed by compelling market data regarding consumer behavior. According to recent reports from Juniper Research, the total value of contactless payment transactions is expected to reach $10 trillion globally by 2027, up from $4.6 trillion in 2022. In the United States specifically, the adoption of digital wallets has reached a critical mass.
A 2023 study by Capital One Shopping found that over 50% of American consumers use a digital wallet for at least some of their in-store purchases. Furthermore, Apple Pay holds the largest share of the U.S. mobile payment market, with an estimated 45 to 50 million active users. By excluding these users from using their preferred payment method, Walmart was effectively creating a barrier to entry for a significant portion of the shopping public.
Industry analysts suggest that Walmart’s pivot is also a defensive move against its primary competitors. Target, Costco, Walgreens, and CVS have all supported NFC payments for years. Even smaller, regional grocery chains have upgraded their terminals to support tap-to-pay. As Walmart continues to expand its "Walmart+" subscription service to compete with Amazon Prime, providing a modern, frictionless checkout experience is essential for retaining high-value, tech-savvy customers.
Official Statements and Strategic Framing
In its official press release, Walmart framed the decision as a commitment to customer "choice" rather than a reversal of previous policy. The company emphasized that it is not abandoning Walmart Pay, but rather expanding the ecosystem of options available to its members and shoppers.
"Tap to Pay is a great addition to the other payment options already offered like cash, credit card or Walmart Pay," the company stated. "And giving customers and members more choice at checkout is part of a broader effort to make managing and using their money easier."
Market observers note that the timing of the announcement—just ahead of the busy holiday shopping season—is likely intended to capture increased spending from younger demographics who may have previously avoided Walmart due to the lack of mobile wallet support. By integrating Apple Pay and Google Pay now, Walmart ensures that its systems will be fully vetted and operational for the 2024 Black Friday and Christmas rush.
Analysis of Implications: Data, Fees, and the Future
While the adoption of Apple Pay is a win for consumers, it presents a strategic challenge for Walmart regarding data collection. One of the primary reasons Walmart resisted NFC payments for so long was the "data wall" created by Apple. When a customer uses Apple Pay, the merchant receives a unique tokenized number rather than the actual credit card number, and Apple does not share the customer’s identity or specific demographic information with the retailer.
For a company like Walmart, which has invested heavily in its "Walmart Connect" advertising business, losing visibility into the specific identity of a transacting customer is a significant trade-off. Walmart Connect relies on "closed-loop" data—the ability to show an ad to a customer and then prove that the same customer bought the product in-store. To mitigate the loss of data from Apple Pay transactions, Walmart is expected to lean more heavily on its loyalty programs and the Walmart+ membership, encouraging users to scan their "Member ID" even if they pay with an external digital wallet.
Furthermore, the adoption of these platforms means Walmart will continue to pay the standard interchange fees set by Visa, Mastercard, and American Express. The dream of the 2012 MCX consortium—to create a merchant-owned payment rail that eliminated these fees—is now effectively dead.
Chronology of the Walmart Payment Evolution
- 2011: Google Wallet (the precursor to Google Pay) launches, introducing NFC payments to the U.S. market.
- 2012: Walmart, Target, and others form the Merchant Customer Exchange (MCX) to develop CurrentC.
- 2014: Apple Pay launches; Walmart and several other retailers actively block the service at their terminals.
- 2015: Walmart officially launches "Walmart Pay" using QR code technology.
- 2016: The CurrentC project is indefinitely delayed and eventually shuttered; most MCX partners begin adopting NFC.
- 2019: Target, one of the last major holdouts alongside Walmart, begins accepting Apple Pay.
- 2020-2022: The COVID-19 pandemic accelerates the shift toward contactless payments; Walmart remains the only "Big Box" holdout.
- August 2024: Walmart announces the nationwide rollout of Apple Pay and Google Pay support.
- Late 2024: Projected completion of the rollout across all Walmart and Sam’s Club stores.
- Mid-2027: Projected completion of the rollout at Walmart-affiliated fuel stations.
Conclusion: A New Era for Big-Box Retail
The capitulation of Walmart to the standards of Apple and Google marks a turning point in the retail industry. It demonstrates that even the most powerful retailers cannot dictate consumer behavior when it comes to the convenience and security of financial transactions. As the lines between physical and digital shopping continue to blur, the "Tap to Pay" standard has emerged as the clear winner in the battle for the checkout counter.
For the millions of Walmart and Sam’s Club customers, the change means one less point of friction in their daily routines. For the retail industry at large, it serves as a case study in the limitations of proprietary ecosystems. While Walmart Pay will likely continue to exist as a tool for the company’s most loyal shoppers, the opening of its gates to Apple and Google ensures that Walmart remains a competitive destination in an increasingly digital-first economy.