Ena Muazin
September’s commodity markets have once again demonstrated the profound and interconnected influence of geopolitical events and climatic anomalies. The ongoing conflict in Iran and the pervasive effects of the El Niño weather phenomenon have emerged as the dominant drivers of price fluctuations across a spectrum of energy and agricultural commodities. This persistent trend, observed throughout the month, has led to notable price increases, underscoring the fragility of global supply chains in the face of these powerful external forces. The widely tracked Goldman Sachs Commodity Index (GSCI), a key benchmark for commodity performance, registered a significant gain of approximately 4.5 percent, reflecting the broad upward pressure on raw material prices. Amidst these market movements, a surprising resurgence has been noted for a fossil fuel previously considered by many to be in decline, signaling a complex interplay of energy transitions and immediate geopolitical realities.
Orange Juice: A Surprising September Surge
In a remarkable turnaround, orange juice, which had been the poorest performing commodity in August, emerged as the top gainer in September. Futures contracts traded in New York saw their value surge by over 27 percent during the month. This dramatic price escalation highlights the inherent volatility within agricultural commodity markets, particularly for less liquid assets where significant trades can disproportionately impact prices.
The inherent characteristics of agricultural markets contribute to these pronounced price swings. The production cycle for crops like oranges involves a significant time lag between planting and harvest. This means that the supply side of the equation is relatively inelastic in the short to medium term, unable to rapidly adjust to sudden shifts in demand or unforeseen production disruptions. This phenomenon is often analogized to the "pig cycle" in livestock markets, where periods of high prices incentivize increased production, leading to eventual gluts and price drops, followed by reduced production and subsequent price rallies.
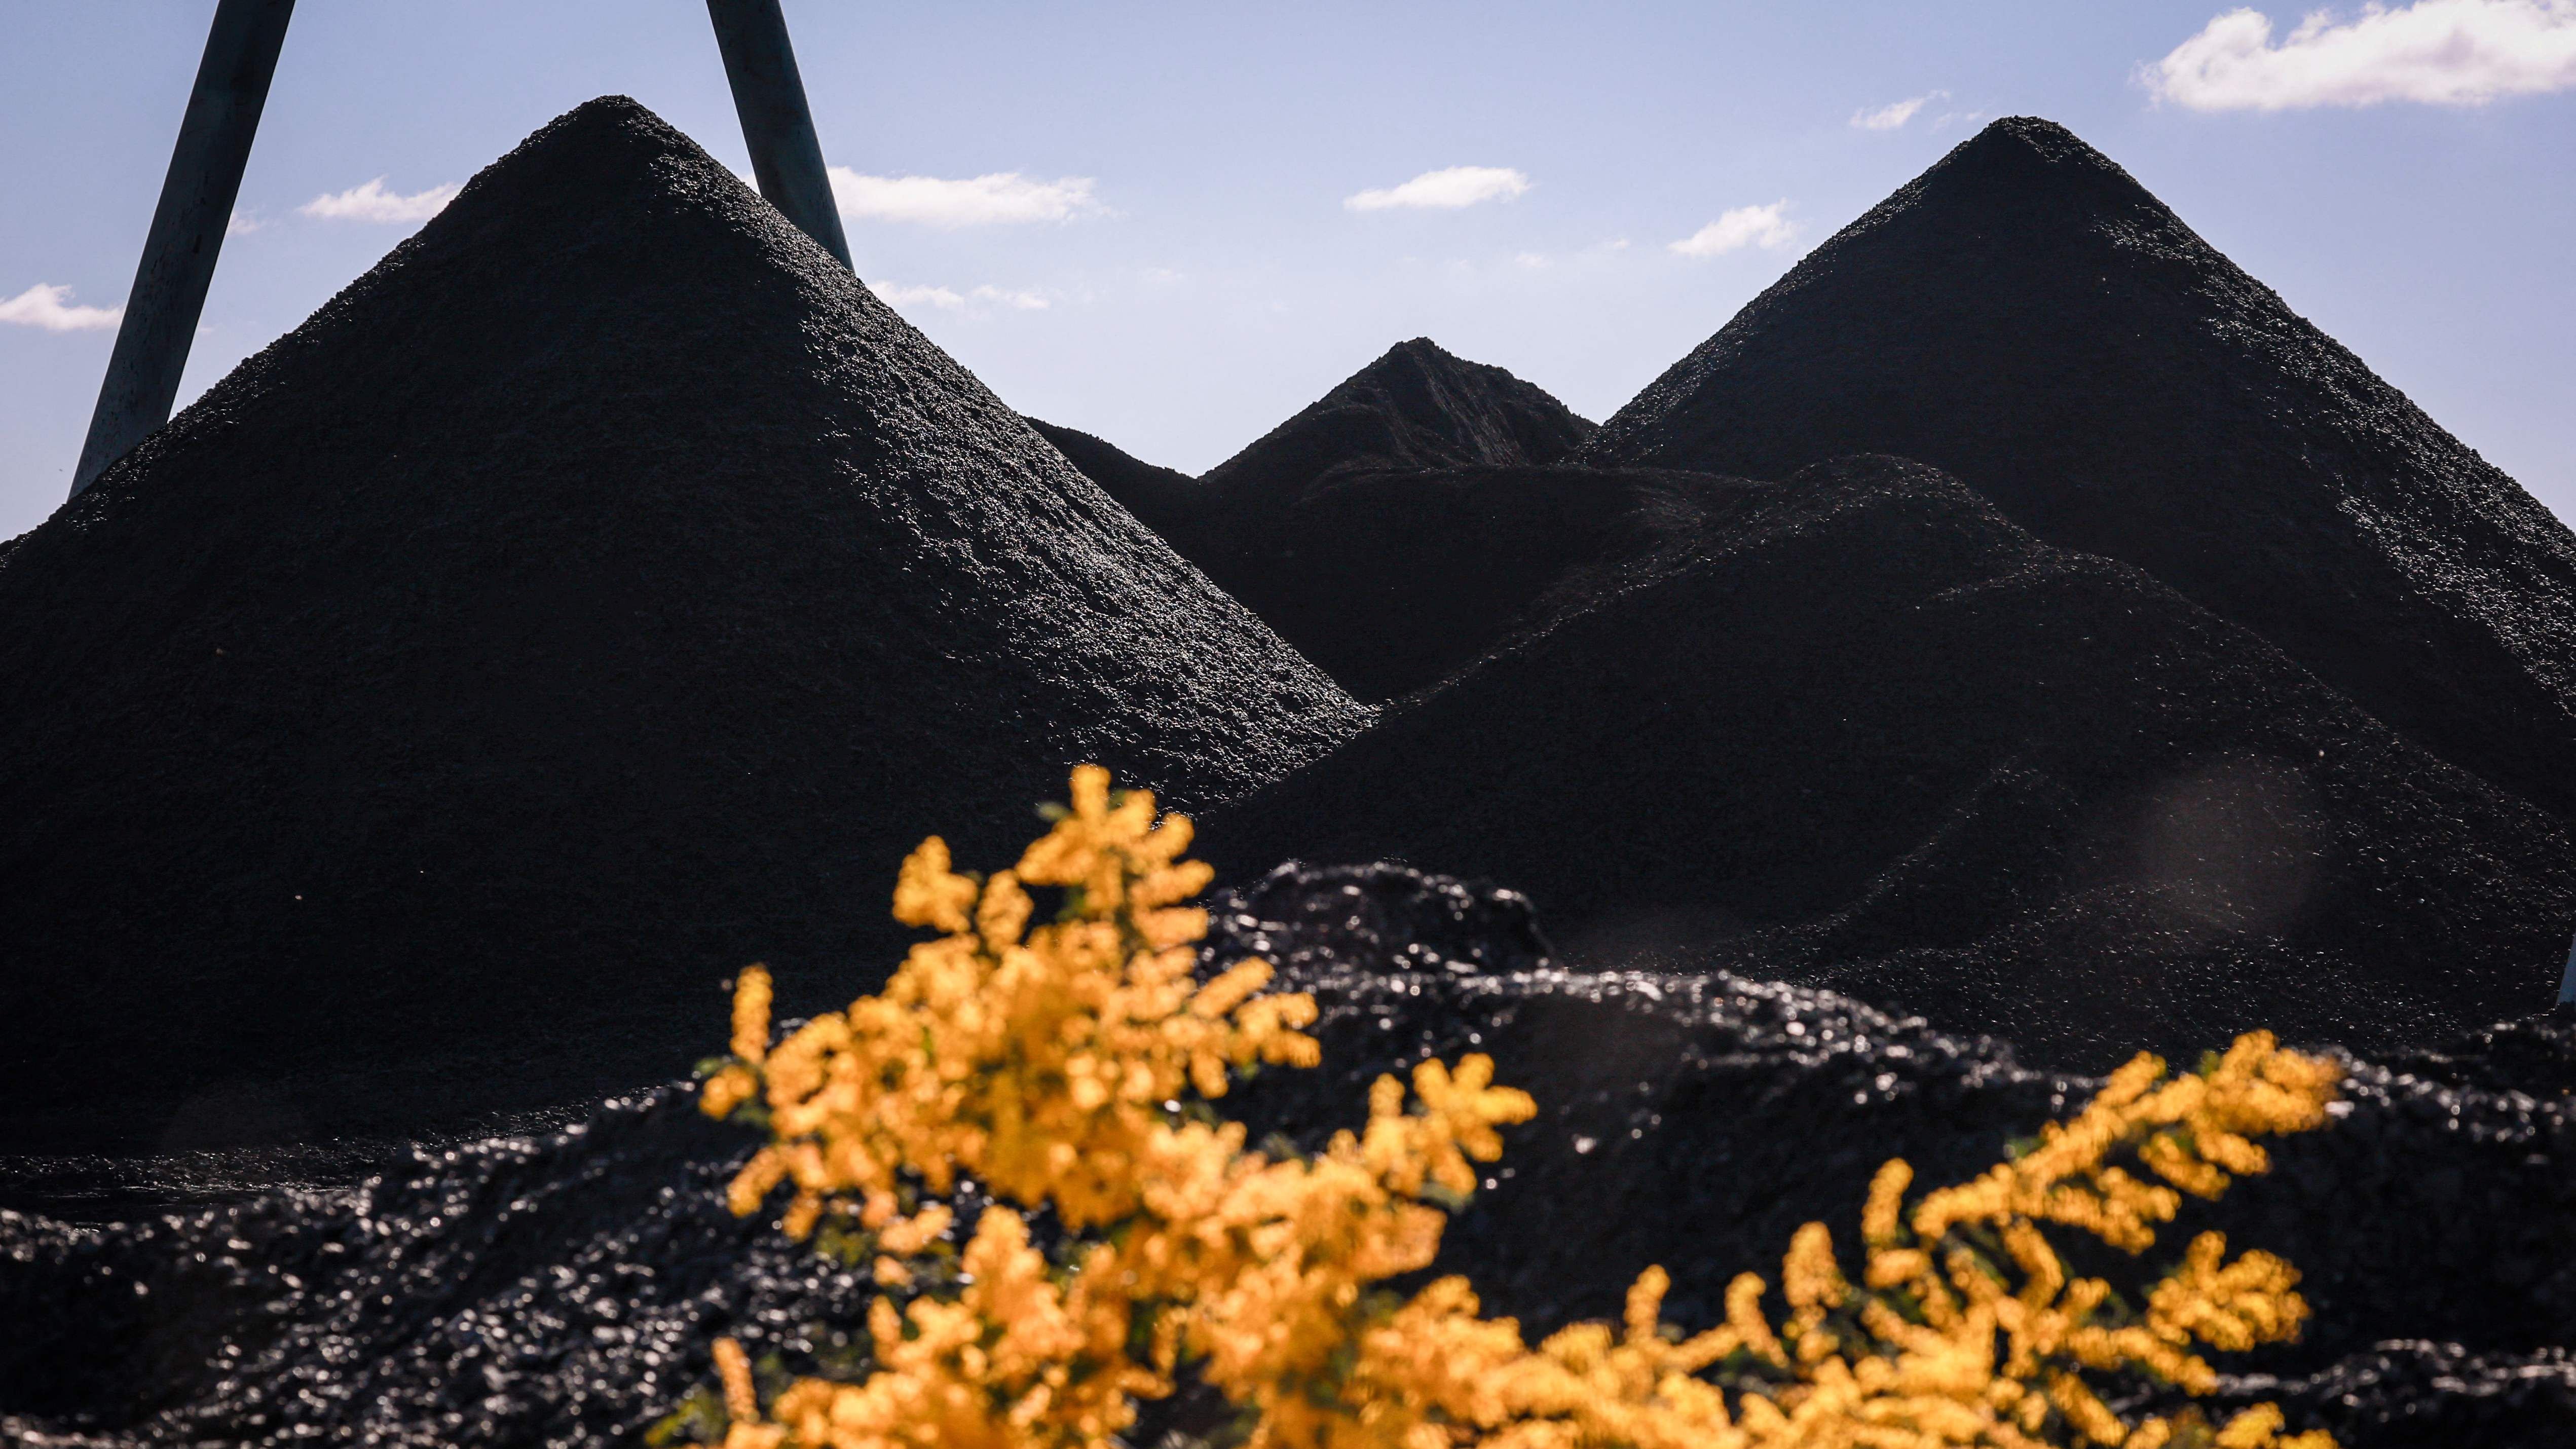
Beyond market structure, fundamental factors are also at play for orange juice. Analysts at Rabobank have projected that global orange juice production for the current season could be as much as 13 percent lower than the previous year. Furthermore, there is a palpable risk that the final output could fall even below these conservative estimates, particularly if the latter half of the year experiences unseasonably hot weather. This forecast is directly linked to the anticipated severity of the El Niño event.
El Niño’s Intensifying Grip on Global Weather Patterns
Meteorologists are increasingly concerned about the potential for an exceptionally strong El Niño this year. El Niño is characterized by a significant warming of the sea surface temperature in the eastern Pacific Ocean. This recurring climate pattern, typically occurring every two to seven years and lasting for approximately nine to twelve months, is known to trigger a cascade of extreme weather events across the globe. The specific impacts vary by region, but generally include altered precipitation patterns, increased frequency of heatwaves, and prolonged droughts in some areas, while others may experience intensified rainfall and flooding. The overall effect is a global rise in temperatures.
The implications of a potent El Niño for agricultural output are substantial. Rabobank analysts have issued a stark warning regarding the potential for a reduced supply in the upcoming harvest year. Their research indicates that "prolonged dry periods at the end of winter, combined with above-average temperatures over extended periods, could impact a portion of the bloom for the 2027/28 harvest season." This suggests that the repercussions of the current El Niño could extend well beyond the immediate harvest, affecting future production cycles and contributing to sustained price pressures on certain agricultural commodities.
The impact of El Niño extends beyond agriculture, influencing energy demand. The extreme heatwaves associated with the phenomenon have led to increased reliance on air conditioning in many regions, driving up electricity consumption. This surge in demand for power, particularly in economies heavily reliant on fossil fuels for electricity generation, has indirectly boosted demand for coal.
Coal’s Resurgence: A "War Winner" Amidst Energy Realignment
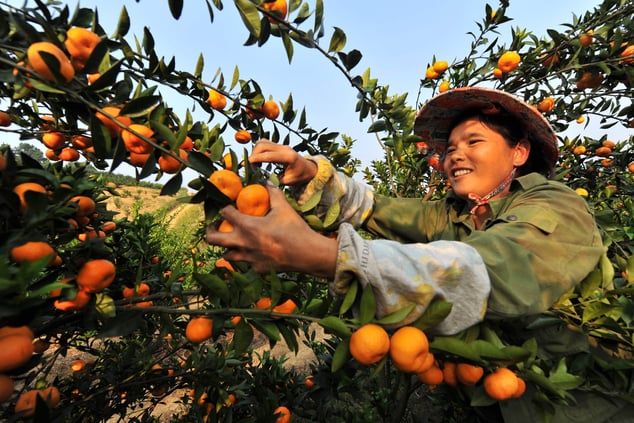
Coal has secured the third position in September’s commodity performance rankings, with prices rising by over six percent. This "war winner," as it has been termed, signifies a notable comeback for a fossil fuel that many had anticipated would see a steady decline. The current geopolitical landscape, specifically the ongoing conflict in Iran, has significantly impacted natural gas prices, making coal a more attractive and cost-effective alternative for power generation in several key economies.
The International Energy Agency (IEA) has reported that higher natural gas prices, exacerbated by the geopolitical situation, are projected to drive coal consumption to a record high this year. This forecast represents a significant deviation from earlier predictions. At the end of the previous year, the IEA had anticipated a slight decrease in global coal demand for the current year, with a projected decline by 2030. Instead, demand is now expected to increase by approximately 1.2 percent.
This shift is being driven by strategic decisions in major energy-consuming regions. Europe, China, South Korea, and Japan have all reportedly transitioned from gas to coal for a portion of their electricity generation needs. This realignment is a direct response to the elevated and volatile natural gas prices. The increased demand for coal is further amplified by the surge in electricity consumption for cooling purposes during the El Niño-induced heatwaves.
Supply-side concerns are also contributing to the upward pressure on coal prices. Indonesia, the world’s largest coal exporter, experienced its lowest monthly coal shipments in five years in September. This reduction is attributed to low water levels in critical river transport routes, hindering the movement of coal, and government-imposed export quotas. These quotas are designed to support domestic coal prices long-term and bolster state revenues, further tightening global supply.

Brent Crude Oil: Pipeline Attacks and Persistent Geopolitical Risk
Brent crude oil prices have also been significantly influenced by geopolitical events, particularly concerning the stability of oil supply routes. A feared scenario has materialized with attacks targeting key oil infrastructure, specifically a critical pipeline. This pipeline had been instrumental in facilitating the movement of approximately five million barrels of crude oil per day from Saudi Arabia to the Red Sea port of Yanbu. Its operational capacity had helped to temper oil price surges, preventing a rapid ascent towards $200 per barrel, even amidst the ongoing blockade of the Strait of Hormuz.
The attacks on this vital artery of oil transport underscore the persistent and multifaceted risks to global energy security. While the Saudi oil giant, Saudi Aramco, has since partially restored the pipeline’s operation, bringing it to about 50 percent of its capacity, the underlying vulnerabilities remain. The potential for further attacks means that the market must continue to factor in a significant risk premium, contributing to price volatility and uncertainty. This situation highlights the delicate balance of power and the constant threat of disruption in a region critical to global energy supply.
The implications of these attacks extend beyond immediate price fluctuations. They serve as a stark reminder of the strategic importance of energy infrastructure and the potential for targeted actions to significantly impact global markets. The ongoing geopolitical tensions in the region continue to cast a long shadow over the stability of oil prices, making them susceptible to sudden and substantial shifts based on security developments.
Cocoa: The August Winner Becomes September’s Loser
In stark contrast to the gains seen in energy and some agricultural commodities, cocoa has experienced a significant price decline in September, falling by over 19 percent. This marks a reversal of fortune for the commodity, which had been the top performer in August.

Similar to the dynamics observed in orange juice, these sharp price fluctuations are not uncommon in the cocoa market. As an agricultural commodity, cocoa is subject to the inherent volatility associated with weather patterns, crop diseases, and market liquidity. The cocoa market, like that of orange juice, is characterized by relatively low liquidity, meaning that substantial trades can have a pronounced impact on prices. The rapid decline suggests that traders may have anticipated sufficient near-term supply, leading to a sell-off.
However, the longer-term outlook for cocoa remains a concern. Ghana, the world’s second-largest cocoa producer, has warned of a potential production shortfall exceeding one-third in the 2026/27 season. This forecast is attributed to heavy rainfall, which has increased the risk of plant diseases. This threat is further exacerbated by the potential impacts of El Niño, which could lead to unfavorable growing conditions. Such a significant contraction in supply could lead to a substantial deficit in the medium term, potentially reversing the recent price slump and driving prices upward in the future. The interplay of immediate market sentiment and long-term supply-side risks creates a complex and unpredictable environment for cocoa traders and consumers alike.
Broader Implications and Market Outlook
The confluence of geopolitical conflict and climate change continues to exert significant pressure on global commodity markets. The events of September underscore the interconnectedness of these factors and their ability to trigger rapid and substantial price movements across diverse asset classes.
For energy markets, the ongoing tensions in the Middle East and the resulting disruption to oil supply routes, coupled with the increased demand for coal driven by high gas prices and El Niño-related cooling needs, paint a complex picture. While the return of some Saudi oil pipeline capacity offers a degree of relief, the underlying geopolitical risks remain a potent force. The renewed reliance on coal, a fuel with significant environmental implications, also raises questions about the pace and direction of global energy transitions.

In agricultural markets, the impact of El Niño is proving to be a dominant theme. The projected decline in orange juice production and the potential future deficit in cocoa supply highlight the vulnerability of global food systems to climatic shifts. While short-term price corrections can occur due to market sentiment, the fundamental pressures from reduced yields and increased demand suggest that many agricultural commodities may face sustained price increases in the coming months and years.
The performance of the Goldman Sachs Commodity Index at 4.5 percent for the month signals a broader inflationary pressure stemming from these commodity market dynamics. As these trends continue, policymakers and businesses will need to navigate a landscape characterized by heightened uncertainty, the need for resilient supply chains, and the ongoing challenge of balancing energy security with environmental sustainability. The coming months will likely see continued volatility as markets react to further developments in the geopolitical arena and evolving climate forecasts.